RyRo Loan Centre

First home buyer mortgage broker, Sydney

First Home Buyer Broker in Sydney

We work out which NSW and federal schemes you qualify for, combine them, then find a lender and loan that fit. Everything you need to buy your first home in NSW, with every dollar of support you're entitled to.

Sumit Joshi, principal broker at RyRo Loan Centre

Book your free first home buyer assessment

No credit check, no obligation. Tell us what you're buying.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • 5% deposit, no LMI, up to $1.5M in Sydney
  • No stamp duty up to $800,000
  • Based in Norwest, Sydney. $0 broker fees
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Overview

First Home Buying in NSW in 2026: Where Things Stand

As a dedicated first home buyer broker in Sydney, RyRo Loan Centre helps you work through every grant, scheme and lender option available, so you enter the market with every dollar of support you're entitled to.

Sydney has not become cheaper. Saving a 20% deposit plus stamp duty, legal fees and moving costs takes most buyers years. The good news: first home buyers in NSW in 2026 have more government support than ever, and several federal and state programs can be used together to cut your upfront costs and the deposit you need.

Minimum deposit with the 5% Deposit Scheme, no LMI, no income caps
5%
Source: firsthomebuyers.gov.au, checked 9 Nov 2026
Price cap in Sydney and the NSW regional centres
$1.5M
Source: firsthomebuyers.gov.au, checked 9 Nov 2026
No stamp duty for eligible first home buyers up to this price
$800K
Source: Revenue NSW, checked 9 Nov 2026
First Home Owner Grant on a new home up to $600,000
$10K
Source: Revenue NSW, checked 9 Nov 2026

What changed, and why the order of steps matters

The biggest change came on 1 October 2025, when the Australian Government 5% Deposit Scheme dropped its income caps and its limit on places, and lifted its price caps to $1,500,000 in Sydney and the NSW regional centres. A 5% deposit with no Lenders Mortgage Insurance now reaches far more of the Sydney market than it did before.

Help to Buy opened to applications on 5 December 2025, adding a shared equity option with a 2% deposit for buyers on lower and middle incomes. The NSW stamp duty exemption to $800,000 and the $10,000 First Home Owner Grant for new homes are still in place.

The combined value of grants, stamp duty savings and LMI you avoid can run to tens of thousands of dollars for an eligible NSW buyer who knows how to use the schemes together. Understanding what you qualify for, and in what combination, is where we start.

Hand holding a set of house keys above small model houses
Most first home buyers can use two or three programs on the same purchase.Photo: Jakub Żerdzicki / Unsplash

Not sure where to start?

Tell us your budget and your deposit. Sumit works out which schemes you qualify for and what they are worth to you.

Get my first home plan

Free, no obligation and no credit check.

Quick answer

What does a first home buyer mortgage broker do?

A first home buyer mortgage broker works out which grants and schemes you qualify for, finds a lender that offers them and suits your income, and runs the loan and the scheme paperwork through to settlement. For a home loan the lender pays the broker, so it costs you nothing.

RyRo Loan Centre is a Sydney first home buyer broker based in Norwest in the Hills District. We help first home buyers combine the 5% Deposit Scheme, the NSW stamp duty exemption, the First Home Owner Grant and the First Home Super Saver Scheme, and we compare 50+ lenders to find the one that says yes on the best terms.

  • Check every scheme

    Your eligibility for each grant and scheme, worked out before you look at a single property.

  • Compare the lenders

    Scheme lenders do not all price or assess the same way. We compare them across 50+ lenders.

  • Handle the paperwork

    Scheme forms, the grant application and lender documents, lodged in the right order.

  • Stay to settlement

    Valuation, formal approval and settlement, alongside your conveyancer.

Quick answer

Is a mortgage broker free for first home buyers?

Yes, at RyRo. For a home loan we are paid a commission by the lender when your loan settles, so there is no broker fee to you. Under the Best Interests Duty we must act in your interests, not the lender's.

Sumit · 0:24
First home buyer? Questions to ask firstSumit Joshi, RyRo Loan Centre · questions a first home buyer should ask firstWatch with transcript

Grants and schemes, updated 9 Nov 2026

The Seven Major Programs for NSW First Home Buyers (2026)

Each program in one line, with the figure that matters and a link to the full guide. Open any card for the detail, or ask us which ones you qualify for.

  1. 1. First Home Owner Grant NSW (FHOG): $10,000 Cash Grant

    A $10,000 payment from the NSW Government for first home buyers who buy or build a new home: up to $600,000 for a new home, or $750,000 combined for land plus a building contract.

    $10,000

    new homes only

    The detail

    The grant applies only to new homes: homes never lived in, off-the-plan purchases, newly built homes and substantially renovated homes. It does not apply to established homes that have been lived in, which make up most of the Sydney market.

    If you're buying a new apartment off the plan within the price limit, or building with a builder, the grant can apply. If you're buying an existing house in the Hills District that has been lived in before, it doesn't.

    You must move in within 12 months and live there for at least 12 continuous months (contracts from 1 July 2023). You can apply through your lender when you arrange finance. It can be combined with the stamp duty exemption, the 5% Deposit Scheme and the First Home Super Saver Scheme. Source: Revenue NSW, checked 9 Nov 2026.

  2. 2. Australian Government 5% Deposit Scheme: Buy with 5% Deposit, No LMI

    The government guarantees part of your loan, so you buy with a 5% deposit and pay no Lenders Mortgage Insurance. Since 1 October 2025: no income caps, unlimited places, and a $1,500,000 cap in Sydney.

    5%

    deposit, no LMI

    The detail

    The scheme (formerly the Home Guarantee Scheme, which included the First Home Guarantee) is the single biggest change to first home buying in NSW in recent years. The guarantee means the lender treats your loan as if you had a bigger deposit, so no LMI is charged. LMI on a Sydney purchase with a 5% deposit can otherwise cost tens of thousands of dollars.

    What changed on 1 October 2025: the limit on places was removed, so there is no waiting list; the income caps were removed; and the price caps went up. In NSW the cap is $1,500,000 in Sydney and the regional centres (Central Coast, Coffs Harbour to Grafton, Illawarra, Mid North Coast, Richmond to Tweed, and Newcastle and Lake Macquarie) and $800,000 elsewhere.

    It is a guarantee, not a cash grant. You apply through a participating lender, and you must be an Australian citizen or permanent resident aged 18 or over, a first home buyer or someone who has not owned property in Australia in the last 10 years, and planning to live in the home. It can be combined with the First Home Owner Grant, the stamp duty exemption and the FHSS. Source: firsthomebuyers.gov.au, checked 9 Nov 2026.
  3. 3. Family Home Guarantee: 2% Deposit for Single Parents

    Single parents and single legal guardians of a dependent child can buy with a 2% deposit and no LMI. It now sits inside the 5% Deposit Scheme, with no income caps and no waiting list.

    2%

    deposit, single parents

    The detail

    The option is for single parents and single legal guardians of one or more dependent children. The official eligibility page does not require you to be a first home buyer: you must not have any other property interest once your new home settles, so it can suit a parent coming back into the market after a separation. Sumit confirms your position before you apply.

    Since the 1 October 2025 changes it has no income caps and unlimited places, and it uses the same price caps as the 5% Deposit Scheme ($1,500,000 in Sydney). A 2% deposit on a $750,000 home is $15,000. You apply through the same participating lenders. Source: firsthomebuyers.gov.au, checked 9 Nov 2026.
  4. 4. Help to Buy Scheme: Government Co-Ownership with 2% Deposit

    The government contributes up to 40% of a new home or 30% of an existing home and owns that share. Income caps apply ($103,000 individual, $165,000 joint or single parent) and there are 10,000 places a year.

    2%

    deposit, shared equity

    The detail

    Help to Buy opened to applications on 5 December 2025 and works very differently from the 5% Deposit Scheme. Instead of guaranteeing part of your loan, the government puts money toward the price and owns that share of the home. You live in it, you borrow less, and you repay the government's share when you can or when you sell.

    It suits buyers with a steady income who can manage repayments but have not saved a large deposit. All applicants must be Australian citizens, and you apply through a participating lender. You use either Help to Buy or the 5% Deposit Scheme on a purchase, not both. Price caps differ by area: check yours in the official tool. Source: firsthomebuyers.gov.au, checked 9 Nov 2026.
    Help to Buy vs the First Home Guarantee vs 5% deposit, compared

  5. 5. NSW Stamp Duty Exemption and Concession (FHBAS)

    No transfer duty on a new or existing home up to $800,000, and a reduced rate above $800,000 and under $1 million. At $800,000 that saves $30,187 at the NSW rates from 1 July 2026.

    $0

    duty to $800,000

    The detail

    Stamp duty (officially transfer duty in NSW) is one of the largest upfront costs of any purchase. At the general rates from 1 July 2026, duty on a $750,000 home is $27,937, and on an $800,000 home $30,187. The First Home Buyers Assistance Scheme removes or reduces that for eligible first home buyers.

    The thresholds: full exemption at $800,000 or less; a concessional rate above $800,000 and under $1 million; no concession from $1 million. Vacant land: full exemption at $350,000 or less, concessional above $350,000 and under $450,000. Unlike the grant, it applies to new and existing homes. You must move in within 12 months and live there for 12 continuous months. Source: Revenue NSW, checked 9 Nov 2026.

    It can be combined with the First Home Owner Grant (new homes), the 5% Deposit Scheme, the 2% option for single parents, Help to Buy and the FHSS.

  6. 6. First Home Super Saver Scheme (FHSS): Save Your Deposit in Super

    Make voluntary contributions to super, then release them plus associated earnings for your deposit. Up to $15,000 a year and $50,000 in total count, per person, so a couple can use up to $100,000.

    $50K

    per person, plus earnings

    The detail

    The tax treatment is the point: before-tax contributions are generally taxed at 15% in your fund, less than most people's marginal rate, so your deposit can grow faster than in a savings account. Each partner applies separately.

    Timing matters. Request your FHSS determination through myGov before ownership of a home transfers to you; if you sign a contract first, request the release within 90 days of signing. The ATO says a release usually takes 15 to 20 business days, so plan around your settlement date. Source: ato.gov.au, checked 3 Nov 2026.

    FHSS 2026 Guide (Blog)

  7. 7. Regional First Home Buyer Guarantee: 5% Deposit in Regional NSW, No LMI

    Regional buyers get the same 5% deposit and no LMI. The official scheme site now lists regional buyers under the 5% Deposit Scheme, with a $1,500,000 cap in the regional centres and $800,000 elsewhere in NSW.

    $800K

    cap, rest of NSW

    The detail

    The Regional First Home Buyer Guarantee helped first home buyers in regional areas buy with a 5% deposit and no LMI. Since 1 October 2025, regional NSW buyers use the 5% Deposit Scheme on the same terms as Sydney buyers: unlimited places and no income caps.

    The price cap depends on where you buy: $1,500,000 in the NSW regional centres (Central Coast, Coffs Harbour to Grafton, Illawarra, Mid North Coast, Richmond to Tweed, and Newcastle and Lake Macquarie) and $800,000 in the rest of NSW. You must be a first home buyer or not have owned property in Australia in the last 10 years, a citizen or permanent resident, and aged 18 or over. Source: firsthomebuyers.gov.au, checked 9 Nov 2026.
Got questions or need help? Book a free call with us.

Sumit · 1:26
The 5% Deposit Scheme and NSW stamp duty togetherSumit Joshi, RyRo Loan Centre · the 5% Deposit Scheme and NSW stamp duty togetherWatch with transcript

Maximise support

How Much Government Support Can You Actually Access?

These schemes are not either or. Most eligible NSW first home buyers can use several at once. Three illustrative examples of what that looks like (not client stories; your figures depend on your loan and lender).

Sumit · 1:22
First home buyer stamp duty in NSW, explainedSumit Joshi, RyRo Loan Centre · no duty to $800,000, a concession to $1 millionWatch with transcript
  • Bright living room with a grey sofa, indoor plants and a large window
    Photo: Minh Pham / Unsplash

    Example 1: Couple buying a new off-the-plan apartment, $580,000, Hills District

    First Home Owner Grant
    $10,000 (new home under $600,000)
    Stamp duty exemption
    $20,287 in duty saved
    5% Deposit Scheme
    $29,000 deposit instead of $116,000 at 20%, and no LMI
    FHSS (if contributing to super)
    Up to $50,000 each counted towards the deposit

    Total government support: $30,287 in grant and duty savings, plus the LMI you avoid

  • Weatherboard cottage behind a white picket fence
    Photo: Paddy Pohlod / Unsplash

    Example 2: Single parent, buying existing home, $750,000

    Stamp duty exemption
    $27,937 in duty saved
    2% option for single parents
    $15,000 deposit instead of $150,000 at 20%, and no LMI
    First Home Owner Grant
    Not available (established home)

    Total government support: $27,937 in duty saved, plus the LMI you avoid

  • Modern two-storey house with a lit entry and garage at dusk
    Photo: Brian Babb / Unsplash

    Example 3: Professional couple buying established home, $1,100,000, Sydney

    First Home Owner Grant
    Not available (existing home)
    Stamp duty exemption
    Not available ($1 million or more)
    5% Deposit Scheme
    $55,000 deposit instead of $220,000 at 20%, and no LMI

    Total government support: The LMI you avoid, plus any FHSS benefit

    Before 1 October 2025 the Sydney cap was lower, so this purchase would not have qualified. The $1,500,000 cap now covers it.

Duty figures use the NSW general transfer duty rates from 1 July 2026 (Revenue NSW). Work out your own with the NSW stamp duty calculator and see what LMI would have cost with the LMI calculator.

Work out my total support

Got questions or need help? Book a free call with us.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824

Low deposit

The 4 Pathways to Buying Without a 20% Deposit

A 20% deposit is no longer the only way in. These are the four routes we use most, and who each one suits.

  • 5% Deposit Scheme

    Government-guaranteed, no LMI. 5% minimum deposit, no income caps, unlimited places, $1,500,000 Sydney cap. Best for: first home buyers with a stable income and 5% saved.

    Read the detail

    Minimum deposit: 5% of the purchase price, with a government guarantee so no LMI is charged. For first home buyers and anyone who has not owned property in Australia in the last 10 years. Unlimited places since 1 October 2025.

  • Family Home Guarantee

    2% deposit, no LMI, for single parents or single legal guardians with a dependent child. Same $1,500,000 Sydney cap. Best for: single parents entering or re-entering the market.

    Read the detail

    Minimum deposit: 2% of the purchase price. You must not hold any other property interest once the new home settles. No income caps and unlimited places since 1 October 2025.

  • Help to Buy

    2% deposit with the government as a co-owner of up to 30% (existing) or 40% (new). Income caps and 10,000 places a year. Best for: lower to middle income buyers who want smaller repayments.

    Read the detail

    Income must be at or below $103,000 for individuals or $165,000 for joint applicants and single parents. All applicants must be Australian citizens. You share the home's value with the government until you buy its share back or sell.

  • Guarantor Home Loan

    A family member uses equity in their home as extra security, so you can buy with a very low or no deposit without LMI. Best for: strong income, little deposit, parents with equity.

    Read the detail

    No government program: it is structured through a standard home loan with a lender that accepts guarantors. The guarantee is usually limited to part of the loan and released once you reach enough equity. Read our guarantor home loan guide.

Find my low deposit pathway

Got questions or need help? Book a free call with us.

Sumit · 0:47
Four tips for the best chance of approvalSumit Joshi, RyRo Loan Centre · four tips for the best chance of approvalWatch with transcript

Schemes overview table

NSW First Home Buyer Schemes Comparison 2026

All the major schemes side by side. Updated November 2026 from the official sources; each scheme name opens its full guide.

NSW first home buyer schemes compared, 2026
SchemeWho it is forMin depositNo LMISydney capCash to you
First Home Owner Grant (NSW)First home buyers, new homes onlyAnyNot applicable$600,000 new home$10,000
Stamp duty exemption (NSW)First home buyers, new or existingAnyNot applicableExempt to $800,000Duty saving
5% Deposit Scheme (federal)First home buyers, or no property in 10 years5%Yes$1,500,000No
Family Home Guarantee (federal)Single parents and guardians2%Yes$1,500,000No
Help to Buy (federal)Citizens under the income caps2%No LMISee official toolShared equity
FHSS (federal, ATO)First home buyers saving in superAnyNot applicableNo capTax advantage
Regional buyers (federal)Buyers outside Sydney5%Yes$800,000 rest of NSWNo

Sources: firsthomebuyers.gov.au, Revenue NSW, checked 9 Nov 2026; ato.gov.au. Combinations: the grant, the duty exemption, the 5% Deposit Scheme and the FHSS can usually be used together; Help to Buy is used instead of the 5% Deposit Scheme. Got questions or need help? Book a free call with us.

Myth busting

Common Misconceptions About First Home Buyer Support

Five things we hear on almost every first call, and what is actually true in 2026.

Get Expert Advice, Free

Tell us what you need and we'll match you to the right option. No credit check, no obligation.

Get my free strategy call

We generally respond within an hour.

  • "The FHOG will cover my deposit."

    The $10,000 grant is paid at or after settlement, so it cannot be your deposit at exchange. You still need your deposit in cleared funds. The grant is useful for moving costs, furniture or your savings buffer.

  • "I can't afford to buy in Sydney."

    Sydney is expensive, but the 5% Deposit Scheme (now to $1,500,000), the stamp duty exemption (worth $30,187 at $800,000) and the FHSS (up to $100,000 for a couple) have changed what is within reach. A $60,000 deposit is 5% of a $1,200,000 home.

  • "The 5% Deposit Scheme ran out last year."

    Not anymore. From 1 October 2025 the limit on places was removed. The scheme is now unlimited, with no waiting list.

  • "I need to choose between the grant and the scheme."

    In many cases you can use several at once. The grant, the stamp duty exemption and the 5% Deposit Scheme can all apply to a new home up to $600,000. We work through the best combination for your situation.

  • "The Regional First Home Buyer Guarantee is still a separate scheme."

    The official scheme site no longer lists it separately. Regional NSW buyers use the 5% Deposit Scheme with unlimited places: $1,500,000 in the regional centres and $800,000 in the rest of NSW.

Eligibility

Am I Eligible? The Key Questions

The core eligibility rules that apply across most schemes. Each scheme has its own detail, which we check for you.

  • You are an Australian citizen or permanent residentHelp to Buy is for citizens only. For the NSW grant and duty exemption, at least one buyer must be a citizen or permanent resident.
  • You have not owned residential property in Australia beforeFor the 5% Deposit Scheme, not owning property or land in Australia in the last 10 years also counts.
  • You will live in the homeIt must be your principal place of residence, not an investment.
  • The price is within the cap for its locationFor example $1,500,000 in Sydney for the 5% Deposit Scheme, $600,000 for the grant on a new home.
  • You apply through a participating lenderNot every lender offers every scheme. We know which ones do.

What about joint buyers?

For the 5% Deposit Scheme you can apply on your own or jointly with one other person: a partner, friend or family member. Each applicant must meet the eligibility rules.

What if I have HECS/HELP debt?

HECS/HELP is included in your serviceability assessment by lenders, and it reduces your borrowing capacity. We assess it as part of every first home buyer review. In most cases it doesn't stop you borrowing, but it does affect how much.

What if I've owned an investment property?

If you've owned any residential property in Australia (including an investment property) you are generally not a first home buyer for the grant, the stamp duty exemption or the 5% Deposit Scheme. There are narrow exceptions, such as the 10 year rule for the 5% Deposit Scheme. If you're unsure, speak to us before assuming you're ineligible.

What if I'm self-employed?

Self-employed applicants can use the same first home buyer schemes as PAYG applicants. The difference is the documents: typically two years of tax returns, business financials and a Notice of Assessment from the ATO. We match self-employed first home buyers to lenders whose assessment suits their income. See low doc loans for the self-employed.

Check my eligibility

Got questions or need help? Book a free call with us.

Sumit · 1:35
What banks look at before they lendSumit Joshi, RyRo Loan Centre · income, debts and savings: what banks look atWatch with transcript

The process

How Buying Your First Home Works: Step by Step

Six steps from your first call to the keys. We run the lender and scheme side of each one.

  1. Step 1

    Step 1: Understand what you can borrow and what schemes you qualify for, before looking at a single property.

    We assess your income, expenses, existing debts (including HECS), deposit and any FHSS contributions, identify which schemes you qualify for and add up the support available. This first conversation is free and takes about 30 to 45 minutes.

  2. Step 2

    Step 2: Get pre-approval.

    Pre-approval is a lender letter confirming how much they will lend, subject to finding a suitable property. With the 5% Deposit Scheme, the lender also reserves your scheme place with Housing Australia. It often takes 2 to 5 business days once your documents are ready, and is usually valid for about 90 days, renewable.

  3. Step 3

    Step 3: Search for a property within your budget and scheme caps.

    Know your numbers before you search. The 5% Deposit Scheme covers homes up to $1,500,000 in Sydney. The grant needs a new home up to $600,000. The full stamp duty exemption needs a price of $800,000 or less, and the concession ends at $1 million.

  4. Step 4

    Step 4: Make an offer or bid at auction.

    With pre-approval in hand you can move quickly. We manage the lender so formal approval follows once a specific property is found.

  5. Step 5

    Step 5: Exchange contracts and complete due diligence.

    Once an offer is accepted or the hammer falls, you exchange contracts and pay the deposit (commonly 10%, sometimes less by agreement). Your solicitor or conveyancer runs the searches, reviews the contract and handles the duty assessment and exemption claim.

  6. Step 6

    Step 6: Settlement.

    Settlement is commonly 4 to 6 weeks after exchange. The lender pays the balance, ownership transfers, and any grant is processed. The duty exemption is applied when duty is assessed, so there is no extra step if your conveyancer has claimed it.

Start with step 1

Got questions or need help? Book a free call with us.

Or book a time on the strategy call page
Sumit · 1:07
Buying a home in NSW, step by stepSumit Joshi, RyRo Loan Centre · six steps from offer to settlement in NSWWatch with transcript

Stamp Duty Calculator NSW

Enter your property value and first home buyer status to see whether you qualify for the exemption or the concession, at 2026/27 NSW rates.
Open the full NSW stamp duty calculator

NSW purchase, 2026/27 rates

First home buyer?
Property type

Transfer duty

$9,796.75

Transfer duty you pay
$9,796.75
First home buyer concession
-$22,640.25
Full breakdown

First home buyer concession: home above $800,000 and below $1,000,000 pays a reduced amount. You save $22,640.25.

Transfer duty at general rates
$32,437
First home buyer concession
-$22,640.25
Transfer duty you pay
$9,796.75

Estimate for NSW only, at 2026/27 rates. Registration fees are the NSW Land Registry Services fees for one transfer and one mortgage. It leaves out conveyancing, settlement and lender fees, and surcharge land tax for foreign owners.

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

Aerial view of a new housing estate on the edge of a city, similar to the Hills District growth areas
New estates in the Hills and the north west, where new homes can qualify for the grant.Photo: Shanjir H / Unsplash
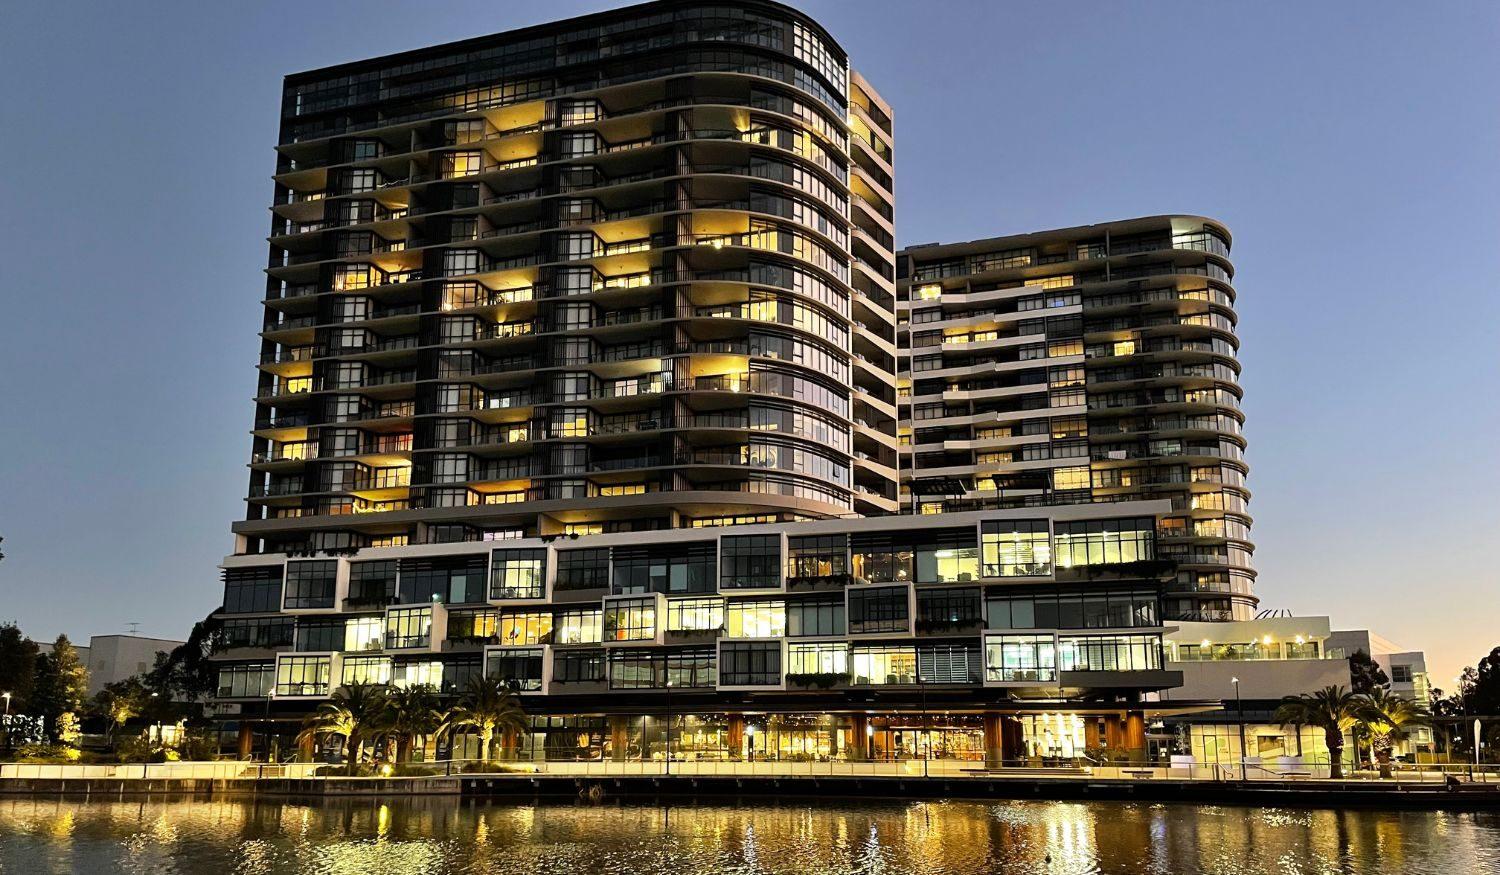
Tower A Esplanade building at Norwest at dusk, home of RyRo Loan Centre
Our office at Norwest, in the Hills District.

Hills District and Sydney

First Home Buyer Mortgage Brokers: Hills District and Greater Sydney

RyRo Loan Centre is based in Norwest. We help first home buyers across Sydney's Hills District and Greater Sydney assess their options, use the government schemes and find the right home loan.

  • Hills District first home buyers

    Castle Hill, Kellyville, Rouse Hill, Baulkham Hills, Norwest, The Hills, Bella Vista, Glenhaven, Round Corner, Cherrybrook, Pennant Hills, West Pennant Hills, Beecroft, Carlingford.
  • Greater Western and Northwest Sydney

    Parramatta, Westmead, Merrylands, Blacktown, Penrith, Seven Hills, Guildford, Auburn, Granville, Schofields, Box Hill, Marsden Park, Riverstone, The Gables, Windsor.
  • The rest of Sydney and NSW

    Inner West, Northern Suburbs, Eastern Suburbs, South Sydney and beyond, plus regional NSW: we help first home buyers wherever they buy.

Why the Hills District suits the scheme stack

The Hills District has seen strong price growth in recent years. A well-located new apartment in the area may qualify for both the grant and the stamp duty exemption, depending on its price and whether it is in a new development. We assess eligibility for every Hills District first home buyer before recommending a loan structure.

In the Hills and Greater Western Sydney, where new house and land packages and off-the-plan apartments are common, the grant, the stamp duty exemption and the 5% Deposit Scheme together can be particularly powerful. See house and land package loans. We build the best scheme combination for each client's situation.

Buying elsewhere in Sydney? Start with our Sydney mortgage broker page or see all our service areas.

From the blog

First home buyer guides from the RyRo blog

Start with the full NSW checklist, the deposit you actually need in Sydney right now, and a side by side look at the low deposit schemes.

Free PDF · 12 pages
Photo: Jakub Żerdzicki / Unsplash

Free 12-page guide

Hills District First Home Guarantee Eligibility Kit

How the First Home Guarantee works since 1 October 2025: a 5% deposit with no LMI, the $1.5 million Sydney price cap, and no income cap or place limit.

  • The 2026 caps and rules on one page
  • An eight-question eligibility self-check
  • Document checklist and a 12-week timeline to settlement

Google5.0 from 360+ Google reviews · Emailed to you straight away

Client stories

What First Home Buyers Say About Working With RyRo

More than 2,500+ Australians have worked with RyRo Loan Centre. Many came to us unsure what they were eligible for and left with a clear plan, often with schemes combined that they did not know they could use together. Rated 5.0 from 360+ Google reviews.

  • Varsha Mehra

    2 years ago on Google

    Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

    Varsha Mehra

    Google2 years ago on Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

  • Anshuman Bhardwaj

    2 years ago on Google

    Google

    Brilliant team and very responsive I am taking help of Sumit and his team for almost 10 years now from my first home to my 6th investment property . He is very helpful, ,informative and respectful to all my questions and needs. Always available and his Team (Dean) also is very knowledgeable . I have recommended them to lot of my friends and also heard good about them. Thanks team and keep up the good work

    Anshuman Bhardwaj

    Google2 years ago on Google

    Brilliant team and very responsive I am taking help of Sumit and his team for almost 10 years now from my first home to my 6th investment property . He is very helpful, ,informative and respectful to all my questions and needs. Always available and his Team (Dean) also is very knowledgeable . I have recommended them to lot of my friends and also heard good about them. Thanks team and keep up the good work

Start my first home plan

Free, no obligation and no credit check.

Read all 360+ Google reviews
Sumit · 2:56
Approved in days after her broker went quietSumit Joshi, RyRo Loan Centre · approved in days after her broker went quietWatch with transcript

Why RyRo

Why First Home Buyers Choose RyRo Loan Centre

  • We know the first home buyer schemes in detail, including the October 2025 changes.

    The rules changed on 1 October 2025 (unlimited places, higher caps and no income test for the 5% Deposit Scheme) and again when Help to Buy opened on 5 December 2025. We know what those changes mean for Hills District and Sydney buyers.
  • We compare 50+ lenders, not just the banks participating in schemes.

    Every government scheme runs through a participating lender, and they do not all offer the same rates, features or assessment rules. We compare them for your situation and pick the best mix of rate, features and serviceability for your income.
  • We calculate your full government support package before you start looking.

    Before you see a single property, we identify every scheme you qualify for, what that support is worth, the price range that keeps the schemes available, and the deposit you actually need (not the 20% default).
  • We manage the process from pre-approval through to settlement.

    Several schemes means several parties: the ATO for FHSS, your lender for the grant and the scheme place, your conveyancer for the duty exemption. We coordinate all of it so nothing is missed.
  • $0 broker fees.

    As a mortgage broker we are paid a commission by the lender at settlement, so there are no fees to you. Under the National Consumer Credit Protection Act we must act in your best interests, not the lender's. That is the Best Interests Duty, and it applies to every recommendation we make.
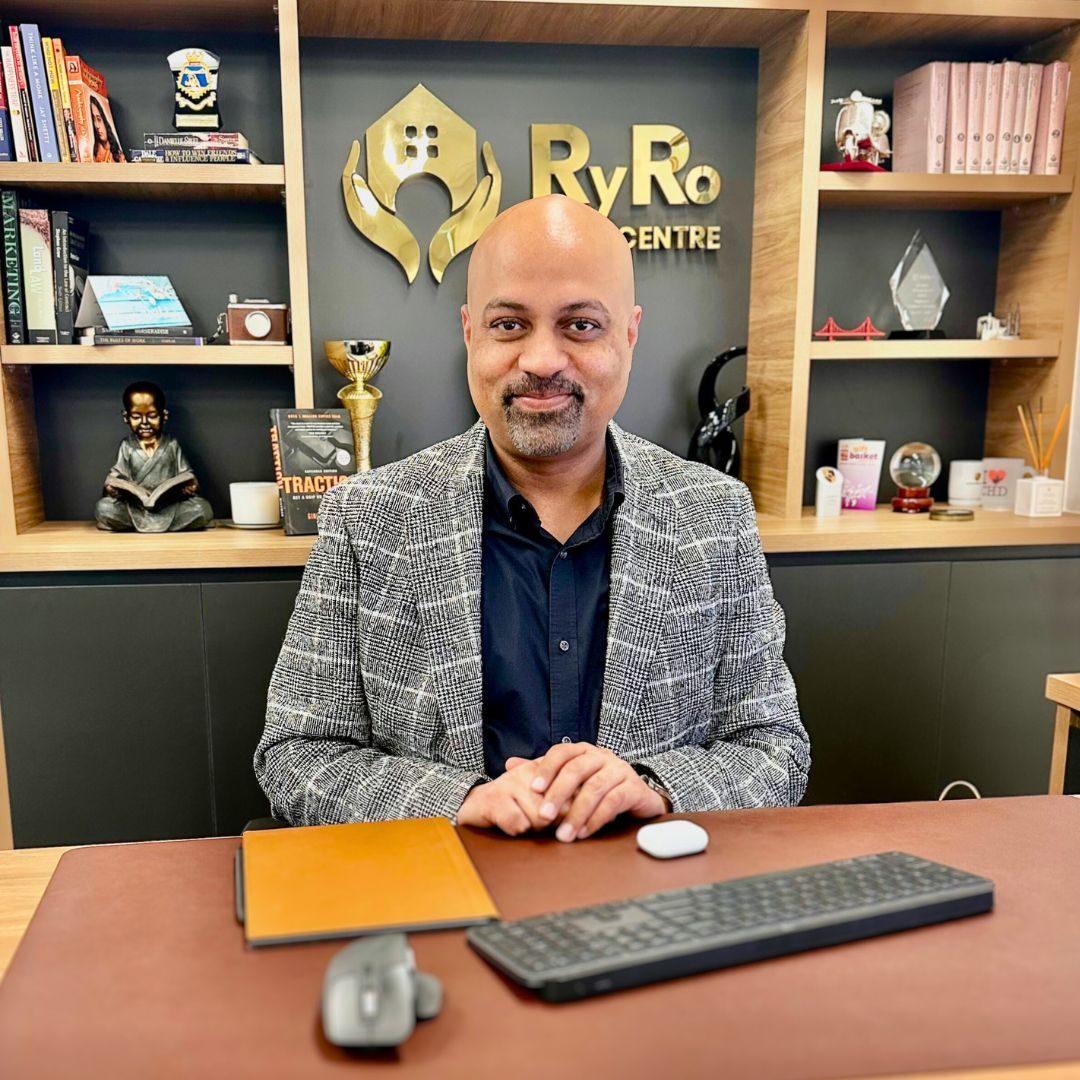
Sumit Joshi at his desk in front of the RyRo Loan Centre logo wall in Norwest
Sumit Joshi at the Norwest office.
Get my free strategy call

We generally respond within an hour.

Google reviews

What Our Customers Say

Rated 5.0 from 360+ Google reviews. Here are first home buyers, word for word.

Google

5.0

From 360+ Google reviews

Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan CentreWatch with transcript
Read all 360+ Google reviews
  • chris sukumar

    5 months ago on Google

    Google

    Sumit at Ryroloan Centre made our first home possible Five stars for Sumit Joshi at Ryroloan Centre. As first home buyers we had no idea where to start. Sumit was easy to contact from day one. He picked up calls, replied to texts fast, and explained everything in simple terms. He secured us a really good rate that beat what our bank offered. The whole pre-approval and settlement process was smooth because he stayed on top of every document and deadline. I want to thank Dean and whole team thank you all. Couldn’t recommend Sumit more highly if you’re a first home buyer.

    chris sukumar

    Google5 months ago on Google

    Sumit at Ryroloan Centre made our first home possible Five stars for Sumit Joshi at Ryroloan Centre. As first home buyers we had no idea where to start. Sumit was easy to contact from day one. He picked up calls, replied to texts fast, and explained everything in simple terms. He secured us a really good rate that beat what our bank offered. The whole pre-approval and settlement process was smooth because he stayed on top of every document and deadline. I want to thank Dean and whole team thank you all. Couldn’t recommend Sumit more highly if you’re a first home buyer.

  • Karra Le

    5 months ago on Google

    Google

    For someone like us who's completely new to the home loan process and first home buyers, they're very responsive and answered all the questions we have. Sumit, Dean and Meet helped us get through the process and supported us all the way till the end. Their team is very knowledgeable and professional. Highly recommended!

    Karra Le

    Google5 months ago on Google

    For someone like us who's completely new to the home loan process and first home buyers, they're very responsive and answered all the questions we have. Sumit, Dean and Meet helped us get through the process and supported us all the way till the end. Their team is very knowledgeable and professional. Highly recommended!

  • Rene Rose Mae Tagle

    8 months ago on Google

    Google

    Sumit was instrumental in securing our first home whilst maintaining a constant channel for communication. Very patient with all our queries. He helped navigate the first home buyer provisions available to us and provided us with the product we were after. Can highly recommend.

    Rene Rose Mae Tagle

    Google8 months ago on Google

    Sumit was instrumental in securing our first home whilst maintaining a constant channel for communication. Very patient with all our queries. He helped navigate the first home buyer provisions available to us and provided us with the product we were after. Can highly recommend.

  • Maria K

    10 months ago on Google

    Google

    We recently used Sumit and his team at RyRo to secure our very first home loan, and we honestly couldn’t be happier with the experience. From start to finish the team was super efficient and so accommodating to our needs. Everything was explained clearly, we were guided through each step, and made what could have been a stressful process feel completely seamless and straightforward. Sumit's professionalism and responsiveness gave us so much confidence, and we genuinely felt supported the whole way through. Thank you again to Sumit and his team!

    Maria K

    Google10 months ago on Google

    We recently used Sumit and his team at RyRo to secure our very first home loan, and we honestly couldn’t be happier with the experience. From start to finish the team was super efficient and so accommodating to our needs. Everything was explained clearly, we were guided through each step, and made what could have been a stressful process feel completely seamless and straightforward. Sumit's professionalism and responsiveness gave us so much confidence, and we genuinely felt supported the whole way through. Thank you again to Sumit and his team!

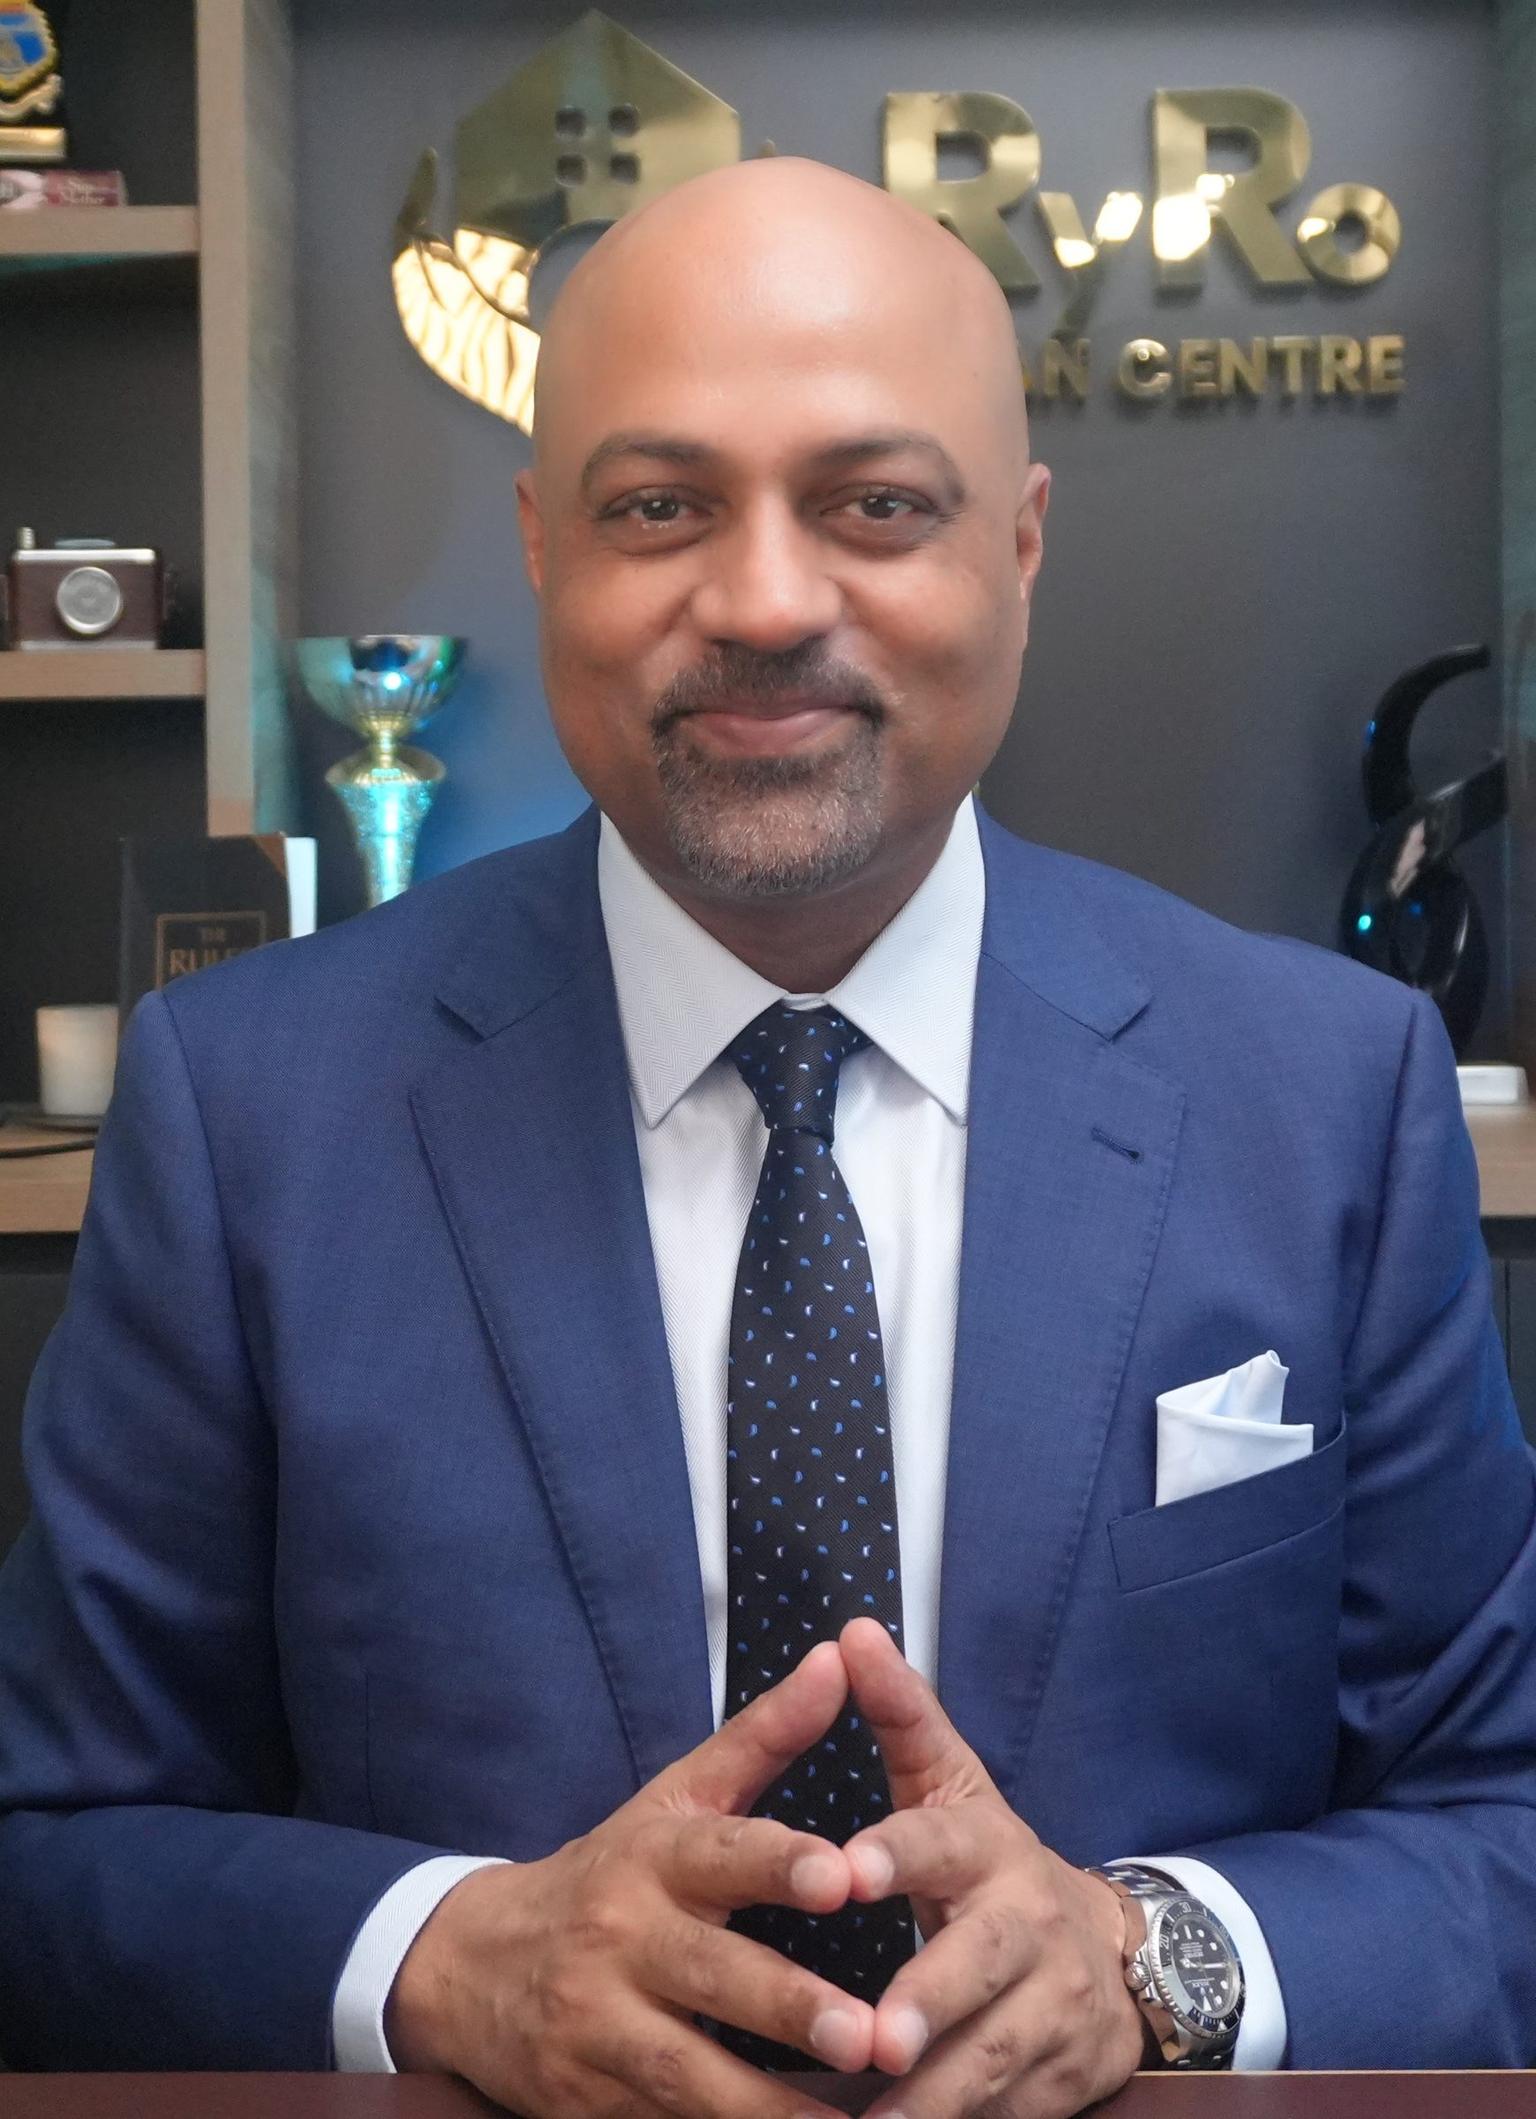
Sumit Joshi, principal mortgage broker at RyRo Loan Centre, in a blue suit at the Norwest office
Sumit Joshi, principal broker
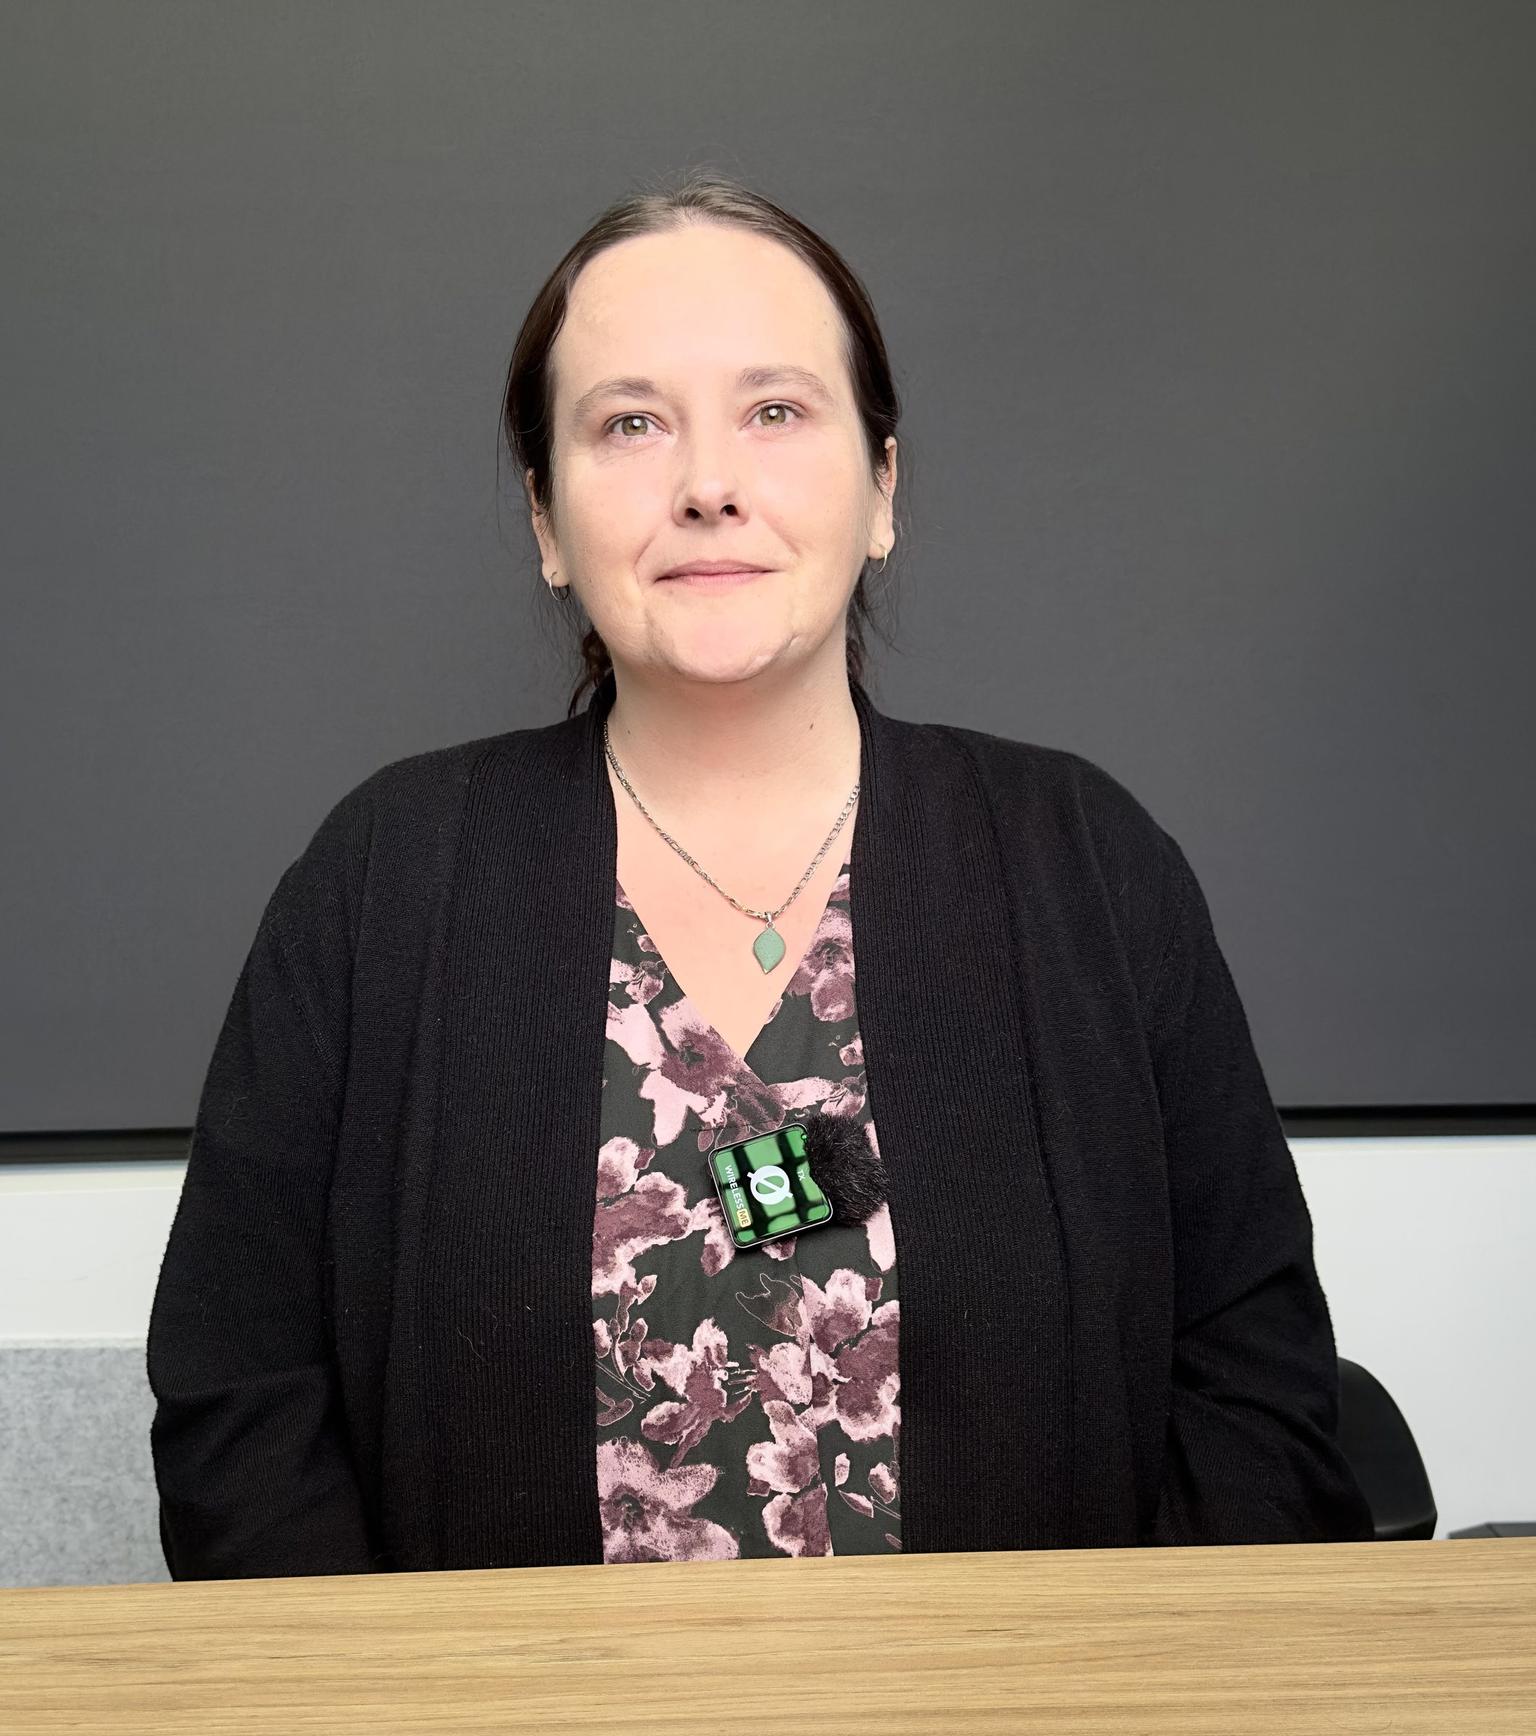
Kathryn Thomas, loan processor at RyRo Loan Centre
Kathryn Thomas, loan processing

Who you will deal with

The RyRo Team

As your first home buyer broker, we compare 50+ lenders and guide you through every grant, scheme and government program available in NSW, from strategy call to settlement. Sumit Joshi works out your schemes, your lender and your loan; Kathryn keeps the application moving through valuation, approval and settlement.

  • One broker, start to finish

    Sumit reads your details, calls you back and stays with your file through settlement.
  • 13+ years of experience

    Award-recognised broking and 2,500+ clients helped.
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge
Get in touch

Free, no obligation.

Meet the team

Answers on demand

Frequently Asked Questions

Answers to common questions about grants, schemes, stamp duty, LMI and the first home buyer process in NSW. Not covered here? Ask a first home buyer question or view all FAQs.

Quick answers

How much deposit do I need to buy my first home in Sydney?

+
Most first home buyers in Sydney need a 5% deposit, using the 5% Deposit Scheme to avoid Lenders Mortgage Insurance on homes up to the $1,500,000 Sydney price cap. Eligible single parents and legal guardians may need only 2%. Budget separately for legal fees and inspections, and for stamp duty if the price is above the $800,000 full exemption threshold. Read the 5% Deposit Scheme guide

Is there an income limit for the 5% Deposit Scheme?

+
No. Since 1 October 2025 the 5% Deposit Scheme has no income caps and no limit on places, so any eligible first home buyer can apply through a participating lender. The property price still has to be within the cap, which is $1,500,000 in Sydney. Help to Buy is different: it keeps income caps of $103,000 for individuals and $165,000 for joint applicants and single parents. Check your 5% Deposit Scheme eligibility

Can I get the First Home Owner Grant on an existing home in NSW?

+
No. The $10,000 NSW First Home Owner Grant only applies to new homes, such as newly built homes, off-the-plan purchases and substantially renovated homes. The price cap is $600,000 for a new home, or $750,000 combined for land plus a building contract. If you are buying an established home, the NSW stamp duty exemption on homes up to $800,000 is usually the bigger saving. Read the First Home Owner Grant guide

Can I use the First Home Super Saver Scheme with the 5% Deposit Scheme?

+
Yes. The First Home Super Saver Scheme can be combined with the 5% Deposit Scheme, the NSW stamp duty exemption and, for new homes, the First Home Owner Grant. You can count up to $50,000 of voluntary super contributions per person, plus associated earnings, towards your deposit. Request your FHSS determination from the ATO before ownership of any property transfers to you. Read the First Home Super Saver guide

How long does home loan pre-approval take for a first home buyer?

+
Pre-approval often takes 2 to 5 business days once your documents are ready, though it depends on the lender. If you are using the 5% Deposit Scheme, the participating lender also has to confirm your scheme place with Housing Australia, and RyRo manages that as part of your application. Get pre-approved before you make offers, so you know your price range and can move quickly. Estimate your borrowing power

Should I use a mortgage broker as a first home buyer?

+
For most first home buyers, yes. Government schemes are applied for through lenders, and not every lender takes part in every scheme. RyRo Loan Centre checks which grants and schemes you qualify for, compares the lenders that offer them, and lodges the scheme paperwork with your loan application. The service costs you nothing, because the lender pays RyRo when your loan settles. Book a free first home buyer strategy call

Grants & schemes

Can I use multiple schemes at the same time?

+
Yes, and most eligible buyers should. The common combinations are the First Home Owner Grant, the NSW stamp duty exemption and the 5% Deposit Scheme together for a new home up to $600,000; the stamp duty exemption or concession with the 5% Deposit Scheme for an established home; and any of these with the First Home Super Saver Scheme to grow your deposit. Help to Buy is used instead of the 5% Deposit Scheme, not with it. We work out the best combination for every first home buyer client.

What is the First Home Buyers Grant in NSW?

+
The NSW First Home Owner Grant (FHOG) is a $10,000 payment from the NSW Government for first home buyers who buy or build a new home, not an established one. A new home must cost $600,000 or less, and land plus a building contract must total $750,000 or less. You can apply through your lender, and you must move in within 12 months and live there for 12 continuous months.

What is the 5% Deposit Scheme and how do I apply?

+
The Australian Government 5% Deposit Scheme (formerly the Home Guarantee Scheme, which included the First Home Guarantee) lets eligible first home buyers buy with a 5% deposit without paying Lenders Mortgage Insurance, because the government guarantees part of the loan to the lender. From 1 October 2025 it has no income caps and unlimited places. You apply through a participating lender, not directly to Housing Australia. The Sydney price cap is $1,500,000. We find the participating lender that suits you best.

What's the difference between the 5% Deposit Scheme and Help to Buy?

+
Both let you buy with a small deposit. The 5% Deposit Scheme is a guarantee: you borrow the price less your deposit, the government guarantees part of the loan, and you avoid LMI. Help to Buy is shared equity: the government contributes up to 30% of an existing home or 40% of a new home and owns that share, so you borrow less. Help to Buy has income caps ($103,000 individual, $165,000 joint or single parent), 10,000 places a year and is for Australian citizens only. The 5% Deposit Scheme has no income caps and unlimited places. The right choice depends on your income, deposit and how you want to own the home.

Do first home buyers pay stamp duty in NSW?

+
Not on most homes. Under the First Home Buyers Assistance Scheme, eligible first home buyers pay no transfer duty on a new or existing home valued at $800,000 or less, and a reduced rate above $800,000 and under $1 million. From $1 million, full duty applies. At $800,000 the saving is $30,187 at the NSW rates from 1 July 2026. You claim it when duty is assessed, usually through your conveyancer, not as a later rebate.

What is the First Home Super Saver Scheme?

+
The FHSS lets you make voluntary contributions to your super (counted up to $15,000 a financial year and $50,000 in total) and later release them, plus associated earnings, for a first home deposit. Because super contributions can be taxed at a lower rate than your wage, your savings can grow faster. Request your FHSS determination before ownership of a home transfers to you; if you sign a contract first, request the release within 90 days of signing.

What first home buyer schemes are available in NSW in 2026?

+
In 2026, NSW first home buyers can use: the $10,000 First Home Owner Grant (new homes to $600,000, or land plus a building contract to $750,000); the stamp duty exemption (no duty to $800,000, a concession under $1 million); the 5% Deposit Scheme (5% deposit, no LMI, Sydney cap $1,500,000, no income caps, unlimited places); the 2% option for single parents and legal guardians (the Family Home Guarantee); the Help to Buy shared equity scheme (2% deposit, income caps, 10,000 places a year); and the First Home Super Saver Scheme. Most buyers can combine several of these.

What changed for first home buyers in October 2025?

+
The 1 October 2025 changes were the biggest shift in first home buyer support in years. Three things changed for the 5% Deposit Scheme: the income caps were removed, the limit on places was removed (no waiting list), and the property price caps went up, to $1,500,000 in Sydney and the NSW regional centres. The same rules now apply to the 2% option for single parents and legal guardians.

Deposits & borrowing

How much can I borrow as a first home buyer?

+
Your borrowing capacity depends on your income, living expenses, existing debts (including HECS), and each lender's assessment rules. Lenders reach different answers for the same household, so we calculate your capacity across several of them. Our borrowing power calculator gives you a first estimate in a minute, and a free assessment with us turns that into a real number from a real lender.

What is LMI and how do I avoid it?

+
Lenders Mortgage Insurance (LMI) is a premium you pay to protect the lender (not you) when you borrow more than 80% of a property's value. It can cost tens of thousands of dollars. You can avoid it by saving a 20% deposit, using the 5% Deposit Scheme, using the 2% option for eligible single parents, using a guarantor loan where a family member's equity supports your loan, or, for some professions, an LMI waiver. We find the right way to avoid it for you.

What is a guarantor home loan?

+
A guarantor home loan uses a family member's property (usually a parent's) as extra security for your loan. That can let you borrow more, or buy with a very small deposit without LMI. The guarantee is usually limited to part of the loan and can be released once you have paid down enough or the property has grown in value. The guarantor must get independent legal and financial advice before signing.

Process & options

How long does the first home buyer process take?

+
From first assessment to settlement, a typical path is: pre-approval (often 2 to 5 business days once documents are ready), the property search (weeks to months), formal approval once you find a property (often 1 to 3 weeks), and settlement (commonly 4 to 6 weeks after exchange). If you use the 5% Deposit Scheme, your lender confirms your scheme place with Housing Australia before settlement. We manage the timeline so every scheme application is lodged well before settlement day.

Can I buy a home while I'm renting? What about rentvesting?

+
Yes. You can buy your first property as an investment (rentvesting) while you keep renting where you live. Be aware that if you buy your first property as an investment rather than a home to live in, you generally will not qualify for the First Home Owner Grant, the stamp duty exemption or the 5% Deposit Scheme, because they require you to live in the property. Talk to us about whether rentvesting suits you and what it means for your scheme eligibility.

Can I buy with a friend or sibling?

+
Yes. The 5% Deposit Scheme lets you apply on your own or jointly with one other person, such as a partner, friend or family member, and each of you must meet the eligibility rules. Co-buying is becoming more common in Sydney. We structure co-buying loans carefully, including what happens if one of you wants to sell or your circumstances change.

What is the Help to Buy Scheme and how does it differ from the 5% Deposit Scheme?

+
Help to Buy is a federal shared equity scheme. The government contributes up to 40% of a new home's price or up to 30% of an existing home's price and owns that share, so you buy with a 2% deposit and borrow less. You repay the government's share when you can or when you sell. The 5% Deposit Scheme is a guarantee, not co-ownership: you borrow the price less your 5% deposit and avoid LMI. Help to Buy has income caps ($103,000 individual, $165,000 joint or single parent), 10,000 places a year and is for Australian citizens; the 5% Deposit Scheme has no income caps and unlimited places. You use one or the other on a purchase.

Do I need to be a permanent resident to access first home buyer schemes?

+
For the 5% Deposit Scheme you must be an Australian citizen or permanent resident, aged 18 or over. Help to Buy is for Australian citizens only. For the NSW First Home Owner Grant and the stamp duty exemption, at least one buyer must be an Australian citizen or permanent resident. Temporary visa holders generally cannot use these schemes on their own. We check eligibility for your visa status as part of every first home buyer assessment.

Checklist

First Home Buyer Checklist: Before You Start

Five stages, in order. Open each one for the list.

Stage 1: Before you talk to a lender

  • Check your credit score (free through the credit bureaus).
  • Close or reduce limits on credit cards and buy now pay later accounts you don't need.
  • Avoid changing jobs in the 3 months before applying.
  • Gather payslips, tax returns and 3 to 6 months of bank statements.
  • Know your HECS/HELP balance.
  • Understand the schemes you are likely eligible for.

Stage 2: Getting pre-approved

  • Choose a mortgage broker or lender.
  • Submit your documents for assessment.
  • Confirm which schemes you are eligible for and which combine.
  • Know your scheme's price cap for your target area.
  • Get a pre-approval letter, with your scheme place reserved if you use the 5% Deposit Scheme.

Stage 3: Property searching

  • Set a budget that respects your scheme's price cap.
  • Track which properties are new (grant eligible) and which are established.
  • Attend open homes with pre-approval in hand.
  • Engage a solicitor or conveyancer before you find a property.

Stage 4: Making an offer or bidding at auction

  • Have the contract reviewed before you bid or offer.
  • Private treaty: make your offer subject to finance and building and pest inspection.
  • Auction: confirm finance and inspections before you bid.
  • Pay the deposit on exchange (commonly 10%).

Stage 5: Between exchange and settlement

  • Arrange insurance for the property from exchange.
  • Keep your job and finances stable.
  • Let your solicitor handle the duty exemption claim and talk to the lender.
  • Plan for moving costs, utility connections and any urgent maintenance.

Want the long version? Read the full First Home Buyer Checklist NSW 2026. Got questions or need help? Book a free call with us.

Sumit · 0:45
Three ways to improve your credit scoreSumit Joshi, RyRo Loan Centre · three ways to improve your credit scoreWatch with transcript

Free first home buyer assessment

Start Your First Home Buyer Assessment

The best time to talk to a mortgage broker is before you start looking at properties, not after you've found one. A 30 to 45 minute conversation tells you what you're eligible for, how much you can borrow, which schemes apply, the deposit you actually need and the price range to target. It's free: lenders pay us at settlement, not you.
Sumit Joshi, principal broker at RyRo Loan Centre

Get started

We'll call you to discuss your first home buyer options. No obligation.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reads your details and calls you back
  • Every scheme you qualify for, added up
  • Free for home loans: the lender pays us
Sumit · 2:59
From two properties to four in six monthsSumit Joshi, RyRo Loan CentreWatch with transcript

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Broker fees for first home buyers
$0
“I was referred to Sumit by my cousin. He went above and beyond, responding to my questions and concerns even after hours, which made the entire process as a First Home Buyer seamless and stress free. I highly recommend. Thank you Sumit and team.”
Kathleen A · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026. General information only, not financial advice. Scheme rules and caps are set by the government and can change. Any lending is subject to the lender's assessment.

Get my free loan review