RyRo Loan Centre

Free mortgage repayment calculator

Loan Repayment Calculator

Calculate your monthly loan repayments and see how much interest you'll pay over the life of your loan. Perfect for planning your budget and comparing different loan options.

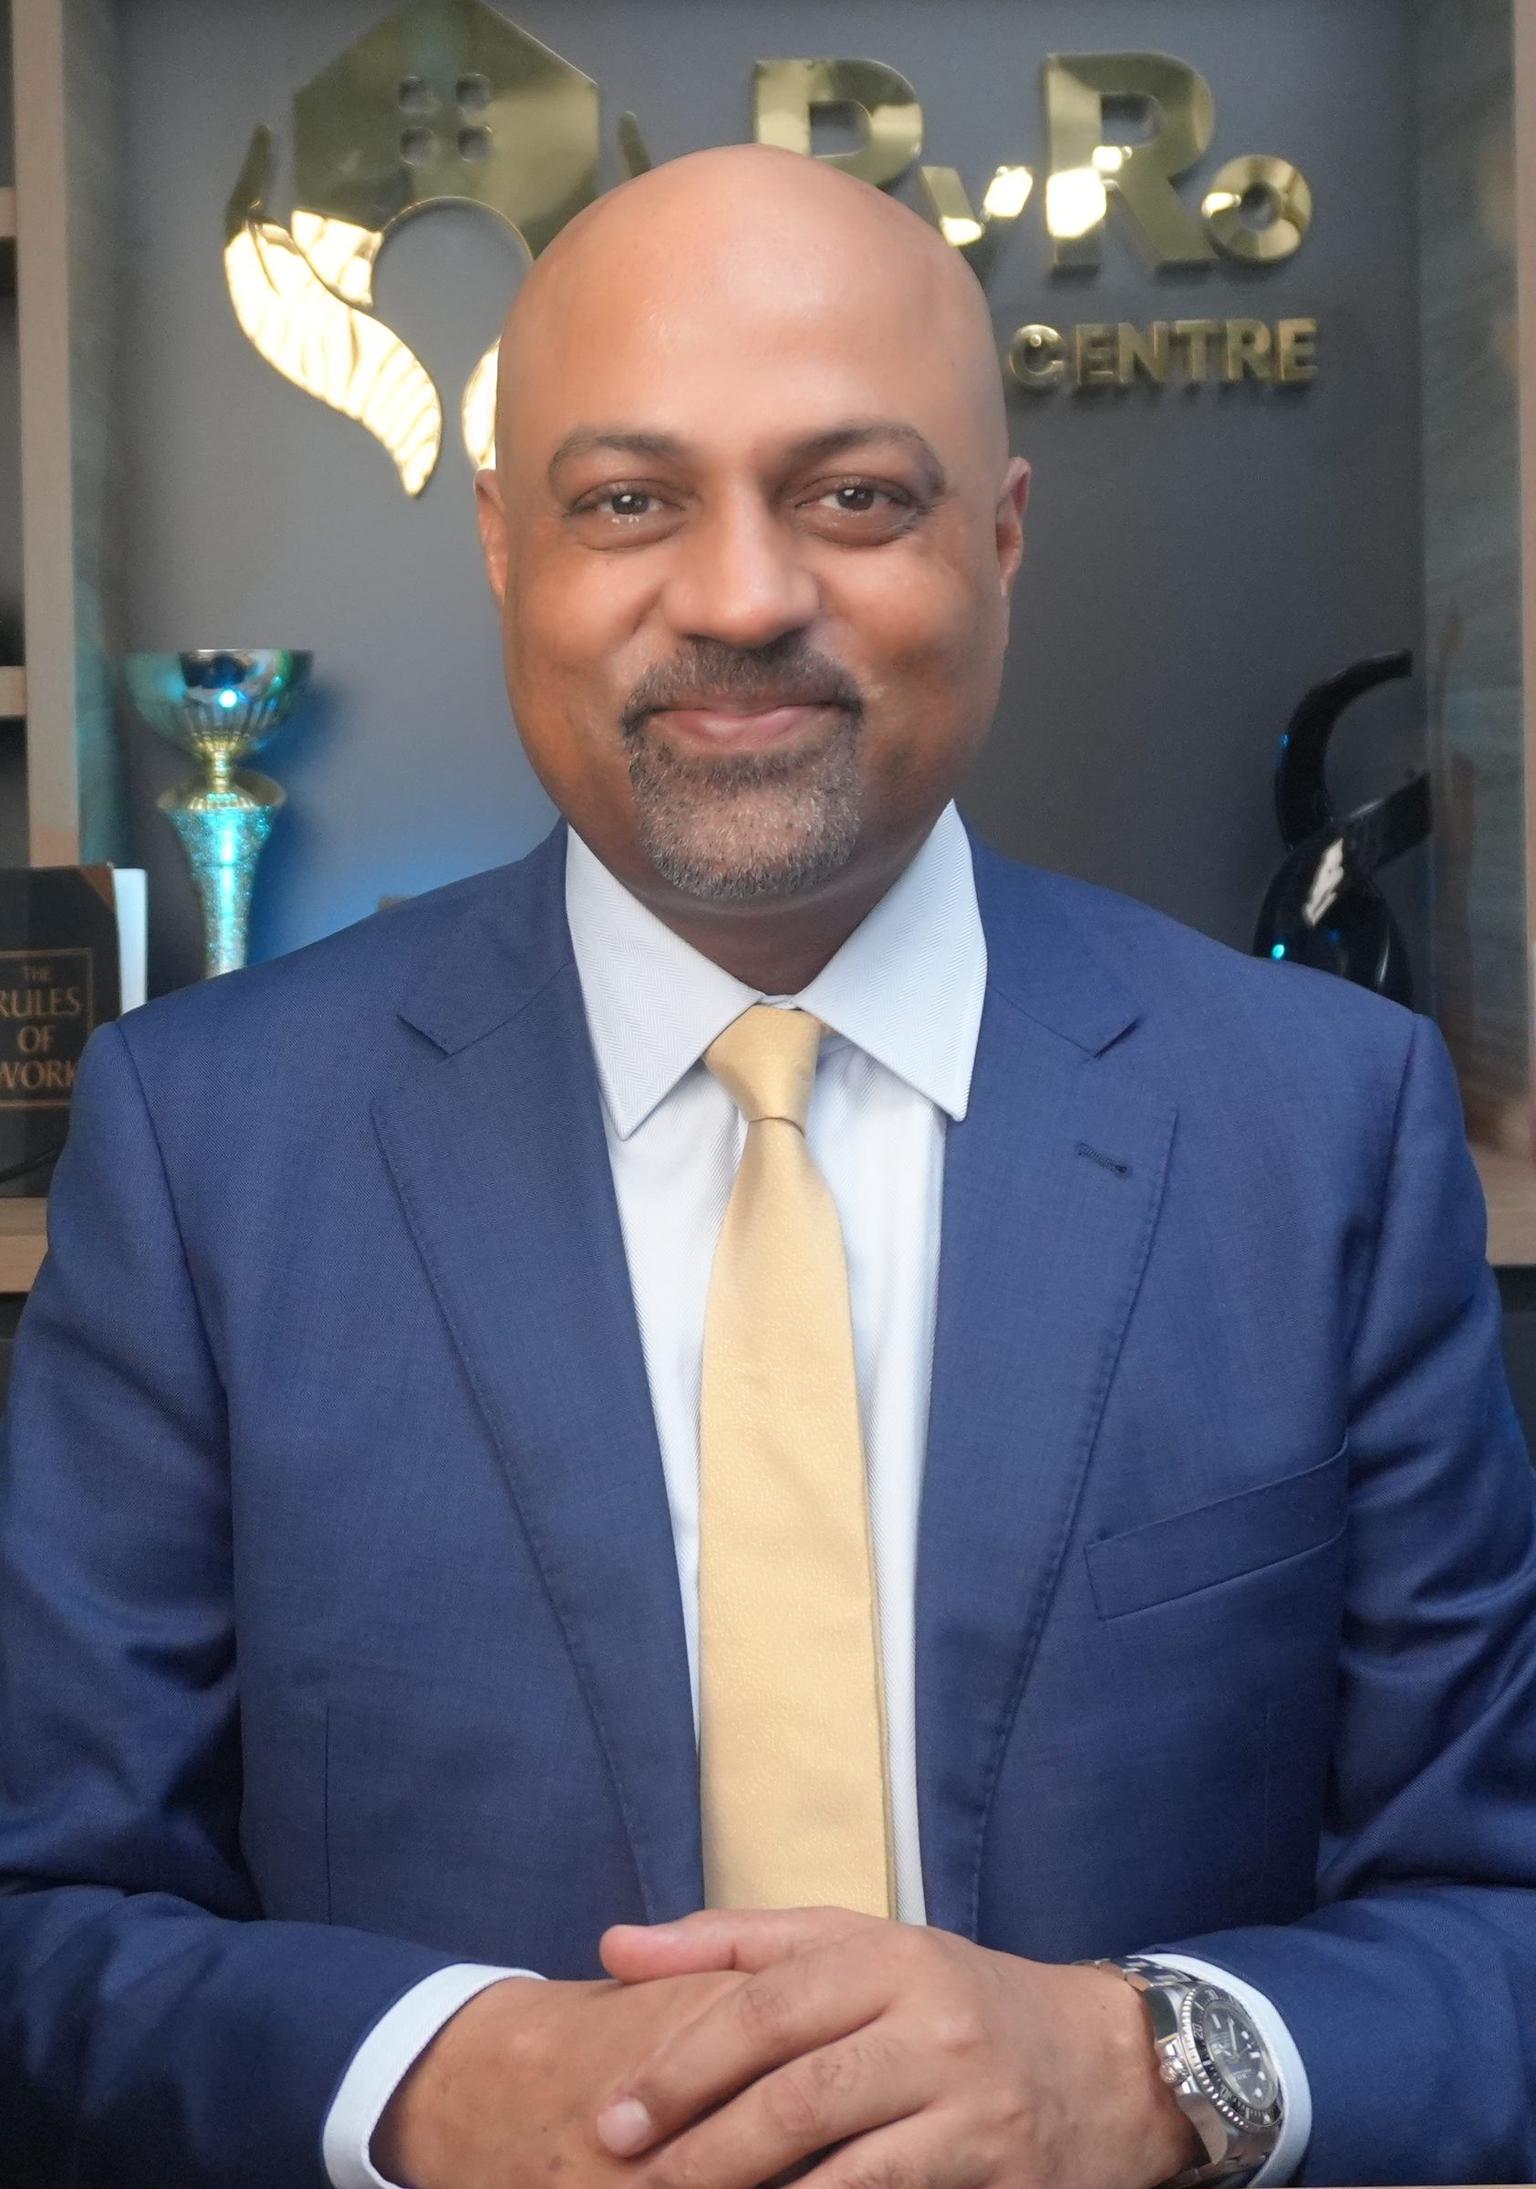
Sumit Joshi, principal broker at RyRo Loan Centre

Get your repayments checked

Real offers and real repayments, checked by a broker.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Free broker review of your rate and repayments
  • Refinancing, first home and investment loans compared
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Loan repayments

Estimate your monthly repayments

Last updated: November 2026

See what your monthly repayments would be for a given loan amount, interest rate and term. You can compare principal-and-interest vs interest-only, and see how much interest you'll pay over the life of the loan. Useful for budgeting, comparing loan sizes, or testing different rate scenarios.

Actual rates and repayments depend on the lender, your situation and the product you choose. For repayments based on your real numbers and current offers, use the form at the top of this page for a free strategy call.

Loan Repayment Calculator

Calculate your monthly loan repayments and see how much interest you'll pay over the life of your loan. Perfect for planning your budget and comparing different loan options.

% a year
How often you repay
Interest only or extra repayments(optional, 2)
Repayment type

Your estimate

Monthly repayment

$3,597

360 repayments over 30 years at 6% a year.

Total interest
$695,029
Total repaid
$1,295,029
Your balance year by year
Loan balance owing at the end of each year
YearBalance owing
1$592,632
2$584,809
3$576,504
4$567,687
5$558,326
6$548,388
7$537,836
8$526,634
9$514,741
10$502,114
11$488,709
12$474,477
13$459,367
14$443,325
15$426,293
16$408,211
17$389,014
18$368,633
19$346,994
20$324,022
21$299,632
22$273,738
23$246,246
24$217,060
25$186,073
26$153,174
27$118,247
28$81,165
29$41,797
30$0

Balance at the end of each year, before any change in rate.

Assumptions

Assumes the rate stays the same for the whole loan, repayments at the end of each period, and no fees. Extra repayments assume your lender keeps your repayment the same so the loan finishes early.

Figures last checked .

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

Got your repayment?

See what a lender would actually charge you

The calculator uses the rate you type in. Sumit compares real offers across our lender panel, whether you are refinancing to a better deal or buying your first home, and shows you the repayment that goes with each. Free, no obligation. We generally respond within an hour.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
Refinance to a better deal

No obligation and no credit check.

From 360+ Google reviews
5.0
Repayment and rate review
Free
Clients helped
2,500+
Broker fees on home loans
$0

Quick answer

How are loan repayments calculated?

Your repayment is set by three things: the loan amount, the interest rate and the term. On a principal and interest loan the formula works out one fixed payment that clears the debt by the last payment. At an assumed 6% rate, $600,000 over 30 years costs $3,597 a month. Interest-only on the same loan is $3,000 a month, because nothing comes off the balance.

Monthly repayment on $600,000 over 30 years at an assumed 6%
$3,597
Source: Standard repayment formula; illustration, not a current rate
Total interest on that loan if you only pay the minimum for 30 years
$695,029
Source: Standard repayment formula; illustration
Monthly interest-only repayment on the same loan, before any principal is repaid
$3,000
Source: Balance × rate ÷ 12; illustration
Buffer above your rate that lenders test your budget at
3%
Source: APRA mortgage serviceability buffer, kept at 3 percentage points (May 2026)

Using the tool

How this loan repayment calculator works

This loan repayment calculator estimates your regular repayments based on the loan amount, interest rate, repayment frequency and loan term you enter. It's useful whether you're comparing different home loan offers, testing rate rises, or planning your budget before you buy or refinance in Sydney, the Hills District or anywhere in NSW.

The calculator assumes a standard principal-and-interest home loan unless you choose interest-only. In real life, lenders may have minimum repayments, rate discounts, package fees and different repayment options. A mortgage broker can help you compare banks and non-bank lenders side by side, not just on interest rate, but on total cost over time.

  1. Step 1

    Quickly estimate your monthly, fortnightly or weekly repayments

    Enter the loan amount, the rate and the term, then pick how often you pay.

  2. Step 2

    See how interest rate changes affect your repayments and total interest

    Run the same loan at a higher rate to see what a rise would cost you each month.

  3. Step 3

    Compare different loan terms, e.g. 25 years vs 30 years

    A shorter term lifts the repayment but cuts the total interest you pay.

  4. Step 4

    Test principal-and-interest vs interest-only repayment options

    Switch the repayment type to see the gap between the two structures.

Sumit · 0:35
$50 a week extra could save you $100,000Sumit Joshi, RyRo Loan Centre · Sumit on total interest, at an assumed 5.5%

Loan structure

Principal & interest vs interest-only: what's the difference?

With a principal and interest (P&I) loan, each repayment covers both the interest charged and a portion of the loan balance. Over time, the balance reduces, less interest accrues, and more of each repayment chips away at the debt. P&I is the default structure for most owner-occupier home loans in Australia and results in the lowest total cost over the life of the loan.

With an interest-only (IO) loan, repayments only cover the interest, the loan balance stays the same throughout the IO period (typically 1 to 5 years). Monthly repayments are lower during this phase, but when the IO period ends, repayments jump to cover both principal and interest over a shorter remaining term. IO loans are commonly used by property investors for cash flow reasons, as the interest may be tax-deductible. Most lenders charge a slightly higher rate for IO loans.

Principal and interest compared with interest-only, on $600,000 over 30 years at an assumed 6%
Principal & interestInterest-only (5 years)
Each repayment coversInterest and some of the balanceInterest only
Balance during the periodFalls every monthStays the same
Repayment, years 1 to 5$3,597$3,000
Repayment from year 6$3,597$3,866
Total interest$695,029$739,743
Often used byOwner-occupiersInvestors managing cash flow

Illustration at an assumed rate, not a current market rate. Lenders often charge a higher rate for interest-only.

Use the calculator above to compare both structures with your loan amount and rate to see the repayment difference and total interest cost.
Buying an investment property? Our investment loan brokers set up interest-only and P&I splits around your cash flow and tax.

Worked examples

Repayments on a $600,000 loan, worked out

One loan, four ways. These illustrate the formula at an assumed 6% rate; they are not current rates or client figures.

Principal and interest

A $600,000 loan over 30 years, paid monthly, at an assumed 6% p.a.

Loan amount
$600,000
Total interest over 30 years
$695,029
Monthly repayment
$3,597

Every repayment pays the interest and some of the balance, so the debt falls from the first month.

Interest-only for 5 years

The same loan with a 5 year interest-only period, then principal and interest over the last 25 years.

Interest-only repayment
$3,000 a month
Total interest over 30 years
$739,743
Repayment from year 6
$3,866

Lower repayments now, a jump of $866 a month later, and $44,713 more interest overall.

$500 a month extra

The principal and interest loan with $4,097 paid every month instead of $3,597.

Paid off in
22 years 1 month
Time saved
7 years 11 months
Interest saved
$212,713

The extra money goes straight off the balance, so every later month charges interest on less.

Rates rise by 1%

The same loan if the rate moves from an assumed 6% to 7% with 30 years still to run.

Repayment at 6%
$3,597
Extra for a 0.5% rise
$195 a month
Extra for a 1% rise
$395 a month

This is why lenders test your budget at a higher rate before they approve you.

Want these numbers on your own loan, at a rate a lender will actually offer you? We run them on real offers for free.

Glass jar of coins with a seedling growing from the top
Small extra amounts, paid early, keep working for the rest of the loan. Photo: Towfiqu barbhuiya / Unsplash

Pay it off faster

How extra repayments save you money

Every dollar you pay above the minimum repayment directly reduces your loan balance. Because interest on a home loan is calculated on the outstanding balance, a lower balance means less interest accrues each month, and that saving compounds over the remaining loan term.

On a $600,000 loan at 6% over 30 years, the minimum monthly repayment is around $3,597. If you add just $500 per month on top of that, you could save over $120,000 in total interest and pay off the loan more than 7 years early. The earlier you start making extra repayments, the greater the effect, because the interest saving in year 2 also reduces the interest in years 3, 4, 5 and beyond.

  • Extra repayments reduce your loan balance and interest immediately
  • Even small amounts, $100 to $200/month, create material savings over 25 to 30 years
  • Lump-sum repayments (e.g. tax refunds, bonuses) have an outsized effect early in the loan
  • Check whether your loan allows extra repayments without fees, fixed-rate loans often have caps

Plan for a rise

What happens if interest rates rise?

On a variable rate loan, your repayments change each time your lender adjusts the rate, usually following RBA cash rate decisions. A 0.5% rate rise on a $600,000 loan adds approximately $180 to $200 per month to minimum repayments. A full 1% increase adds around $360 to $400 per month.

This is why APRA requires lenders to stress-test your repayments at your contract rate plus a 3% serviceability buffer before approving a loan. The buffer is designed to ensure borrowers can absorb rate increases without defaulting. If you were approved at 6%, you were tested at 9%.

If you're concerned about rate volatility, a strategy call with a broker can help you weigh fixed vs variable options and find a loan structure that fits your risk tolerance and financial goals. Our guide to fixed vs variable home loans sets out the trade-offs.

A month, for a 0.5% rise on $600,000 over 30 years from an assumed 6%
+$195
Source: Standard repayment formula; illustration
A month, for a 1% rise on the same loan
+$395
Source: Standard repayment formula; illustration

Serviceability buffer: APRA, May 2026.

Check my rate and repayments

Free review. No obligation.

Lower your repayments

How to reduce your home loan repayments

If the repayments shown are higher than you're comfortable with, there may be ways to bring them down or make them more manageable:

Hands signing loan paperwork at a desk
A refinance is paperwork we handle for you, start to finish. Photo: Scott Graham / Unsplash
  • Refinancing to a lower interest rate or sharper product

    We compare your loan with our lender panel through our refinancing service.

  • Extending your loan term to spread repayments over a longer period

    Lower repayments now, more interest over the life of the loan.

  • Using an offset account or making extra repayments when cash flow allows

    Try the offset calculator to see the saving.

  • Consolidating higher-interest debts into your home loan (with advice)

    One repayment, but check the total cost over the longer term.

The right strategy depends on your goals, risk tolerance and timeframe. We can walk you through different repayment scenarios, including what happens if rates move, and help you choose a structure that suits your situation.

A lower repayment is not free

Before you switch lenders to chase the number above, check what the move costs in discharge fees, new lender charges and government registration. Our guide to the cost of refinancing a home loan in 2026 lists each one.

What to do next

Pair this with our other tools or dive into our Home Loans overview and Refinancing guide to see how different products and structures can change your repayments.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824

Live in the Hills? Our Norwest office reviews loans for homeowners from Castle Hill to Kellyville every week, so you can sit down with a mortgage broker in the Hills District and see your repayments on real offers.

Real loans, real figures

How we changed repayments for refinancers

Three recent loans from our files, with the figures as they happened.

  • Refinance
  • Owner occupied
  • Fixed rate

Homeowners lock in two years of repayment certainty

Property value
$2.35M
Loan amount
$735K
2-year fixed rate
4.99%
  1. 1. The situation

    The clients owned their home, valued at about $2.35M, with a loan of around $735K.

  2. 2. What we did

    Reviewed fixed, variable and split options across our lender panel.

    +2 more in the full story

  3. 3. The result

    A known repayment for the next two years, which made the household budget easy to plan.

    +2 more in the full story

Read the full story

The situation

The clients owned their home, valued at about $2.35M, with a loan of around $735K. With rates rising through 2026 they wanted to stop guessing what their repayments would be from one month to the next.

What we did

  • Reviewed fixed, variable and split options across our lender panel.
  • Kept the loan at a similar amount (about $735K) so they were not borrowing more than they needed.
  • Moved the full loan to a 2-year fixed rate of 4.99%.

The result

  • A known repayment for the next two years, which made the household budget easy to plan.
  • Protection from any further rate rises during the fixed period.
  • A loan-to-value ratio of roughly 31%, which keeps their options open when the fixed term ends.

Rate shown is the rate this client received in 2026. Rates change often and depend on your circumstances, so yours may differ.

Car with keys and coins, representing car finance
Car loan repayments work the same way, over a shorter term.

Cars, utes and work vehicles

Car and vehicle loan repayments

You can run a car loan through the calculator above: enter the amount, the rate you have been quoted and the term. Three things change the answer.

  • Car loans run over shorter terms than home loans, so enter the term in years exactly as quoted.

  • A balloon (residual) payment lowers each repayment but leaves a lump sum to pay at the end. Ask for a quote that shows it.

  • New, used, electric or a ute for work: the lender, the rate and the term all change the repayment.

Car finance is arranged by RyRo Asset Finance, where Rohan Joshi compares a panel of car lenders for you. See car loans with RyRo Asset Finance.

RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.

Rated by refinancers

What refinancers say about Sumit

Lower repayments, less paperwork and a better deal. Word for word from Google.

Google

5.0

From 360+ Google reviews

Sumit · 1:18
Cheaper rate or the right strategy?Sumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • Sumit Financial

    5 years ago on Google

    Google

    We went through refinance with Sumit and were quite nervous about the whole process. Sumit made the whole changeover from our current bank very easy and smooth for us by providing minimum paper work We are in a far better financial position and after borrowing for the new pool our loan repayments dropped by $190 a week !! So I can not thank Sumit enough for the excellent solution he has provided us and has put us in a strong financial position. Thanks Sumit , kids are loving the new pool !!

    Sumit Financial

    Google5 years ago on Google

    We went through refinance with Sumit and were quite nervous about the whole process. Sumit made the whole changeover from our current bank very easy and smooth for us by providing minimum paper work We are in a far better financial position and after borrowing for the new pool our loan repayments dropped by $190 a week !! So I can not thank Sumit enough for the excellent solution he has provided us and has put us in a strong financial position. Thanks Sumit , kids are loving the new pool !!

  • Gurbaksh Dhillon

    2 years ago on Google

    Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

    Gurbaksh Dhillon

    Google2 years ago on Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

  • Sanjay Wadhwani

    2 years ago on Google

    Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

    Sanjay Wadhwani

    Google2 years ago on Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

  • Krish Gopal

    5 years ago on Google

    Google

    We have consulted with RyRo Loan Centre for 2 refinancing packages and on both occasions Sumit has ensured that our needs were met far beyond expectations. Sumit has exceptional knowledge in the field and makes the process very simple and efficient.

FAQ

Loan repayment calculator FAQs

Monthly figures, interest-only, extra repayments, rate rises and refinancing, answered in plain English.

9 answers in 3 topics

Your repayments

  • On a $500,000 principal-and-interest loan at 6% over 30 years, monthly repayments are approximately $2,998. At 6.5% they rise to around $3,160. On a 25-year term at 6%, the monthly repayment increases to about $3,222 but you pay significantly less interest overall. Use the calculator above to run your own scenario with the exact loan amount, rate and term.
  • Repayments on a principal and interest loan use a standard amortisation formula: the loan amount, the interest rate for each period and the number of repayments set one fixed payment that clears the loan by the end of the term. Early on most of each payment is interest; later most of it is principal. Interest-only repayments are simpler: the balance times the rate, divided by the number of payments in a year. The calculator above does the maths for you.
  • The saving comes from paying half your monthly repayment every fortnight. There are 26 fortnights in a year, so you make the equivalent of 13 monthly repayments instead of 12. On a $600,000 loan at an example rate of 6% over 30 years, the monthly repayment is about $3,597. Paying half of that ($1,799) every fortnight saves about $148,900 in interest and pays the loan off about 5 years 6 months sooner. A fortnightly repayment that a lender works out on a fortnightly schedule (about $1,660 here) saves very little, so check which one your lender offers.
  • The calculator gives you a strong guide based on standard home loan formulas. It doesn't factor in all fees, introductory discounts, package costs or future rate changes, so your actual repayments may differ once a specific lender and product are chosen.
  • Yes, you can use the loan repayment calculator for most types of principal-and-interest loans by entering the relevant amount, rate and term. Just remember that personal loans and car loans typically have higher interest rates and shorter terms than home loans.

Loan structure and extra repayments

  • Principal and interest (P&I) repayments reduce your loan balance from day one, meaning you build equity and pay less total interest over the life of the loan. Interest-only (IO) repayments are lower in the short term but the loan balance doesn't reduce, and IO periods are typically capped at 1 to 5 years before reverting to P&I (with higher repayments). IO is often used by investors for cash flow management. Most owner-occupiers are better served by P&I from the start.
  • Extra repayments reduce your loan balance directly, which means less interest accrues each month. On a $600,000 loan at 6%, an extra $500/month could save over $120,000 in interest and cut more than 7 years off a 30-year loan. The effect compounds over time because each reduction in balance reduces the interest charged in all future months. Even small, consistent extra repayments make a meaningful difference over a 25 to 30 year term.

Rates and refinancing

  • On a variable rate home loan, your repayments increase automatically when your lender passes on a rate rise. A 0.5% rate increase on a $600,000 loan adds approximately $180 to $200 per month to repayments. Lenders are required to test your ability to service the loan at your rate plus a 3% buffer, so if you were approved at 6%, your repayments were stress-tested at 9%. Use the calculator to model rate scenarios and ensure your budget is comfortable across a range.
  • Often, yes. Refinancing to a sharper rate, a loan without a package fee or a longer remaining term can lower your repayments, but switching has costs: discharge fees, government registration fees and sometimes a valuation or break cost on a fixed loan. A broker compares those costs with the saving before you move. If you want your current loan checked against our lender panel, leave your details in the form and we will run the numbers for you.

Free strategy call

The people behind your strategy call

Sumit and the team compare real offers across our lender panel and show you the repayment that goes with each one. 5.0 stars from 360+ Google reviews and 2,500+ clients helped. We generally respond within an hour.
Sumit Joshi, principal broker at RyRo Loan Centre

Get your repayments checked

Real offers and real repayments, checked by a broker.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Your repayments worked out on real lender offers
  • Refinance, first home and investment loans covered
  • Free for home loans: the lender pays us
Sumit · 2:56
Approved in days after her broker went quietSumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Repayment and rate review
Free
“Sumit has been amazing through the whole process of refinancing our home loan. So professional and friendly. I highly recommend him to anyone who is looking for a mortgage broker!”
Annaliza Benitez · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026. Calculator results are estimates. Your rate and repayments depend on the lender, the product and your situation.

Get my free loan review