RyRo Loan Centre

Home loan broker, Sydney

Find the Right Home Loan in Sydney, Faster Than You Think

RyRo Loan Centre compares home loans from 50+ lenders and manages your application from strategy to settlement. Based in Norwest, we look for the right loan for your situation, not just the lowest rate on a comparison site.

Sumit Joshi, principal broker at RyRo Loan Centre

Find your home loan in 60 seconds

Free call with Sumit. No credit check, no obligation.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Buying, upsizing, building, refinancing or investing
  • One broker from first call to settlement day
  • Based in Norwest, Sydney. $0 broker fees on home loans
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Start here

Where Should You Start?

Most people landing here are doing one of three things: buying, cutting the cost of a loan they already have, or moving up to a bigger place. Pick the path that matches you and go straight to the detail.

Not sure which one you are? That is a two-minute conversation. Book a free strategy call and we will tell you which path your situation actually fits.

  • Hands signing loan paperwork at a deskAlready own

    You want to cut the cost of the loan you already have

    Rate not reviewed in two years, or a fixed term about to end? We compare your loan against the market and do the break-cost maths.

    Is this you?

    This path is for you if your loan has not been reviewed in two or more years, your fixed term is about to end, or you have simply never checked your rate against the market. Refinancing is the single highest-return hour most existing homeowners can spend.

  • Modern white kitchen with a marble benchtopUpsizing

    You have outgrown the house and want the next one

    Use the equity in the home you own as the deposit on the next one, without selling first.

    Is this you?

    This path is for you if you own a home with equity in it and want to buy a bigger one without selling first. You release equity against the property you own, use it as the deposit on the next place, then decide whether to keep the first home or sell it.

  • House keys with a house-shaped key ring held up inside a front doorFirst home

    You are buying your first home

    Work out your deposit, the schemes you qualify for and what you can actually borrow, before you start bidding.

    Is this you?

    This path is for you if you are working out your deposit, which government schemes you qualify for, and what you can actually borrow. The 5% Deposit Scheme changed the maths for Sydney buyers from 1 October 2025.

  • Timber frame of a new house going up, with scaffolding against a blue skyBuilding

    You are building or doing a knockdown rebuild

    Progress payments, builder approval and a fixed-price contract make a construction loan a different loan entirely.

    Is this you?

    This path is for you if you are doing a knockdown rebuild, a house and land package in the northwest growth corridor, or a build on a block you already own. Progress payments and builder policy make this a different loan entirely.

  • Aerial view of a new housing estate on the edge of a city, similar to the Hills District growth areasBuying land

    You are buying a vacant block to build on later

    Lenders assess vacant land differently from a house, so the deposit, the term and the lender choice all change.

    Is this you?

    This path is for you if you have found a block, or want one in a new estate, and plan to build later. We line up a lender that suits the land now and the construction loan when you are ready to build.

  • Modern two-storey house with a lit entry and garage at duskNew estate

    You are buying a house and land package

    The land settles first, then the build draws down in stages. The lender has to suit your builder, block and timeline.

    Is this you?

    This path is for you if you are buying land and a build contract together in a new estate across northwest or southwest Sydney. We check the lender suits your builder and your timeline before you sign, so land settlement and the first progress payment line up.

  • Stack of cardboard moving boxes by a sunny windowBuy before you sell

    You are buying the next home before the old one sells

    A bridging loan covers the gap, so you can buy the right place now and sell on your own timeline.

    Is this you?

    This path is for you if you have found the next home but the one you own has not sold yet. A bridging loan funds the purchase now, then the sale of your current home pays it down. We work out the peak debt, the bridging term and what happens if the sale takes longer.

  • Bright living room with a grey sofa, indoor plants and a large windowRenovating

    You want to renovate the home you already own

    Equity, a top-up or a construction loan for bigger work: the right one depends on the size of the job.

    Is this you?

    This path is for you if you are planning a kitchen, an extension or a full renovation. Smaller jobs often suit a top-up or equity release, while structural work may need a construction loan with progress payments. We match the loan to the scope and the quotes you have.

  • Calculator app on a phone held over a folder of paperworkCheck-up

    You want to know if your loan still stacks up

    A free home loan health check compares your rate, fees and features with what you could get today.

    Is this you?

    This path is for you if you are not sure whether to refinance or stay put. We look at your rate, fees, offset and structure against the market, then tell you plainly whether a change is worth it. Sometimes the answer is a better deal from the lender you already have.

Investing or self-employed? See property investing services and our specialist lenders for complex income, trusts and SMSF purchases. Already own a home? Our guide for existing homeowners puts refinancing, equity, renovating and upsizing side by side.

Overview

Overview of Home Loans

RyRo Loan Centre is a Sydney mortgage broker that compares home loans across its lender panel and manages your application from pre-approval to settlement, at no cost to you. RyRo works with first home buyers, upgraders, refinancers and investors across Sydney from its office in Norwest, in the Hills District. RyRo Loan Centre is rated 5.0 from 360+ Google reviews.

Whether you're buying your first home, refinancing an existing mortgage, upgrading to your next property or growing an investment portfolio, RyRo Loan Centre compares home loan options from 50+ lenders and manages your application from strategy to settlement. Based in Norwest in Sydney's Hills District, we help borrowers across Sydney, NSW and Australia find the right home loan for their situation, not just the lowest rate on a comparison website.

Quick answer

What does a home loan broker do in Sydney?

A home loan broker compares loans from many lenders for you, works out which ones will actually approve your situation, prepares the application and manages it to settlement. At RyRo Loan Centre that is free for home loans, because the lender pays us, and you deal with Sumit from our Norwest office.

What is a home loan?

Finance to buy residential property, with the property as security, repaid with interest over 25 to 30 years.
More detail

A home loan (mortgage) is finance to buy residential property. You borrow from a lender, use the property as security, and repay with interest over 25 to 30 years. The right structure depends on your goal (owner-occupier, investment, building, refinancing), income, deposit and timeline. We compare 50+ lenders to find the best rate and structure for you.

How home loans work

Lenders assess your income, expenses, debts and the property before they approve the loan.
More detail

Lenders assess your income, expenses, debts and the property before approving your loan. The property is security: if you stop repaying, they can sell it to recover the debt. Getting the right structure from day one matters for approval and long-term cost. We match you to lenders that fit your situation.

Fixed vs variable rate home loans

Variable moves with the market and gives flexibility. Fixed locks your repayment for 1 to 5 years.
More detail

Variable rates move with the RBA cash rate; repayments can go up or down and you get flexibility (extra repayments, offset, redraw). Fixed rates lock your rate for 1 to 5 years for repayment certainty but with less flexibility. Many borrowers split: part fixed, part variable. We help you choose what fits your situation.

Principal and interest vs interest-only loans

Principal and interest builds equity. Interest-only keeps repayments lower for a set period, often for investors.
More detail

P&I repayments reduce your balance and build equity; they're the standard for owner-occupiers and usually have lower rates. Interest-only repayments cover just interest for a set period (often used by investors); the balance doesn't fall and rates are higher. We explain which suits you before you decide.

Ali Ahsan

3 years ago on Google

Google

Sumit was very helpful and has effectively guided through the process, fairly analysed options for us and finally made the interaction with selected lender smooth overall given it was our first ever home loan. Recommend if you need advice aligned to your circumstances.

Ali Ahsan

Google3 years ago on Google

Sumit was very helpful and has effectively guided through the process, fairly analysed options for us and finally made the interaction with selected lender smooth overall given it was our first ever home loan. Recommend if you need advice aligned to your circumstances.

Sumit · 0:49
Mortgages do not need to be complicatedSumit Joshi, RyRo Loan Centre · Sumit on how we work

Home loan types

Every Type of Home Loan, Covered

We help borrowers across Sydney and Australia secure finance for every property purchase situation. Whether you're a first home buyer, an upgrader, an investor, someone looking to refinance, or a borrower with a complex income situation, we work with lenders across our panel of 50+ who support your specific scenario.

7 home loan categories

  1. 01

    First Home Buyer Loans

    Your deposit, the schemes you qualify for, the lender and the structure, sorted before you bid.
    More on first home buyer loans

    Buying your first home in Sydney is one of the most significant financial decisions of your life, and it comes with real complexity: choosing the right deposit level, understanding which government grants and schemes apply to you, selecting the right lender and loan structure, and navigating one of the most competitive property markets in the world.

    Our first home buyer loans in Sydney cover the full picture, from how much you need to save and what government support you qualify for, through to pre-approval, property purchase and settlement. From 1 October 2025, the Australian Government's 5% Deposit Scheme (formerly the First Home Guarantee) has no income caps, no place limits, and a property price cap of $1,500,000 for Sydney and major NSW regional centres, meaning eligible first home buyers can purchase with as little as a 5% deposit without paying Lenders Mortgage Insurance. The NSW First Home Owner Grant of $10,000 may also apply if you're purchasing or building a new home (with a price cap of $600,000 for a new dwelling, or $750,000 for a house and land package combined).

    We work with first home buyers every day. We know the questions you haven't thought to ask yet, and we answer them before they become surprises.
  2. 02

    Home Loans for Owner-Occupiers (Upgraders and Established Buyers)

    Structured properly, the same purchase can cost tens of thousands less over a 30-year loan.
    More on upgrading

    Purchasing an established home or upgrading from your current property requires careful structuring to avoid leaving money on the table. The difference between a well-structured home loan and a generic bank product can mean tens of thousands of dollars over the life of a 30-year loan, in interest charges alone.

    We compare home loan options from 50+ lenders, including major banks, non-bank lenders and specialist lenders that aren't accessible directly to borrowers. We negotiate on your behalf, prepare your application for the strongest possible presentation, and manage the process from pre-approval through to settlement. For Sydney buyers in competitive suburbs, fast pre-approval can make a real difference when it comes to bidding at auction with confidence.

  3. 03

    Investment Home Loans

    Assessed differently to owner-occupier loans, so the structure and the lender matter more.
    More on investment loans

    Investment property loans in Sydney and across Australia are assessed differently to owner-occupier loans. Lenders apply higher interest rates for investment purposes, have stricter serviceability assessments for existing investors, and look carefully at rental income, existing debt levels and your overall portfolio structure.

    Whether you're purchasing your first investment property or adding to an existing portfolio, the right loan structure matters significantly: the choice between fixed and variable rate, interest-only and principal and interest, offset or redraw, and which lender to use can affect your cash flow, tax position and future borrowing capacity. We work with property investors at every stage, from first-time investors to experienced buyers managing multi-property portfolios.

    Investment loans

  4. 04

    Refinancing Home Loans

    Took your loan out more than two years ago? The rate may no longer match the market.
    More on refinancing

    If you took out your home loan more than two years ago, there's a reasonable chance you're paying a rate that no longer reflects what's available in the market, and that gap could be costing you significantly. On a $700,000 loan, a difference of just 0.5% in your interest rate represents roughly $3,500 per year in additional interest. Refinancing your home loan in Sydney through a broker who compares across 50+ lenders means you're accessing the full market, not just switching between a handful of major banks.

    We review your current loan, compare it against options across our panel, calculate whether the savings outweigh any break costs or switching fees, and manage the refinancing process from application to settlement. Common reasons our clients refinance include: reducing their interest rate; accessing equity for renovation or investment; switching from variable to fixed (or vice versa); and moving off a rate and structure that no longer suits their situation.

    There's no cost to find out whether refinancing makes sense for you. Get a free strategy call and we'll assess your current loan against the market.

    Refinancing

  5. 05

    Construction Loans

    Staged progress payments, so you pay interest only on what has been drawn during the build.
    More on construction loans

    Building a new home, whether from scratch on a new block or as a knock-down-rebuild on an established lot, requires a different loan structure to buying an existing property. Construction loans in Sydney and NSW are structured with staged progress payments, released at each build milestone: slab, frame, lock-up, fix-up and practical completion. You only pay interest on what has been drawn down during the construction period, not the full loan amount, which reduces your interest costs while the build is underway.

    Lenders assess construction loans on both your financial position and the strength of your build contract and builder. Not every lender is well-versed in construction finance. We work with lenders whose policies genuinely support your construction timeline and builder, and we plan the transition from a land loan to a construction loan, or arrange the construction loan from day one, so the process is smooth and cost-effective.

    Construction loans

  6. 06

    Home and Land Package Loans

    Land and build in one structure, popular in the northwest and southwest growth corridors.
    More on home and land packages

    Buying land and building your home at the same time? A home and land package loan combines land purchase and construction finance into a single, streamlined structure. Popular in new estates across northwest and southwest Sydney, including Box Hill, Marsden Park, Schofields, Riverstone and similar growth corridors, these loans simplify the finance process and can align settlement with construction commencement.

    Getting the structure right for a home and land package matters: the land component settles first, then the construction loan draws down progressively as building milestones are reached. We ensure the lender's policies support your builder, your block and your timeline, so there are no surprises between land settlement and construction commencement.

    Home and land packages

  7. 07

    Low Doc Home Loans

    For self-employed borrowers whose payslips do not tell the whole story.
    More on low doc loans

    Self-employed borrowers, business owners and people with complex income structures often find that standard home loan applications don't reflect their actual financial position. Low doc loans allow eligible borrowers to support their application with alternative income documentation, such as BAS statements, accountant's declarations or business bank statements, rather than standard payslips and tax returns.

    Low doc home loans typically require a larger deposit (usually a minimum of 20%) and carry higher interest rates than standard loans, but they open the market to borrowers who would otherwise be declined by mainstream lenders. We have access to specialist lenders who assess low doc applications fairly and understand self-employed and business income. We assess your situation honestly and match you to the most appropriate lender from the start.

    Low doc loans

We compare home loan options from 50+ lenders across every borrower category. Tell us what you're trying to achieve and we'll match you to the right product and lender.

Not sure which home loan type suits your situation? Get expert advice free, no credit check, no obligation. We'll call you to discuss your situation and the best options from our panel.

Sumit · 1:14
Upgrading? Keep your first home or sell itSumit Joshi, RyRo Loan Centre · for upgraders

Already own a home?

Should You Refinance in 2026?

Refinance in 2026 if your current rate sits more than about 0.5% above what you could get today, or if your loan has not been reviewed in two or more years. Skip it if you are locked into a fixed rate where break costs swallow the saving, or if your loan to value ratio is above 80% and switching would trigger Lenders Mortgage Insurance all over again.

Worth a review if

  • Your rate is about 0.5% or more above new-borrower rates
  • Your loan has not been reviewed in two or more years
  • Your fixed term is about to end
  • Your property value has pushed your LVR under 80%

Probably stay put if

  • Break costs on a fixed rate swallow the saving
  • Your LVR is above 80% and switching would mean LMI again
  • The numbers do not stack up after switching costs

Waiting for a cut is not a strategy. The saving available right now comes from the gap between what existing borrowers pay and what new borrowers are offered, and for many Sydney households that gap is real.

On a $750,000 Hills District loan, half a percent is roughly $3,750 a year. Over the five years most people stay put, that is the difference between a kitchen renovation and nothing. Model your own numbers with our loan repayment calculator, then check what an offset account would add on top with the home loan offset calculator.

Here is what to do first: find your current rate on your last statement, then compare it against the market. That is exactly what our refinancing service does, free, across 50+ lenders, including the break-cost maths if you are on a fixed rate. If the numbers do not stack up we will tell you to stay put.

Review my current loan

Free review. Bring your last statement.

Clients who refinanced with us

  • Gurbaksh Dhillon

    2 years ago on Google

    Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

    Gurbaksh Dhillon

    Google2 years ago on Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

  • Sanjay Wadhwani

    2 years ago on Google

    Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

    Sanjay Wadhwani

    Google2 years ago on Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

Sumit · 0:35
$50 a week extra could save you $100,000Sumit Joshi, RyRo Loan Centre · at an assumed 5.5%

Case studies

Three home loans we restructured in 2026

Real clients, details kept private. The figures are from the loans we arranged; your rate and outcome depend on your circumstances.

Talk through my loan

Free, no obligation.

  • Refinance
  • Owner occupied
  • Fixed rate

Homeowners lock in two years of repayment certainty

Property value
$2.35M
Loan amount
$735K
2-year fixed rate
4.99%
  1. 1. The situation

    The clients owned their home, valued at about $2.35M, with a loan of around $735K.

  2. 2. What we did

    Reviewed fixed, variable and split options across our lender panel.

    +2 more in the full story

  3. 3. The result

    A known repayment for the next two years, which made the household budget easy to plan.

    +2 more in the full story

Read the full story

The situation

The clients owned their home, valued at about $2.35M, with a loan of around $735K. With rates rising through 2026 they wanted to stop guessing what their repayments would be from one month to the next.

What we did

  • Reviewed fixed, variable and split options across our lender panel.
  • Kept the loan at a similar amount (about $735K) so they were not borrowing more than they needed.
  • Moved the full loan to a 2-year fixed rate of 4.99%.

The result

  • A known repayment for the next two years, which made the household budget easy to plan.
  • Protection from any further rate rises during the fixed period.
  • A loan-to-value ratio of roughly 31%, which keeps their options open when the fixed term ends.

Rate shown is the rate this client received in 2026. Rates change often and depend on your circumstances, so yours may differ.

Understanding

What is a Home Loan? (In More Detail)

A home loan is the single largest financial commitment most Australians will ever make. Getting it right, the right structure, the right lender, the right rate, can save you tens of thousands of dollars and significantly reduce financial stress over the life of the loan.

3 key things to know

  1. 01

    What you can use a home loan for

    Buying an established home, a new home or an investment, or building on land you own or are buying.
    What a home loan covers

    Home loans can be used to purchase an established residential property, a new home, an investment property, or to fund construction of a new dwelling on land you already own or are purchasing. The property is used as security, and the loan is structured as a set amount borrowed and repaid over a set term with interest.

    The terms, rates and lender appetite vary by property type, your purpose (owner-occupier or investor), your deposit and your financial profile.

  2. 02

    Variable vs fixed rate, and when each makes sense

    Variable gives you flexibility, fixed gives you certainty. Many borrowers split the loan between the two.
    Fixed, variable or split

    Variable rate loans offer flexibility: offset accounts, unlimited extra repayments, redraw facilities, and the potential to benefit when rates fall. Fixed rate loans offer certainty: the same repayment amount for one to five years regardless of rate movements.

    The right choice depends on your cash flow needs, your risk tolerance, and your view of where rates are headed. Many borrowers split their loan, fixing a portion for certainty and leaving the rest variable for flexibility. There's no universally right answer; we work through this with you based on your specific position.

    Fixed rate vs variable rate: compare your options in detail

  3. 03

    Borrowing capacity and how lenders assess you

    Lenders test your repayments at a rate at least 3 percentage points above your actual rate.
    How the buffer works

    Under APRA guidelines, lenders must assess your ability to service a home loan at an interest rate at least 3 percentage points above the actual loan rate. This is the mortgage serviceability buffer, which has been maintained at 3% since October 2021 and confirmed to remain unchanged in APRA's July 2025 review.

    This buffer means that even at current rates, you're assessed at a significantly higher rate, which affects how much you can borrow. It also means that different lenders, with different expense benchmarks and income assessment methods, will arrive at different borrowing capacity figures for the same borrower.

    We know which lenders calculate serviceability most favourably for different income types and structures, and we apply that knowledge to maximise your options.

Use our Loan Repayment Calculator to estimate your repayments before you apply, or speak directly with our team for figures based on your actual numbers, obligation-free.

Hand holding a set of house keys above small model houses
The loan, the lender and the structure matter as much as the rate.Photo: Jakub Żerdzicki / Unsplash
Desk calculator beside a laptop and printed budget charts
Run your repayments before you talk to a lender.Photo: Jakub Żerdzicki / Unsplash

Get your home loan strategy call

Tell us about your situation and we'll match you to the right lender. Free, no obligation, no credit check.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
Get my free strategy call

Free, no obligation. We generally respond within an hour.

The process

How Does a Home Loan Work?

Understanding how a home loan works before you apply makes the process faster, clearer and less stressful.

7 key things to know

  1. 01

    Pre-Approval

    Know what a lender will lend before you make offers. In Sydney it lets you bid at auction with confidence.
    More on pre-approval

    Before you start making offers on property, it's strongly advisable to have a home loan pre-approval in place. Pre-approval (also called conditional approval or approval in principle) confirms that a lender is willing to lend you up to a certain amount, subject to the property you're purchasing meeting their criteria. In Sydney's competitive property market, having pre-approval before auction gives you the confidence to bid and signals to vendors and agents that you're a serious buyer. Pre-approval is typically valid for 90 days. We obtain pre-approvals quickly, most straightforward applications receive pre-approval within 1 to 2 business days.

  2. 02

    Deposit Requirements

    Usually 5% to 20%, depending on the lender, the loan type and the property.
    The deposit rules

    The deposit you need depends on the lender, the loan type and the property:

    • Most standard home loans require a minimum 5 to 20% deposit
    • Borrowing above 80% LVR (loan-to-value ratio) typically triggers Lenders Mortgage Insurance (LMI), an insurance premium you pay to protect the lender if you default
    • A 20% deposit avoids LMI and generally delivers access to better interest rates and broader lender choice
    • Eligible first home buyers can purchase with as little as a 5% deposit under the Australian Government's 5% Deposit Scheme (no income caps, no place limits from 1 October 2025), avoiding LMI entirely
    • The government guarantees up to 15% of the loan value so the lender treats you as having a 20% deposit
    • NSW property price cap under the scheme is $1,500,000 for Sydney and major regional centres (up from $900,000 prior to 1 October 2025)
    • Investors generally need a 10 to 20% deposit, with some lenders applying more conservative policies
  3. 03

    Interest Rates

    Half a percent on a $700,000 loan over 30 years can add up to more than $70,000 in interest.
    Why the rate matters

    The interest rate on your home loan determines a significant portion of the total cost of borrowing. On a $700,000 home loan over 30 years, a difference of just 0.5% in your interest rate can mean more than $70,000 in additional interest payments over the life of the loan. Rates offered to new borrowers are often lower than the average across all existing loans, which is the whole reason a loan review is worth doing. The rate a lender advertises is rarely the rate every borrower receives. We negotiate with lenders across our panel on your behalf to secure the most competitive rate available for your specific scenario.

  4. 04

    Lenders Mortgage Insurance (LMI)

    Payable above 80% LVR. It protects the lender, not you, and there are ways to avoid it.
    Ways to avoid LMI

    LMI is an insurance premium payable by the borrower when borrowing above 80% LVR. It protects the lender, not you, in the event of default. LMI can cost anywhere from a few thousand dollars to over $30,000 depending on your LVR and loan size, and it's typically added to the loan balance. It can be avoided by having a 20% deposit, accessing the 5% Deposit Scheme (First Home Guarantee), using an eligible guarantor, or certain professional packages offered by specific lenders. We work through these options with you clearly so you can decide which path makes the most financial sense. Estimate yours with our LMI calculator.

  5. 05

    Valuation

    The lender values the property. If it comes in under the price, your deposit has to cover the gap.
    When a valuation comes in short

    Before approving your home loan, the lender commissions an independent valuation of the property. The valuation must support the purchase price: if it comes in lower than the contracted price, the lender will only lend against the lower figure, which affects your LVR and potentially your deposit requirement. This is particularly relevant in competitive markets where buyers sometimes pay above comparable sales. We prepare your application to give the strongest possible presentation and alert you to any valuation risk before you commit.

  6. 06

    Settlement

    Usually 30 to 90 days after exchange. Kathryn coordinates your conveyancer and the lender.
    What happens at settlement

    Home loan settlement typically occurs 30 to 90 days after exchange of contracts, with the timeframe agreed between buyer and seller at exchange. Settlement is the point at which you take legal ownership of the property, the loan funds are drawn down, and the purchase price is paid to the vendor. Our settlement liaison Kathryn manages this process end-to-end, coordinating with your conveyancer and the lender to ensure settlement proceeds smoothly and on time.

  7. 07

    After Settlement: Ongoing Loan Management

    We review your loan as the market moves and tell you when a better option appears.
    How we look after the loan

    A good mortgage broker relationship doesn't end at settlement. We review our clients' loans regularly to ensure they remain competitive as the market changes. Interest rates move, lenders introduce new products, and your financial situation evolves. If a better option becomes available, through refinancing, restructuring or switching products within your existing lender, we'll let you know before it costs you money.

Kshitindra Rai

5 years ago on Google

Google

Great Service. I would definitely recommend them. Sumit was great and explained everything in detail. I did not run into surprises and the settlement went through on time. Also, this was my first time buying property so I had a lot of questions and Sumit was very patient in answering them and also giving me suggestions. Thanks for all the help.

Kshitindra Rai

Google5 years ago on Google

Great Service. I would definitely recommend them. Sumit was great and explained everything in detail. I did not run into surprises and the settlement went through on time. Also, this was my first time buying property so I had a lot of questions and Sumit was very patient in answering them and also giving me suggestions. Thanks for all the help.

Ready to start? Get a free strategy call and we'll walk you through the process for your situation, from pre-approval to settlement.

Sumit · 1:07
Buying a home in NSW, step by stepSumit Joshi, RyRo Loan Centre · offer to settlement

Deposit and costs

Home Loan Deposit Requirements: What Do You Actually Need?

The deposit required for a home loan in Australia depends on several factors: the property type, your loan purpose, your financial profile and which lender you're working with.

Typical minimum deposit by loan type
Loan typeTypical minimum depositWhat to watch
Owner-occupier home loan5% with most lendersLMI applies above 80% LVR
First home buyer, 5% Deposit Scheme5%No LMI, price caps apply
Investment home loan10% with most lenders20% to avoid LMI
Construction loanSimilar to a standard loanAssessed on land plus build
Low doc home loanUsually 20%Alternative income evidence

4 key deposit categories, in detail:

1. Standard owner-occupier home loans

Most lenders will finance up to 95% LVR (5% deposit) for owner-occupier home loans on standard residential property. Borrowing above 80% LVR triggers Lenders Mortgage Insurance (LMI). A 20% deposit avoids LMI and typically delivers access to lower interest rates and broader lender choice.

For Sydney buyers where property values are significantly above the national average, saving a 20% deposit is a substantial undertaking, which is why government schemes like the 5% Deposit Scheme are particularly impactful in this market.

2. Investment home loans

Investment loans are assessed more conservatively. Most lenders require a minimum 10% deposit for investment purchases, with 80% LVR (20% deposit) typically required to avoid LMI and access competitive investment rates.

Borrowers with multiple existing investment properties may face additional restrictions, and serviceability becomes more complex as the portfolio grows.

3. Construction loans

Construction loan deposit requirements are similar to standard home loans, but assessed against the combined land and construction costs (total project value). A licensed builder with a fixed-price building contract is required by most lenders.

Progress payments are released in stages as construction milestones are completed, so you only pay interest on drawn funds during the build.

4. Low doc home loans

Self-employed and complex income borrowers seeking low doc loans typically need a larger deposit, usually a minimum of 20%, because the lender is accepting alternative income verification.

Some specialist lenders will consider lower LVRs for strong applicants with documented trading history.

Not sure how much you'll need? Get a free strategy call and we'll work through deposit requirements, stamp duty costs and grant eligibility based on your situation.

Sumit · 0:47
Four tips for the best chance of approvalSumit Joshi, RyRo Loan Centre · deposit, LMI and approval

Lender criteria

What Do Lenders Look for When Assessing a Home Loan?

Understanding what lenders assess helps you prepare a stronger application, and set realistic expectations before you approach anyone.

7 key factors lenders assess

  1. 01

    Income and employment stability

    Lenders want to see stable, ongoing income that can comfortably service the loan. PAYG employees with consistent salary history are assessed most straightforwardly. Self-employed borrowers, contractors and those with variable income face more scrutiny; lenders typically average the last two years of income and apply the APRA-mandated serviceability buffer of 3% above the actual loan rate.
    How we handle it

    We assess your income presentation before approaching any lender, so we target those whose assessment methods work most favourably for your specific situation.

  2. 02

    Expenses and living costs

    Lenders assess your declared living expenses against benchmark figures (the Household Expenditure Measure, or HEM) and use whichever is higher. Borrowers with higher declared expenses, or multiple dependants, may find their borrowing capacity reduced more than expected.
    How we handle it

    We factor this into our lender matching from day one, so there are no surprises during the assessment process.

  3. 03

    Existing debts and credit commitments

    Every existing debt, credit cards, personal loans, car loans, HECS/HELP debt, other mortgages, reduces your borrowing capacity. Even unused credit card limits count toward your assessed liabilities.
    How we handle it

    We review your full debt position before approaching lenders and advise where reducing or closing existing facilities could meaningfully improve your borrowing capacity.

  4. 04

    Credit history

    Lenders pull your credit report as part of the assessment process. Missed payments, defaults, court judgements or multiple recent credit applications can all affect approval outcomes and the rate you're offered.
    How we handle it

    If your credit history has any issues, we identify the right lender from the start, rather than applying to the wrong one and generating an unnecessary rejection on your file.

  5. 05

    Deposit size and LVR

    The larger your deposit, the lower your loan-to-value ratio (LVR) and the more lender options you have access to. A 20% deposit (80% LVR) avoids LMI and opens the full market. A smaller deposit still has options, but lender choice narrows, and rates are typically higher.
    How we handle it

    We are transparent about these trade-offs so you can make an informed decision.

  6. 06

    Property type and location

    Not every property passes a lender's security assessment. Small apartments (particularly studios under 50 square metres), properties in certain high-density buildings, homes in remote postcodes, or properties with structural or title issues can attract reduced LVR limits or outright lender declines.
    How we handle it

    We identify any potential security issues with a property before your application is lodged, so you're not caught off guard.

  7. 07

    Loan purpose

    Owner-occupier loans attract lower rates and broader lender choice than investment loans. This is a regulated difference: APRA requires lenders to hold more capital against investment loans, which is reflected in the pricing gap between owner-occupier and investor rates.
    How we handle it

    If you're purchasing an investment property, we structure the loan to maximise flexibility and manage your overall portfolio debt position.

We assess all of these factors before we approach any lender, so we present your application to the most suitable lenders from the start, not after a rejection has already marked your credit file.

Want to strengthen your application? Get a free strategy call and we'll run through your situation so we target the right lenders from day one.

Sumit · 1:35
What banks look at before they lendSumit Joshi, RyRo Loan Centre · income, debts and savings

Belinda White

2 years ago on Google

Google

Sumit is an outstanding mortgage broker. He patiently worked through our application and got us an awesome result when many other brokers wouldn't assist as we are small business owners. Thank you!

Grants and schemes

Government Help Available When Buying a Home in NSW

Understanding what government support is available before you buy can save you tens of thousands of dollars in upfront costs.

Minimum deposit with no LMI under the 5% Deposit Scheme
5%
Source: Housing Australia, checked Nov 2026
Scheme price cap for Sydney and major NSW regional centres
$1.5m
Source: Housing Australia, checked Nov 2026
First home buyers pay no NSW transfer duty up to this price
$800k
Source: Revenue NSW, checked Nov 2026

4 key areas of government support:

1. NSW Stamp Duty (Transfer Duty) on Home Purchases

Stamp duty applies to all property purchases in NSW and must be paid within 3 months of signing the contract of sale. It cannot typically be added to your mortgage and is calculated on the purchase price or market value, whichever is higher.

First home buyers may be fully exempt on purchases up to $800,000 or receive a concessional rate from $800,001 to $1,000,000 under the First Home Buyers Assistance Scheme (FHBAS).

Use our NSW Stamp Duty Calculator to estimate what's payable on your specific purchase.

2. NSW First Home Owner Grant (FHOG)

First home buyers purchasing or building a new home in NSW may qualify for the NSW First Home Owner Grant: a one-off $10,000 tax-free payment from the NSW Government. To qualify, the property must be brand new and never previously occupied or sold as a residence. Price caps apply: the property must not exceed $600,000 for a new dwelling, or $750,000 combined land and construction value for a house and land package.

Purchasers must be Australian citizens or permanent residents, aged 18 or over, and must not have previously owned property in Australia. You must move into the home within 12 months of settlement and live there for at least 12 continuous months. The grant applies to new homes only, not established property purchases.

3. Australian Government 5% Deposit Scheme (Home Guarantee Scheme)

From 1 October 2025, the Australian Government's Home Guarantee Scheme (commonly referred to as the 5% Deposit Scheme) has been significantly expanded: no income caps, no limit on the number of places available, property price cap of $1,500,000 for Sydney and NSW regional centres (Newcastle and Lake Macquarie, Illawarra) and $800,000 for other NSW areas.

Eligible buyers purchase with a 5% deposit; the government guarantees up to 15% of the loan value, so the lender treats you as having a 20% deposit and LMI is avoided. The scheme is applied through participating lenders. We confirm your eligibility and match you with the right participating lender.

4. Help to Buy Scheme (Launched December 2025)

The Australian Government's Help to Buy Scheme launched on 5 December 2025. It is a shared equity program where the government contributes up to 40% of the purchase price for a new home, or 30% for an existing home, in exchange for an equivalent equity stake in the property. Income caps apply: $100,000 per year for individual applicants; $160,000 for joint applicants and single parents. Minimum 2% deposit required.

10,000 places available per year nationally (approximately 3,000 for NSW buyers). NSW property price caps: up to $1,300,000 in Sydney and regional centres; up to $800,000 in other NSW areas. You own the home and live in it; the government shares in any gains or losses when you sell or buy back their share. Our Help to Buy scheme guide for Sydney buyers goes through it in full.

The Family Home Guarantee supports eligible single parents with at least one dependent child to purchase with as little as a 2% deposit, with the government guaranteeing up to 18%. You do not need to be a first home buyer to access this scheme.

For a full breakdown of every grant and scheme, see our First Home Buyers page. Want to check what you qualify for? Get a free strategy call and we'll run through grants, stamp duty exemptions and scheme eligibility for your specific situation.

Sumit · 1:26
The 5% Deposit Scheme and NSW stamp duty togetherSumit Joshi, RyRo Loan Centre · scheme rules and NSW duty
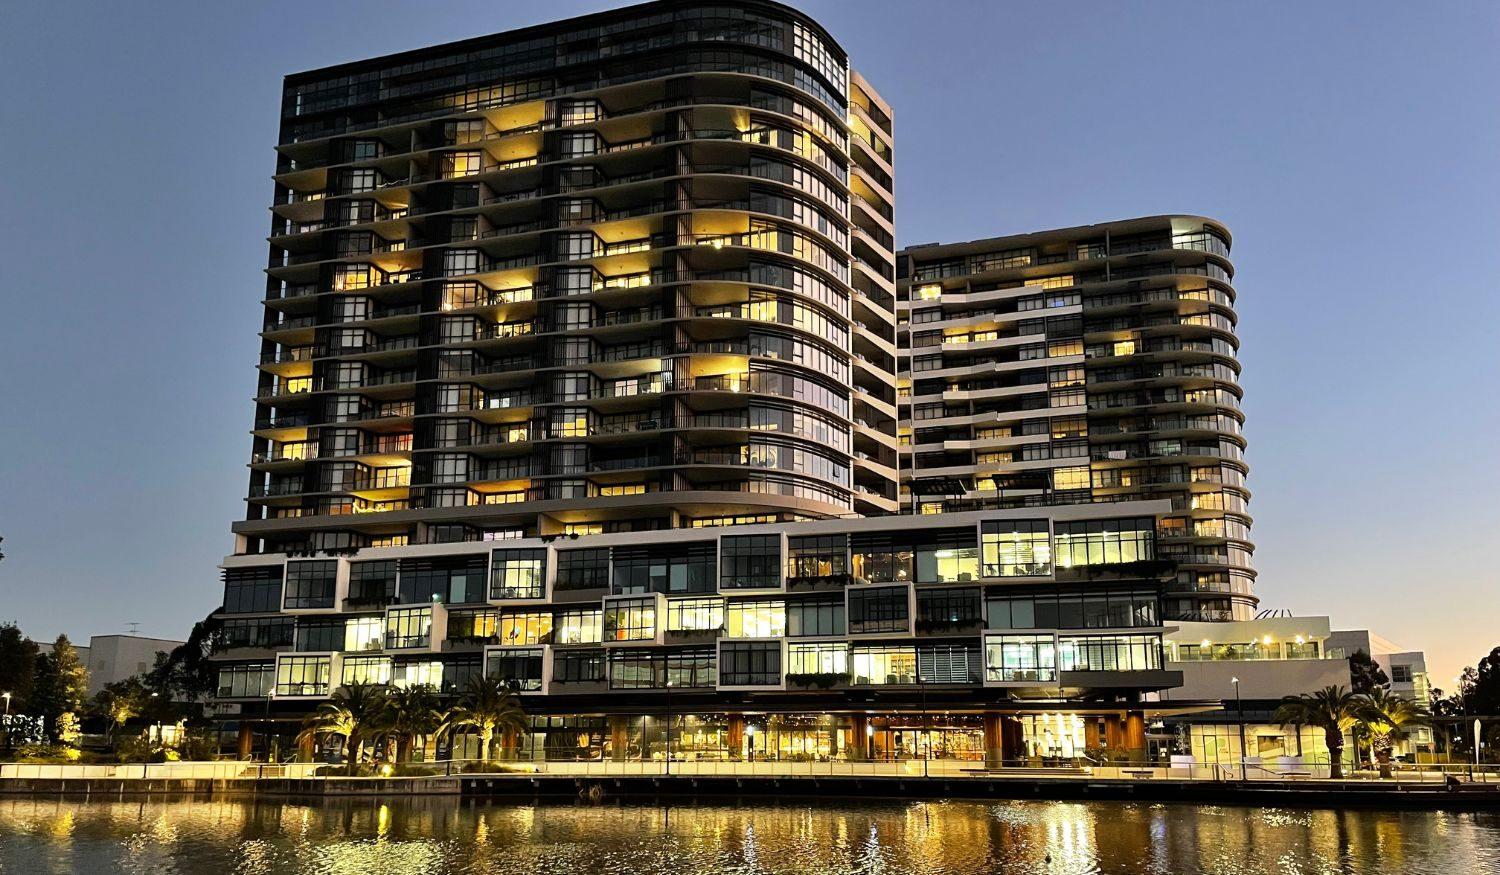
Tower A Esplanade building at Norwest at dusk, home of RyRo Loan Centre
Our office at Tower A, Norwest, in Sydney's Hills District.

Where we help

Home Loans in Sydney, NSW and Across Australia

RyRo Loan Centre is based in Norwest in Sydney's Hills District, and we work with home loan borrowers across all of Sydney, regional NSW and Australia. As a mortgage broker in the Hills District and Norwest, we understand the local property market deeply, from Castle Hill, Baulkham Hills, Kellyville, Rouse Hill and Norwest itself, through to established suburbs across the North Shore, Inner West, Eastern Suburbs, Southwest Sydney and the full Sydney metropolitan area.

Sydney's property market is one of the most competitive in the world, and having pre-approval in place before you start inspecting can be the difference between winning and losing the home you want. We work fast, communicate clearly and make sure our clients are ready to act when the right property comes along.

Outside Sydney?

For borrowers outside Sydney, in Newcastle, the Central Coast, Wollongong, the Hunter Valley, regional NSW and across Victoria, Queensland, South Australia and Western Australia, we arrange home loans through our national lender panel. Stamp duty exemptions and grant eligibility vary by state, and we always confirm what applies to your specific location and situation.

5 common home loan enquiries we assist with:

  • First home buyer loans in Sydney under the 5% Deposit Scheme with a $1,500,000 price cap
  • Home loan pre-approval for buyers actively searching in Sydney's competitive auction market
  • Refinancing home loans for existing borrowers on rates that no longer reflect the current market
  • Investment home loans structured to support both single-property buyers and growing portfolios
  • Construction and home and land package loans for buyers building in Sydney's growth corridors

Whether you're a first-time buyer or an experienced property investor, our team brings the same expertise, lender access and clear advice to every enquiry. Buying or refinancing in Sydney, NSW or elsewhere? Get a free strategy call and we'll match you to the right lender for your situation and location.

Sound familiar?

Home loan situations we sort out every week

Most people who call us about a home loan are in one of these spots. Here is what usually gets in the way, and what we do about it.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Buying the next place before selling

    The challenge: You have found the next home but the current one is not sold, and you cannot see how the deposit works.

    How we handle it

    We work out your usable equity, check you can carry both loans for a while, and line up the right structure before you bid.

  • A fixed rate about to end

    The challenge: Your fixed term rolls onto the lender’s revert rate soon and you do not know if staying is the best deal.

    How we handle it

    We compare your revert rate with the market, ask your lender for a better offer, and switch you only if the numbers stack up.

  • Bidding at auction this month

    The challenge: Auctions are unconditional, so you need to know your limit and have the lender ready before the day.

    How we handle it

    We get your pre-approval in place, check the lender is comfortable with the property type, and tell you your real ceiling.

  • Self-employed with a strong business

    The challenge: Your business is doing well but the tax returns do not show it yet, or the bank does not read them the way you do.

    How we handle it

    We present your income the way lenders assess it and go to lenders whose policy suits your structure, full doc or low doc.

  • Building or renovating

    The challenge: The builder wants a fixed-price contract signed, the lender wants it before approval, and the dates have to line up.

    How we handle it

    We match you to a lender that suits your builder and your stages, so each progress payment is paid on time.

  • Less than 20% saved

    The challenge: You are close on the deposit but LMI, stamp duty and the schemes make the maths hard to follow.

    How we handle it

    We check the schemes you qualify for, price LMI where it applies, and show you the deposit you really need.

These are common situations, not client stories. Every loan depends on your circumstances and the lender's policy.

5 reasons to work with us

Why Choose RyRo Loan Centre as Your Mortgage Broker in Sydney?

Real people. Real expertise. Here's what you can expect when you work with us.

Sumit Joshi standing at the RyRo Loan Centre reception in Norwest
Sumit at the RyRo Loan Centre reception in Norwest.

Access to 50+ Lenders

Major banks, second-tier, non-bank and specialist lenders, so you are never limited to three or four banks.
Read more about this

Finding the right home loan isn't just about finding a low rate, it's about finding a lender whose policy, assessment criteria and loan structure genuinely suit your situation. We compare home loans from major banks, second-tier lenders, non-bank lenders and specialist lenders that aren't accessible directly to the public.

Our panel of 50+ lenders means we're never limited to what three or four banks can offer you.

$0 Broker Fees

The lender pays us when your loan settles. No charge for the strategy call and no obligation to go ahead.
Read more about this

Our service is completely free to you. We're paid a commission by the lender when your loan settles. That means you get expert home loan advice, full lender comparison, application management, negotiation and settlement support at no direct cost to you.

There are no hidden fees, no charges for strategy calls and no obligation to proceed.

Local Sydney and Hills District Knowledge

Based in Norwest. We know which lenders move fastest at auction and how the Hills market behaves.
Read more about this

We're based in Norwest and we understand Sydney's property market and lending conditions: which lenders move fastest in competitive auction environments, which lenders have the most favourable policies for specific property types, and how the Hills District, Northwest Corridor and broader Sydney market behaves.

Local knowledge matters when time and accuracy both count.

End-to-End Process Management

Paperwork, lender follow-ups and valuation issues handled for you, with updates at every stage.
Read more about this

From your first strategy call through to settlement, we handle the paperwork, prepare your application, liaise with lenders, manage valuation issues and keep you updated at every stage.

Our settlement liaison Kathryn coordinates with your conveyancer and the lender so nothing falls through the cracks between exchange and settlement day.

Strategy First, Product Second

We start with what you are buying and why, then work back to the right lender and loan.
Read more about this

Most borrowers don't need the cheapest rate on a comparison site. They need the right loan, structured correctly for their actual situation, with a lender who will support them through approval and beyond.

We start with your strategy, what you're buying, why, what you plan to do with it, and work back to the right lender and product. That approach produces better outcomes than rate-shopping alone.

More than 2,500+ Australians have trusted RyRo Loan Centre to help them find the right home loan. From first home buyers navigating Sydney's market for the first time to experienced investors refinancing and restructuring, the feedback from our clients reflects the same thing consistently: clear communication, genuine expertise and a process that's smoother than they expected. Rated 5.0 from 360+ Google reviews.

Get my free strategy call

We generally respond within an hour.

Your process

Simple, Clear, Fast: Your Home Loan Process

From your first call to settlement, here's how we work with you.

6 steps from first call to settlement

  1. Step 1: Free Strategy Call

    Tell us what you are buying or refinancing, your deposit or equity and your income type.

    What happens in this step

    Tell us what you're trying to achieve: what you're buying (or whether you're refinancing), your approximate purchase price or current loan balance, your deposit or equity position, and your income type.

    We assess your situation, identify any potential complications upfront, and shortlist the most suitable lenders from our panel of 50+.

  2. Step 2: Situation Assessment and Lender Matching

    We match you to lenders whose policy fits, not whoever has the lowest headline rate this week.

    What happens in this step

    We review your full financial position: income, expenses, existing debts, credit profile, deposit and the property you're purchasing. We match you to lenders whose policies genuinely fit your scenario, not just whoever has the lowest headline rate this week.

    For investors and self-employed borrowers, this step is particularly important: the right lender match can significantly affect both your approval outcome and your ongoing costs.

  3. Step 3: Application and Documentation

    One clear document list up front, so there is no back and forth with the lender.

    What happens in this step

    We handle the paperwork and prepare a strong, complete application. We tell you exactly which documents are required, payslips, tax returns, BAS statements, bank statements, identification, so there's no back-and-forth or repeated requests.

    A well-prepared, complete application moves significantly faster and reduces the chance of a lender requesting additional information mid-process.

  4. Step 4: Valuation and Approval

    The lender values the property while we keep your application moving.

    What happens in this step

    The lender commissions an independent valuation of the property. We manage communication with the lender throughout to keep your application progressing.

    Most straightforward applications receive pre-approval within 1 to 2 business days. Full approval including valuation typically takes 5 to 10 business days, depending on the lender and the property.

  5. Step 5: Settlement

    Kathryn coordinates your conveyancer and the lender through to settlement day.

    What happens in this step

    We coordinate settlement with your conveyancer and the lender. Kathryn keeps you informed so you always know where things stand, from the day contracts are exchanged right through to title transfer on settlement day.

    No surprises.

  6. Step 6: Post-Settlement Review (ongoing)

    We keep an eye on your loan and get in touch when a better option appears.

    What happens in this step

    Your home loan doesn't end at settlement. We monitor rates and policy changes across our lender panel and reach out when a better option becomes available, whether that's through refinancing, restructuring or switching products.

    Our relationship with you continues for as long as your loan is in place.

Start step 1

Step 1 takes about two minutes.

Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan Centre · every step until settlement

Google reviews

What Our Customers Say

Real Google reviews of RyRo Loan Centre, word for word.

Google

5.0

From 360+ Google reviews

Sumit · 2:56
Approved in days after her broker went quietSumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • O D

    2 weeks ago on Google

    Google

    My wife and I are very happy and very greatful for all the help Sumit from RYRO LOAN CENTRE has helped us once again. We are so blessed to have had the opportunity to meet such a kind, hard working and wonderful person who will go above and beyond to get our home loan refinancing approved. So thank you very much summit. We will definitely be going back to RYRO team when we buy our next property. We will also recommend RYRO Loan Centre, especially Sumit to our family & friends! They are simply the BEST!! 😊

    O D

    Google2 weeks ago on Google

    My wife and I are very happy and very greatful for all the help Sumit from RYRO LOAN CENTRE has helped us once again. We are so blessed to have had the opportunity to meet such a kind, hard working and wonderful person who will go above and beyond to get our home loan refinancing approved. So thank you very much summit. We will definitely be going back to RYRO team when we buy our next property. We will also recommend RYRO Loan Centre, especially Sumit to our family & friends! They are simply the BEST!! 😊

  • chris sukumar

    5 months ago on Google

    Google

    Sumit at Ryroloan Centre made our first home possible Five stars for Sumit Joshi at Ryroloan Centre. As first home buyers we had no idea where to start. Sumit was easy to contact from day one. He picked up calls, replied to texts fast, and explained everything in simple terms. He secured us a really good rate that beat what our bank offered. The whole pre-approval and settlement process was smooth because he stayed on top of every document and deadline. I want to thank Dean and whole team thank you all. Couldn’t recommend Sumit more highly if you’re a first home buyer.

    chris sukumar

    Google5 months ago on Google

    Sumit at Ryroloan Centre made our first home possible Five stars for Sumit Joshi at Ryroloan Centre. As first home buyers we had no idea where to start. Sumit was easy to contact from day one. He picked up calls, replied to texts fast, and explained everything in simple terms. He secured us a really good rate that beat what our bank offered. The whole pre-approval and settlement process was smooth because he stayed on top of every document and deadline. I want to thank Dean and whole team thank you all. Couldn’t recommend Sumit more highly if you’re a first home buyer.

  • Karra Le

    5 months ago on Google

    Google

    For someone like us who's completely new to the home loan process and first home buyers, they're very responsive and answered all the questions we have. Sumit, Dean and Meet helped us get through the process and supported us all the way till the end. Their team is very knowledgeable and professional. Highly recommended!

    Karra Le

    Google5 months ago on Google

    For someone like us who's completely new to the home loan process and first home buyers, they're very responsive and answered all the questions we have. Sumit, Dean and Meet helped us get through the process and supported us all the way till the end. Their team is very knowledgeable and professional. Highly recommended!

  • Rene Rose Mae Tagle

    8 months ago on Google

    Google

    Sumit was instrumental in securing our first home whilst maintaining a constant channel for communication. Very patient with all our queries. He helped navigate the first home buyer provisions available to us and provided us with the product we were after. Can highly recommend.

    Rene Rose Mae Tagle

    Google8 months ago on Google

    Sumit was instrumental in securing our first home whilst maintaining a constant channel for communication. Very patient with all our queries. He helped navigate the first home buyer provisions available to us and provided us with the product we were after. Can highly recommend.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie
Sumit Joshi, 2020 Broker of the Year

Broker of the Year 2020Awarded to Sumit Joshi

Who you will deal with

The RyRo Team

Sumit Joshi JP · Principal broker · Credit Rep 446824

Whether you're buying your first home or your fifth investment property, we'll find the right home loan option for your situation.

You deal with Sumit from the first call. He reads your situation, compares lenders across the panel, prepares the application and stays on it until the loan settles. Kathryn then works with your conveyancer and the lender so settlement day runs on time.

We work from the Norwest office in the Hills District. Meet us in person, or do it all by phone and email from anywhere in Sydney. Read more about RyRo Loan Centre or see our awards and recognition.

Kathryn Thomas, loan processor at RyRo Loan Centre

Kathryn ThomasSettlement and client liaison. Kathryn works with your conveyancer and the lender from exchange to settlement day.

  • We generally respond within an hour
  • Free strategy call, no obligation

Why Sydney borrowers choose RyRo

Rated by clients, recognised by lenders

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • MFAA 10 year member badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • AFG Excellence Awards finalist 2024 badge
  • AFG Excellence Awards finalist 2023 badge
  • AFG Excellence Awards finalist 2022 badge
  • AFG Award winner 2019 badge
  • AFG Award winner 2018 badge
  • AFG Award winner 2017 badge
  • AFG Award winner 2016 badge
  • AFG Award winner 2015 badge
  • AFG Award winner 2014 badge
  • AFG Award winner 2013 badge

AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026

Denise

3 years ago on Google

Google

Really appreciated the help and advice provided. Answered all my questions and everything went smoothly. Thank you Sumit and Kathryn! Would highly recommend.

Read all 360+ Google reviews

Answers on demand

Frequently Asked Questions

Answers to common questions about home loans, deposits, approval times, refinancing and upsizing, and how we help Sydney and NSW borrowers.

15 answers in 4 topics

Most common questions

  • A home loan (also called a mortgage) is a type of finance used to purchase residential property. You borrow a set amount from a lender, use the property as security, and repay the loan with interest over a set term, typically 25 to 30 years. Home loans come in variable rate, fixed rate and split formats, with principal and interest or interest-only repayment structures. The right combination depends on your situation, goals and property type. We explain the options clearly and recommend based on your actual circumstances, not a generic template.

  • Most standard home loans require a minimum 5% to 20% deposit depending on the lender and loan type. Borrowing above 80% LVR typically triggers Lenders Mortgage Insurance (LMI). A 20% deposit avoids LMI and generally delivers better rates and broader lender access. From 1 October 2025, eligible first home buyers can purchase with as little as a 5% deposit under the expanded Home Guarantee Scheme, avoiding LMI entirely through a government guarantee, with no income caps and a $1,500,000 price cap for Sydney. Contact us to confirm what deposit you actually need for your specific purchase and situation.

  • Your borrowing capacity depends on your gross income, living expenses, existing debts and the loan's assessed repayments at a stress-tested rate (3% above the actual loan rate, per APRA guidelines currently in place). Different lenders calculate borrowing capacity differently, the same borrower can receive meaningfully different results from different lenders depending on how they assess income and expenses. Use our Borrowing Power Calculator for an estimate, or speak with us for a detailed assessment based on your actual figures (no credit check, no obligation).

    Borrowing power calculator
  • There's no single best home loan rate, the most competitive rate available to you depends on your deposit size, loan purpose (owner-occupier or investment), repayment type (P&I or interest-only), loan amount and financial profile. Rates offered to new borrowers are often sharper than what existing borrowers are paying, and that gap is exactly why a loan you set up two or three years ago is worth reviewing. We compare options from 50+ lenders and negotiate on your behalf to find the most competitive rate and structure for your specific scenario.

  • No. RyRo Loan Centre charges $0 broker fees. We're paid by the lender when your loan settles. You get expert advice and comparison at no extra cost.

Rates & process

  • Home loan pre-approval (also called conditional approval or approval in principle) is a lender's indication that they'll lend you up to a specified amount, subject to the property you purchase meeting their criteria. It's typically valid for 90 days. In Sydney's competitive auction market, having pre-approval in place before you start inspecting or bidding is strongly advisable. For most straightforward applications, we obtain pre-approval within 1 to 2 business days.

  • Pre-approval is typically obtained within 1 to 2 business days for straightforward applications. Full approval, including formal property valuation, typically takes 5 to 10 business days. Complex applications (self-employed income, multiple existing properties, unusual property types) may take longer. We manage the process and communicate with lenders throughout to keep your application moving.

  • This depends on your cash flow needs, risk tolerance and view of rate movements. Variable loans offer flexibility (offset accounts, unlimited extra repayments, redraw) and benefit when rates fall. Fixed loans offer repayment certainty for a defined period but restrict flexibility. The cash rate has moved more than once in 2026, so the timing of a fixed term matters. There's no universally right answer, we work through the options with you based on your specific position and the rate environment at the time you apply.

  • LMI is an insurance premium payable by the borrower when borrowing above 80% of the property value. It protects the lender, not you, in the event of default. The cost varies depending on your LVR and loan size, and can reach over $30,000 for higher LVR loans on larger purchase prices. LMI can be avoided by having a 20% deposit, qualifying for the government's 5% Deposit Scheme (no LMI with 5% deposit from 1 October 2025), using an eligible guarantor, or accessing certain professional packages offered by specific lenders. We assess your options and work through whether paying LMI makes financial sense for your situation versus waiting to save a larger deposit.

    LMI calculator

Refinancing & upsizing

  • Refinance in 2026 if your current rate is more than about 0.5% above what you could get today, your loan has not been reviewed in two or more years, or your property has grown enough in value to push your LVR under 80%. If your rate sits about 0.5% above what a new borrower is offered, a $750,000 loan is costing you roughly $3,750 a year more than it needs to. The exceptions are worth knowing: if you are locked into a fixed rate, break costs can wipe out the saving, and if your LVR is above 80% you may trigger LMI again on the new loan. A free review tells you which side of the line you sit on.

    Our refinancing service
  • Yes, and it is how most Sydney upsizers move without selling first. Lenders will generally let you borrow up to 80% of your current property value, so your usable equity is (current value × 80%) minus your outstanding balance. You draw that equity against your existing home, use it for the deposit and purchase costs on the next place, and take a separate loan for the balance. The constraint is rarely the equity, it is serviceability: you need to show you can carry both loans assessed at your rate plus APRA's 3% buffer. We model the whole structure before you start bidding.

    Equity home loans
  • Yes. Refinancing your home loan is one of the most financially impactful moves an existing homeowner can make. Borrowers who set up their loan some years ago are often paying well above what new borrowers can access today. We compare your current loan against the full market, calculate whether the savings outweigh any switching costs, and manage the refinancing process from start to finish. Most refinances settle within 3 to 6 weeks of application.

NSW & specialist

  • Yes. Transfer duty (stamp duty) applies to all property purchases in NSW and must be paid within 3 months of signing the contract of sale. If you're a first home buyer purchasing a new or established home, you may be fully exempt from stamp duty on purchases up to $800,000, or receive a concessional rate on purchases from $800,001 to $1,000,000 under the NSW First Home Buyers Assistance Scheme (FHBAS). For example, stamp duty on an $800,000 home in NSW would ordinarily be approximately $31,335, eligible first home buyers pay nothing. Use our Stamp Duty Calculator to estimate your liability and speak with us to confirm your eligibility.

    NSW stamp duty calculator
  • Yes. Self-employed borrowers have access to both standard and low doc home loans. Standard home loan assessment typically requires two years of tax returns and business financials confirming the income you're relying on. Low doc loans allow alternative income documentation (BAS statements, accountant's declarations, business bank statements) for those who can't or prefer not to use standard documents. We have extensive experience placing self-employed borrowers with lenders who assess complex income fairly, and we know which lenders are most accommodating for different business structures and income patterns.

    Low doc home loans
  • Yes, and for investors, working with a broker is particularly valuable. Investment loans are assessed differently to owner-occupier loans, and lender policies around investor serviceability, portfolio limits and interest-only terms vary significantly across the market. We work with investors at every stage of their portfolio journey and structure loans to maximise borrowing capacity, cash flow and flexibility for future purchases.

    Investment loans
View all FAQs

Free tools

Plan Your Home Purchase or Refinance with Our Free Calculators

Before you apply for a home loan, knowing your numbers makes every conversation more productive. Use our free tools to estimate before you commit.

What the four core calculators tell you

Borrowing Power Calculator. Understand how much you could borrow based on your income, expenses and existing debts. A useful starting point before you begin property searching, and a good way to test how different scenarios (closing a credit card, paying off a debt) affect your borrowing capacity.

Loan Repayment Calculator. Estimate your monthly home loan repayments based on loan amount, interest rate and term. Useful for modelling different deposit scenarios, rate changes and loan amounts before you engage a lender.

NSW Stamp Duty Calculator. Calculate the transfer duty payable on your property purchase in NSW and check your first home buyer exemption eligibility under the First Home Buyers Assistance Scheme.

Home Loan Offset Calculator. Model the interest savings and loan term reduction that an offset account delivers over the life of your loan. A powerful tool for understanding the real value of offset versus redraw, and whether a slightly higher rate with a full-featured offset account is worth it for your situation. Does a fixed rate home loan have an offset account?

Ready to discuss your numbers?

Get a free strategy call and we'll work through figures based on your actual situation.

From the blog

Home loan guides from the RyRo blog

Three of the questions we get asked most: how to buy and sell without ending up homeless or double mortgaged, how much deposit you actually need in Sydney, and how fast you can realistically clear the loan.

Talk to Sumit

Ready to Find Your Home Loan?

Join 2,500+ Australians who've trusted RyRo Loan Centre with their lending. $0 fees. Expert advice. No credit check.
Sumit Joshi, principal broker at RyRo Loan Centre

Start My Home Loan Journey

We'll call you to discuss your situation. No obligation, no credit check.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reads your details and calls you back
  • No obligation and no credit check
  • Free for home loans: the lender pays us
Sumit · 2:59
From two properties to four in six monthsSumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Lenders on our panel
50+
“Sumit has been amazing through the whole process of refinancing our home loan. So professional and friendly. I highly recommend him to anyone who is looking for a mortgage broker!”
Annaliza Benitez · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026.

Get my free loan review