The RBA lifted the cash rate three times between February and May 2026 and has held it at 4.35% since, with the next decision due 29 September 2026. On the $842,000 NSW average loan, cutting your rate by half a percentage point is worth $271 a month. We do that maths on your actual balance before you commit to anything.
RyRo Loan Centre is a refinance broker based in Norwest. We compare 50+ lenders, run the break-even maths before you commit, and manage the switch from application through to discharge of your old mortgage. You pay us nothing.
50+Lenders
FastPre-approval
$0Broker Fees
5.0/5 Rating359+ Reviews
13+ YearsTrusted Professionals
100% SatisfactionProven results for 2500+ clients
Start Here
Find out if you can get a better deal on your home loan
Tell us your current rate and remaining balance and we'll identify how much you could save, and whether refinancing makes sense for your situation.
No Credit Check100% Obligation-Free
Join thousands of clientsWe generally respond within an hour
“Just tell us what you're buying, we'll match you to the right lender. No pressure, no obligation.”
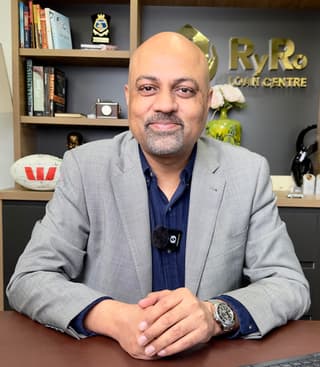
Sumit · Director & Senior Loan Specialist
By submitting, you agree to our privacy policy and terms of service.
The Ryro Team
We review, compare and refinance home loans across 50+ lenders, negotiating on your behalf so you can access a sharper rate, better features or more flexible loan structure.
Meet the team
Sumit
Director & Senior Loan Specialist
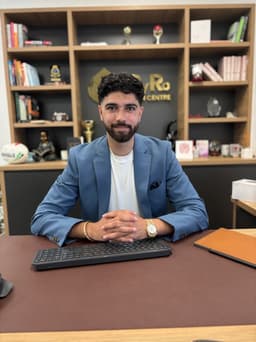
Rohan
Asset Finance Specialist
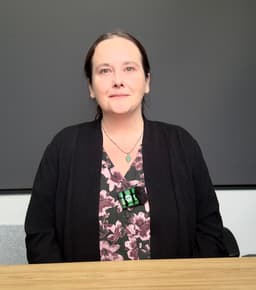
Kathryn
Settlement & Client Liaison
Why work with us
50+Lenders
FastPre-approval
$0Broker Fees
5.0/5 Rating359+ Reviews
13+ YearsTrusted Professionals
100% SatisfactionProven results for 2500+ clients
Overview
Refinancing at a glance
Understanding the current rate environment is the starting point for every refinancing decision. We compare 50+ lenders and manage the entire process on your behalf.
What is refinancing?
Refinancing means replacing your current home loan with a new one, with your existing lender (internal) or a different lender (external). You get a new rate, structure and features. Around 34,800 Australians switch lenders every month.
The rate gap
The average variable rate is often 0.5% to 1.5% higher than the best available rate for refinancers. On a $650,000 balance, a 1% rate cut can save over $4,600 per year. We find out where you stand; free, no obligation.
We manage the process
From rate review to settlement, we prepare your application, coordinate valuation, track approval and manage discharge with your existing lender. You deal with us, not two lenders.
Break-even and savings
Use our Loan Repayment Calculator to model repayments, or speak with us for a full cost-benefit and break-even analysis, obligation-free.
Start Here
Find out if you can get a better deal on your home loan
Tell us your current rate and remaining balance. We'll identify how much you could save and whether refinancing makes sense.
No Credit Check100% Obligation-Free
Join thousands of clientsWe generally respond within an hour
“Just tell us what you're buying, we'll match you to the right lender. No pressure, no obligation.”
Sumit · Director & Senior Loan Specialist
By submitting, you agree to our privacy policy and terms of service.
Start here
What does a refinance broker do?
A refinance broker compares your current home loan against the whole lender market, works out whether switching actually leaves you in front after costs, then handles the application, valuation, approval and settlement so you never have to negotiate with two banks at once.
That is the short version. In practice, five things happen when you hand your loan to us:
1
We price your loan against the market
We take your current lender, rate, balance, remaining term and loan features, then compare that against live pricing from 50+ lenders. Your own bank will only ever show you their shelf. We show you everyone.
2
We do the break-even maths before you commit
Discharge fee, application fee, valuation, government registration fees, break costs if you are fixed, and a fresh LMI premium if your LVR is still above 80%. Total those, divide by the monthly saving, and you have the month the switch starts paying you. If that number does not work, we say so.
3
We pick the lender, not just the rate
The cheapest advertised rate is useless if the lender will not accept your income type, values your property conservatively, or takes nine weeks to assess. We match you to a lender whose credit policy and valuation approach suit your file.
4
We prepare and lodge the application
Payslips, statements, rates notice, identification, other debts. We check the file before it goes in, because the number one cause of a refinance dragging past eight weeks is a missing document.
5
We run the settlement and the discharge
Your outgoing lender has no incentive to make leaving easy. We chase the discharge authority, coordinate both sides and confirm the old mortgage is released from your title.
What it costs you: nothing. The lender pays our commission when the loan settles. It is not added to your rate and it is not added to your balance. We also work under the best interests duty in the National Consumer Credit Protection Act, which means the recommendation has to be the right one for you. Book a free strategy call or send us your current rate and we will tell you where you stand.
Worked example
What is a rate cut actually worth on a NSW home loan?
On the $842,000 NSW average owner-occupier loan, every 0.25 percentage points you cut off your rate is worth about $136 a month. A half point is $271. A full point is $536.
Most refinancing pages pick a rate they claim you are on, pick a sharper one they claim you can get, and show you the difference. We cannot know either of those numbers about you, so here is the table the other way round. Find the improvement you think you can get, and read across.
Value of a rate reduction on an $842,000 NSW average owner-occupier home loan over a 30 year term, principal and interest
Rate cut
New rate
Monthly repayment
Saved per month
Saved per year
Saved over 5 years
Less owing after 5 years
0.25%
6.05%
$5,075
$136
$1,637
$8,186
$2,366
0.50%
5.80%
$4,940
$271
$3,255
$16,277
$4,811
0.75%
5.55%
$4,807
$405
$4,854
$24,271
$7,334
1.00%
5.30%
$4,676
$536
$6,433
$32,165
$9,938
1.25%
5.05%
$4,546
$666
$7,991
$39,957
$12,622
How this table was built, September 2026. Balance $842,000 is the NSW average owner-occupier loan size from ABS Lending Indicators, June quarter 2026, released 14 August 2026. The Australian average is $731,000. The starting rate of 6.3% is the average rate on outstanding owner-occupier variable loans from RBA Statistical Table F6, data as at June 2026. Repayments use the standard amortisation formula over a 30 year term, principal and interest, with the rate held flat for the whole period. This is arithmetic on published averages, not a quote and not a prediction. Your own saving depends on your balance, your actual rate, your LVR, your income type and your credit file, and refinancing costs are excluded from these columns. See the break-even table below for those.
The last column is the one people miss
A lower rate does not just cut the repayment. If you keep paying the same amount, more of it goes to principal. On a half point improvement you would owe $4,811 less after five years than you otherwise would, on top of the $16,277 you did not pay in interest. That is the part a rate comparison table never shows you, and it is why we look at the whole structure rather than the headline number.
Run your own numbers first
Put your balance and a lower rate into our home loan repayment calculator to see the monthly difference on your own loan. If you keep a cash balance in your everyday account, also try the home loan offset calculator, because moving to a loan with a proper offset account can be worth more than a small rate cut. Then bring the numbers to us and we will check them against what you can actually be approved for.
Market context
Last updated: September 2026
When to refinance a home loan, and whether 2026 is the year
2026 is a rate-rising year, not a rate-falling one, and that changes the answer in two ways most refinancing advice has not caught up with.
Where the cash rate sits
The RBA raised the cash rate three times in 2026, by 25 basis points each in February, March and May, taking it from 3.60% to 4.35%. It has since held at that level twice, on 16 June and again on 11 August 2026. The next Board decision is 29 September 2026. The practical read for a borrower is simple: this is not a market where waiting is rewarded. If your loan has drifted, it will keep drifting.
The loyalty tax has closed, and almost nobody has noticed
For years the standard pitch was that lenders quietly punish existing customers, so you were probably paying 0.3 to 0.5 percentage points more than a new customer at the same bank. You will still find that claim on most broker websites. As at June 2026 it is not what the data shows.
RBA Statistical Table F6 puts the average rate on outstanding owner-occupier variable loans at 6.3%, and the average rate on new owner-occupier variable loans funded that month at 6.3%. The gap is roughly zero, and it has been roughly zero every month for the past year. That makes sense mechanically. The loyalty tax opened up during the 2020 to 2023 period when the RBA was cutting and banks passed the cuts to new customers faster than to the back book. In a rising market, both books move up together.
So why refinance at all in 2026? Because the average is not the point. The spread that matters is between the average and the sharp end of the market, and that spread is real. Averages hide it: a borrower on a competitive product and a borrower on a legacy product two years past its review both sit inside that 6.3% number. The question is not whether your bank is punishing you for loyalty. It is whether your specific loan is priced anywhere near what your specific profile could get today. That is a question about your file, not about the market.
If you fixed before 2026, your break cost is probably small
This is the second thing the rate rises changed, and it works in your favour. A fixed rate break cost is the lender recovering its economic loss when you exit early. It is driven by the movement in wholesale funding rates between the day you fixed and today, applied to your balance over the remaining term. When wholesale rates have fallen since you fixed, the lender loses money and the break cost is large. When they have risen, there is little or no loss to recover.
Wholesale rates have risen through 2026. For many borrowers who fixed before this year, the break cost that would have been prohibitive in 2021 or 2022 may now be modest or close to nil. That does not make breaking a fixed rate automatically right, and we will not tell you it does. But it does mean the assumption that you are locked in until expiry is worth testing rather than accepting. Break costs are lender-calculated and quote-specific, so we get you a written figure from your own lender before anyone makes a decision.
How many people are actually doing this
In the June quarter of 2026, Australians refinanced 103,046 loans worth $67.08 billion to a different lender, according to ABS Lending Indicators. Owner-occupier external refinancing was down about 1.1% on the same quarter a year earlier, while investor refinancing was up 5.3%. Volumes have eased slightly from the 2025 peak, which followed the rate cuts, but they remain historically high. Refinancing is where lenders grow their book when property turnover is subdued, and a borrower with 20% or more equity and a clean repayment record is exactly the file they compete for.
If you are rolling off a fixed rate
Loans revert to the lender's standard variable rate the day the fixed term ends, and the standard variable rate is usually one of the least competitive products on their shelf. If your fixed term ends in the next six to twelve months, start now so a new loan is ready to settle the week the fixed rate expires. You should not spend a single month on a revert rate.
Overview
What is refinancing a home loan?
Refinancing means replacing your current home loan with a new one, either with your existing lender or a different one, so you can reset the rate, the structure, the features and the term.
The process involves a new loan assessment, a property valuation, new loan documents, and a settlement where the new loan pays out the old one and takes over the mortgage on your title. Refinancing is not a sign of financial trouble. It is routine maintenance on the biggest debt you will ever carry.
The usual reasons are a lower rate, access to equity you have built up, consolidating high-interest debt, getting features your current loan does not offer such as a proper offset account, or restructuring after a change in your circumstances. See our full home loan services for the other loan types we handle.
Internal vs external refinancing
An internal refinance means renegotiating with your current lender or moving to a different product in their range. It is faster, involves less paperwork, and if they want to keep you they may sharpen the offer. The limit is obvious: you only get to choose from their products, and a lender that already has your business has less reason to fight for it.
An external refinance means moving to a new lender entirely, with a full application, valuation and settlement. It takes longer but it opens the whole market. Most refinancers end up switching lenders, because that is where the pricing is.
We do both. Our starting point is always to find the strongest option on the open market, then take that number back to your current lender and see if they will match it. Either way you win, and either way you do not have to make the phone call.
7Reasons
7 reasons Australians refinance their home loan
1
Cut the rate and cut the repayment
The most common reason and the easiest to quantify. If your loan settled two or more years ago and you have never asked for a review, your rate is almost certainly above the sharp end of the market. On the $731,000 Australian average owner-occupier loan over 30 years, a one percentage point reduction off the 6.3% average is worth roughly $465 a month. Over the remaining term that is tens of thousands of dollars. It is a 20 minute conversation to find out where you sit.
2
Access equity for renovations, an investment deposit or a second home
Every repayment builds equity, and Sydney price growth has built a lot more of it passively. A cash out refinance lets you take part of that equity as cash by refinancing to a larger loan. Most lenders cap total borrowing at 80% of the current property value, and the gap between that ceiling and your balance is your usable equity. Example: a home worth $1,200,000 with $500,000 owing gives you a ceiling of $960,000, so up to $460,000 is accessible. We check serviceability and the effect on your LVR before recommending it. Full detail on our home equity loans page.
3
Consolidate high-interest debt into the mortgage
Credit cards and unsecured personal debt carry far higher interest rates than a mortgage secured against your home, which is the whole reason consolidation appeals. Rolling those debts into the mortgage cuts the rate on them sharply and turns several payments into one. We will show you the actual rates on your own facilities side by side rather than working from typical ranges. The trap is term: stretching a $15,000 card balance over 25 years can cost more in total interest than clearing it in three years at the higher rate. We model both the monthly relief and the lifetime cost, and where consolidation makes sense we structure the loan so the consolidated portion gets paid down fast.
4
Your fixed term is ending
The day a fixed term expires, the loan reverts to the lender's standard variable rate, which is usually well above what they offer new customers. This is the single highest-value moment in a loan's life to refinance, because break costs no longer apply and you have complete freedom to move. Come to us six to twelve months before expiry and we will have a new loan ready to settle the week the fixed term ends.
If your income has grown, your other debts are gone, or you have had a windfall, refinancing to a shorter term cuts total interest hard. Trimming a year or two off the remaining term lifts the repayment modestly but removes a large amount of interest from the back end of the loan. We model a few term options against your cash flow so you can see the trade-off in dollars rather than in theory.
6
Get an offset account, redraw or a split structure
Plenty of borrowers are stuck on basic products with no offset, no redraw and no ability to split between fixed and variable, usually because they chose on advertised rate alone. An offset account is one of the strongest interest-saving tools available: every dollar sitting in it reduces the balance interest is charged on. Hold a steady $30,000 against a $600,000 loan and you are only paying interest on $570,000, while the money stays available. Sometimes the right structure beats a slightly lower rate. Test it on our offset calculator.
7
Your circumstances changed and your lender no longer fits
A separation that needs the debt restructured. A move from PAYG to self-employment that needs a lender comfortable with two years of business returns. An investment strategy that needs a lender who treats rental income generously. These are all valid reasons to move, independent of rate. Our panel of 50+ lenders includes specialists in PAYG, self-employed, investment and professional-category lending, so if your current lender's policy no longer matches your life, we will find one that does.
“Tell us your current rate and remaining balance and we'll identify how much you could save, and whether refinancing makes sense for your situation. No pressure, no obligation.”
Sumit, Director & Senior Loan Specialist
Free strategy call - no obligation
Get Expert Advice, Free
Tell us your current rate and remaining balance. We'll call you to run through your options and savings potential.
No Credit Check100% Obligation-Free
Join thousands of clientsWe generally respond within an hour
By submitting, you agree to our privacy policy and terms of service.
Costs
How much does it cost to refinance?
A standard external refinance in NSW costs roughly $500 to $2,000 all up, assuming your LVR is 80% or below, you are not breaking a fixed rate and no new LMI is payable. Break costs and LMI are the two things that can push it much higher.
The only part of that which is fixed and knowable in advance is the government title fee. NSW Land Registry Services charges $182.73 including GST to register a discharge of mortgage and the same again to register the new mortgage, under the 2026/27 schedule effective 1 July 2026. So $365.46 of your cost is set by the state and identical no matter which lender you move to. Everything else is lender-set and negotiable.
Here is where the rest of the money actually goes.
The three cost buckets
1. Leaving your current lender
Your current lender charges a discharge fee to close the loan and release the mortgage from your title. This is typically $150 to $500. Commonwealth Bank publishes $350 in its consumer mortgage lending fee schedule effective September 2026, which is a reasonable reference point, though your own lender's figure is what counts and we confirm it in writing. A discharge fee is not an exit fee: exit fees on variable rate contracts entered into after 1 July 2011 are banned under Australian consumer credit law. If your loan predates July 2011, check the contract. If you are inside a fixed term, breaking early triggers a break cost, calculated on the difference between your fixed rate and the current wholesale rate for the remaining term. Break costs can run into the thousands or tens of thousands, so we get a written quote from your lender before recommending anything.
2. Setting up at the new lender
Expect an application or settlement fee of $150 to $750, document processing of $100 to $600 where it applies, a valuation of $100 to $300 which is often waived as a competitive incentive, and state government mortgage registration and discharge fees. Baseline entry costs usually land between $500 and $1,500. Cashback offers for refinancers come and go, and when they are running they can cover entry costs entirely. We check what is live at the time you apply rather than quoting you a figure from last quarter. The one to watch is LMI: it is not transferable between lenders, so if your LVR is still above 80% you may pay it again, and at 1% to 5% of the loan amount it can erase the entire rate saving.
3. The break-even point
Divide the total cost of switching by the monthly saving and you get the month the refinance starts paying you. This is the single number that decides whether a refinance is worth doing, and it is almost always sooner than people expect. The table below works it out on the NSW average loan at three realistic cost levels. We run the same calculation on your actual balance and your actual quoted costs before recommending anything.
How many months until a refinance pays for itself?
Same $842,000 NSW average loan. Three cost scenarios: the unavoidable NSW title fees on their own, then with a typical major-bank discharge fee added, then with a full application fee on top as well.
Break-even period in months for refinancing an $842,000 NSW home loan at three switching cost levels
Rate cut
Saving per month
NSW title fees only ($365)
Plus $350 discharge fee ($715)
Plus $600 application fee ($1,315)
0.25%
$136
2.7 months
5.2 months
9.6 months
0.50%
$271
1.3 months
2.6 months
4.8 months
0.75%
$405
0.9 months
1.8 months
3.3 months
1.00%
$536
0.7 months
1.3 months
2.5 months
How this table was built, September 2026. Balance $842,000 and starting rate 6.3%, sources as above. Title fees are $365.46, being a discharge of mortgage at $182.73 and a mortgage registration at $182.73, both including GST, from the NSW Land Registry Services 2026/27 fee schedule effective 1 July 2026. The $350 discharge fee and $600 application fee are Commonwealth Bank's published figures from its consumer mortgage lending fee schedule effective September 2026, used here as a widely applicable reference point rather than a claim about your lender. Break-even is total cost divided by monthly saving. This excludes fixed rate break costs and any new LMI, which are the two items that can change the answer completely.
The headline is that on a loan this size, even a quarter point improvement clears its own costs inside a year in every scenario above. The reason people still lose money refinancing is not the switching fees. It is resetting a 22 year remaining term back to 30 years, paying LMI a second time, or breaking a fixed rate without getting the break cost quoted first. We check all three before recommending anything.
Four to eight weeks from application to settlement is normal for an external refinance. Low LVR applications with clean documents can settle in two to three weeks. Complex files can stretch past ten weeks.
Here is where the time actually goes, so you can see what is worth chasing and what is not.
Typical refinancing timeline from application to settlement
Stage
Typical time
What holds it up
Rate review and lender selection
1 to 3 days
Waiting on your current loan statements
Document collection and lodgement
3 to 7 days
Missing payslips, statements or identification
Lender assessment and valuation
1 to 3 weeks
Physical valuation bookings and lender backlogs
Formal approval and loan documents
3 to 7 days
Signing and returning documents late
Settlement and discharge of old loan
1 to 2 weeks
Your outgoing lender processing the discharge authority
The stage nobody warns you about is the last one. Your outgoing lender has no reason to hurry, and a discharge authority that sits in a queue can add two weeks on its own. We lodge the discharge request in parallel with the new application rather than waiting for approval, which is the single biggest thing that keeps a refinance on schedule.
The Process
How refinancing works, step by step
The paperwork is broadly the same as a new home loan application, but with fewer unknowns. The property exists, you have a repayment history, and you have done this before. Here is what happens after you get in touch.
1
Step 1: Free rate review and comparison
We take your current lender, rate, balance, term, features and goals, then compare against our panel of 50+ lenders factoring in your LVR, income type and property location. Takes about 20 minutes and costs nothing. You come out of it knowing whether you are well placed where you are, or how much you are leaving on the table.
2
Step 2: Cost benefit analysis and lender matching
We model the saving from the new rate, the one-off costs of switching, the break-even month, and the net benefit over how long you plan to hold the loan. If you are fixed, we get the break cost. If your equity is near 80%, we confirm the current valuation to check whether LMI applies. Then we pick the lender whose credit policy and valuation approach fit your file, which is not always the one with the lowest advertised rate.
3
Step 3: Application and documentation
We prepare and lodge the application. Payslips or income evidence, three to six months of bank statements, current home loan statements, rates notice, identification, and details of other debts. Self-employed files add two years of tax returns and business financials. We review everything before submission, because a clean file is the difference between six weeks and ten.
4
Step 4: Valuation, assessment and formal approval
The new lender values the property, either from comparable sales data or with a physical inspection, and confirms your LVR. They then assess income, expenses and credit. This is the longest stage, usually one to three weeks. We stay on the assessor and clear any conditions the same day they are raised.
5
Step 5: Settlement and discharge
The new lender pays out the old loan, the old mortgage comes off your title, the new one goes on, and your new repayment schedule starts. We coordinate both lenders, confirm the discharge is registered, and send you a final summary of your new rate, repayment and settlement costs.
Types
Types of refinancing: which one fits your situation?
Five refinancing structures. Working with a refinance broker matters most here, because the right structure is often worth more than the last 0.1% on the rate.
Rate and term refinance
The simple one. You swap your existing loan for a new one at a lower rate, a shorter term, or both, without borrowing anything extra. The balance stays the same and the goal is purely to reduce the repayment or the total interest. This is the right move when you do not need additional funds and you just want the loan priced properly.
Cash out refinance and equity release
You refinance to a larger loan and take the difference as cash. That cash is the equity you have built through repayments and through growth in the property's value. Most lenders cap total borrowing at 80% of the current value. Funds can go towards renovations, an investment property deposit, debt consolidation or another major expense, and the lender will ask which. We assess whether the purpose and the extra debt stack up before recommending it. More on the equity release options page.
Debt consolidation refinance
You fold credit cards, personal loans and car loans into the home loan so everything is repaid at the home loan rate. Monthly cash flow improves immediately and you go from five payments to one. The thing to watch is that a short-term debt spread across 25 years can cost more in total interest even at the lower rate, so we model it properly and, where it makes sense, structure the loan so the consolidated portion is cleared quickly rather than dragged out.
Fixed to variable, or variable to fixed
Sometimes the point is not a lower rate but a different kind of loan. With the cash rate on hold at 4.35% and further increases still on the table according to some forecasters, budget certainty has value, and fixing part of the loan delivers it. Coming off a fixed rate and wanting an offset account and unlimited extra repayments pushes the other way. A split loan gives you some of each. We advise on this based on your balance, remaining term, repayment goals and how much rate movement you can absorb.
Investment property refinance
Same principles, different assessment. Investment loans price higher than owner-occupier loans, and lenders vary widely in how much rental income they will count, which changes your borrowing capacity a lot. Serviceability is measured across your total debt, not one property at a time. Investors commonly use a cash out refinance on an existing property to fund the deposit on the next one. We work with single-property investors through to multi-property portfolios and match them to lenders whose investment policy supports the plan.
When not to refinance
When refinancing does not make sense
We only recommend a switch when the numbers support it. These are the five situations where they often do not.
1
Your LVR is above 80%: A fresh LMI premium at the new lender can add 1% to 5% of the loan amount, which usually swallows the rate saving whole. LMI is not transferable. We check your LVR against a current valuation before recommending anything, and sometimes the answer is to wait for growth or pay the balance down first.
2
The break cost on your fixed loan is too high: Break costs are largest when wholesale rates have moved against your fixed rate. If the saving will not recover the break cost inside your holding period, waiting for the fixed term to expire is the better play. We get the written quote and do the arithmetic before you commit.
3
Your balance is small or nearly repaid: A rate cut on a small balance produces a small dollar saving, and the fixed costs of switching do not shrink to match. If you are within a few years of paying the loan out, the effort rarely pays for itself. We will model it and tell you honestly.
4
You are selling within 12 months: A short holding period usually means you never reach break-even. It can still work if the saving is large and the costs are low, so it is worth running the numbers rather than assuming, but the default answer is no.
5
Your financial position has recently weakened: A drop in income, a jump in debts, or missed repayments on your credit file will narrow your options to less competitive lenders, or knock the application back entirely. We assess this before lodging anything, because a declined application leaves an enquiry on your file that makes the next attempt harder.
Location
A refinance broker for the Hills District and greater Sydney
RyRo Loan Centre is based in Norwest, in Sydney's Hills District. Most of our refinancing clients are within a 20 minute drive, and we know which lenders value property in these suburbs accurately and which ones come in conservative, which matters enormously when you are trying to get under 80% LVR or release equity.
Parramatta and Western Sydney: Parramatta, Westmead, Merrylands, Guildford, Auburn, Granville, Blacktown, Seven Hills, Toongabbie, Penrith.
Northwest Sydney: Schofields, Box Hill, Marsden Park, Riverstone, Gables, Tallawong, Windsor.
Inner West and beyond: Strathfield, Burwood, Concord, Homebush, Lidcombe, Rhodes, plus clients across the rest of greater Sydney and interstate.
If you are in the Hills District and have owned your home for two or more years, the gap between your rate and the sharp end of the market has almost certainly widened. Whether that gap is a quarter of a point or a full point depends entirely on your rate, your LVR and your lender, and we will not guess at it before we have seen your loan. It costs nothing to find out.
Free Tools
Free calculators to check your refinancing position
Three reads that cover the numbers most people get wrong: what the switch actually costs, when it is worth doing, and whether a cashback offer is real money or a trap.
Your current lender has exactly one interest in your refinance: keeping you. We have access to 50+ lenders including the majors, second-tier banks, credit unions, non-banks and digital-only lenders. In the current market some of the sharpest refinance pricing sits well outside the big four, with lenders most borrowers have never heard of.
2
We do the numbers honestly
We do not recommend a switch that does not stack up. We cost the discharge fee, the entry fees, the break cost if you are fixed, the LMI risk if your equity is near 80%, and the break-even month. If the answer is that you should stay put and come back in a year, that is what we will tell you.
3
We manage both sides, not just the application
Refinancing means dealing with an outgoing lender who has no reason to make leaving easy and an incoming lender with their own hoops. We prepare the application, coordinate the valuation, chase formal approval, lodge the discharge and confirm settlement. You deal with us, not with two banks at once.
4
We know the Hills District market
We know which lenders value homes in Castle Hill, Kellyville, Bella Vista and Rouse Hill accurately and which come in low, which estates get conservative valuations, and how that plays into your LVR. For anyone releasing equity, the valuation is the whole ballgame.
5
$0 broker fees on residential home loans
Our service costs you nothing for a residential refinance. We are paid a commission by the lender when the loan settles. No broker fee, no consultation fee, no application preparation fee. We work under the best interests duty in the National Consumer Credit Protection Act, which applies to every recommendation we make.
What our clients say about refinancing with RyRo
More than 2,500 Australians have trusted RyRo Loan Centre with their home loans. Plenty come to us specifically to refinance after years with their original lender, and the most common reaction is surprise at how much they had been overpaying.
5.0 out of 5, based on 359+ verified Google Reviews.
What Our Customers Say
5 out of 5
Based on 359+ verified Google Reviews.
Vandhana Naidu
"We can't thank Sumit enough for helping us secure our first home - especially in such a tough and competitive market. He truly went above an…"
Usually yes, for two reasons. A refinance broker compares the whole market instead of one bank's product shelf, and a broker knows which lenders are pricing sharply for refinancers right now rather than which ones advertise loudest. On the $842,000 NSW average owner-occupier loan, cutting your rate by half a percentage point off the 6.3% average saves about $271 a month, and a full point saves about $536. Our service also costs you nothing, so the only thing you spend is the 20 minutes it takes us to review your current loan and tell you where you stand. Loan size from ABS Lending Indicators June quarter 2026, average rate from RBA Table F6.
No. RyRo charges you $0 to refinance. We are paid a commission by the lender once your loan settles, and that commission is not added to your rate or your loan amount. You get the same rate through us that you would get going direct, with the difference that we have already compared 50+ lenders to find it. We are also bound by the best interests duty under the National Consumer Credit Protection Act, which legally requires us to recommend the option that is best for you, not the one that pays us the most.
The common triggers are a fixed rate about to expire, a loan that has not been reviewed in two or more years, a property that has grown enough in value to push your LVR below 80%, or a change in your income or goals. The RBA raised the cash rate three times between February and May 2026 to 4.35% and has held it there since, with the next decision on 29 September 2026. This is not a market where waiting is rewarded. One thing that has changed in your favour: because wholesale rates rose through 2026, break costs for people who fixed before this year are often small or nil, so a fixed loan is worth testing rather than assuming you are locked in. A free 20 minute review tells you either way.
2
Cost, timing and paperwork
A standard external refinance at 80% LVR or below, with no LMI and no fixed rate break cost, usually lands between $500 and $2,000 all up. That covers the discharge fee from your current lender (commonly $150 to $500), an application or settlement fee at the new lender ($150 to $750), a valuation ($100 to $300, often waived), and NSW government title fees. In NSW those title fees are fixed and knowable: $182.73 including GST to discharge the old mortgage and $182.73 to register the new one, so $365.46 total under the 2026/27 NSW Land Registry Services schedule. Break costs on a fixed loan and a fresh LMI premium above 80% LVR are the two things that can blow the budget out, so we check both before recommending anything. On the $842,000 NSW average loan, even a 0.25 percentage point rate cut clears $1,315 of switching costs in under ten months.
Four to eight weeks is typical for an external refinance, measured from the day the application is submitted to settlement. Roughly one week goes to preparing and lodging documents, one to three weeks to lender assessment and valuation, one week to formal approval and loan documents, and one to two weeks to settlement and discharge of the old mortgage. Some lenders run fast refinance products for low LVR applications that settle inside two weeks. The biggest cause of delay is missing paperwork, which is why we check the file before it is lodged.
For a PAYG application: your last two or three payslips, three to six months of transaction account statements, six months of statements on your current home loan, your most recent council rates notice, photo identification, and statements for any other debts including credit cards and car loans. If you are self employed, add two years of personal and business tax returns plus financial statements. We send you a checklist tailored to the specific lender we are applying to and review the whole file before it is lodged.
3
LMI, equity, fixed rates and credit
Only if your loan is still above 80% of what the property is worth today. LMI is not transferable between lenders, so a fresh premium applies at the new lender if your LVR is above 80%, and it can add 1% to 5% of the loan amount, which usually wipes out the rate saving. The good news for most Sydney owners is that property growth has already done the work. If you bought in the Hills District several years ago, your LVR has probably fallen under 80% on its own. We confirm the current valuation first.
Yes, that is a cash out refinance. Most lenders let you borrow up to 80% of the current property value, and the gap between that ceiling and your current balance is your usable equity. On a Castle Hill home worth $1,500,000 with $600,000 owing, 80% is $1,200,000, so up to $600,000 could be released. Lenders will ask what the money is for and will assess your ability to service the larger loan. Renovations, an investment property deposit and debt consolidation are the three most common uses.
Yes, but breaking a fixed term early triggers a break cost, and it can run from a few hundred dollars to tens of thousands depending on your balance, how long is left on the fixed term, and how wholesale rates have moved since you fixed. Ask your lender for a written break cost quote before you commit to anything, because the quote is usually only valid for a day or two. In most cases the smarter move is to start the process six to twelve months out so the new loan settles the week your fixed term ends.
Often yes, but the lender list gets shorter and the rate gets higher. Mainstream lenders want a clean file with no defaults, judgements or recent missed repayments. If your file has marks on it, specialist and non conforming lenders on our panel will still look at the application, usually at a higher rate and a lower maximum LVR. We check your position first and only apply where approval is realistic, because every declined application leaves an enquiry on your credit file and makes the next one harder.
Not sure which one you need? Book a free strategy call or contact our Norwest office. No obligation, and reviewing your loan does not involve us lodging a credit application. A lender may make a credit enquiry later, once you have seen your options and given consent to proceed.
In-depth guides
Related guides from RyRo Loan Centre
Refinance reads to help you choose the right rate, structure and lender for the next 5 years.
Find out if your home loan rate is still competitive
Reviewing your loan takes 20 minutes and costs you nothing. The RBA raised rates three times in 2026 and meets again on 29 September, so the gap between what you are paying and what is available is worth checking. RyRo Loan Centre compares 50+ lenders and manages the whole switch on your behalf, at no cost to you.
“Don't wait for your rate to become a problem. Find out where you stand now.”
Sumit · Director & Senior Loan Specialist
Meet the team
Rohan
Asset Finance
Helping clients secure the right equipment and vehicle finance.
Kathryn
Settlement Liaison
Keeping your settlement on track from application to keys.
5.0/5 Rating359+ Reviews
13+ YearsTrusted Professionals
100% SatisfactionProven results for 2500+ clients
50+Lenders
FastPre-approval
$0Broker Fees
Get Started
Free strategy call - no obligation
Leave your details and we'll call you to run through your current rate, your options and your savings potential.
No Credit Check100% Obligation-Free
Join thousands of clientsWe generally respond within an hour
By submitting, you agree to our privacy policy and terms of service.