RyRo Loan Centre

Trust and company loan broker, Sydney

Trust & Company Property Loans: Asset Protection Meets Smarter Structure

Buying in a family trust or company name? Most banks don't make it easy. We match your structure to lenders that fund it, and work alongside your accountant and solicitor.

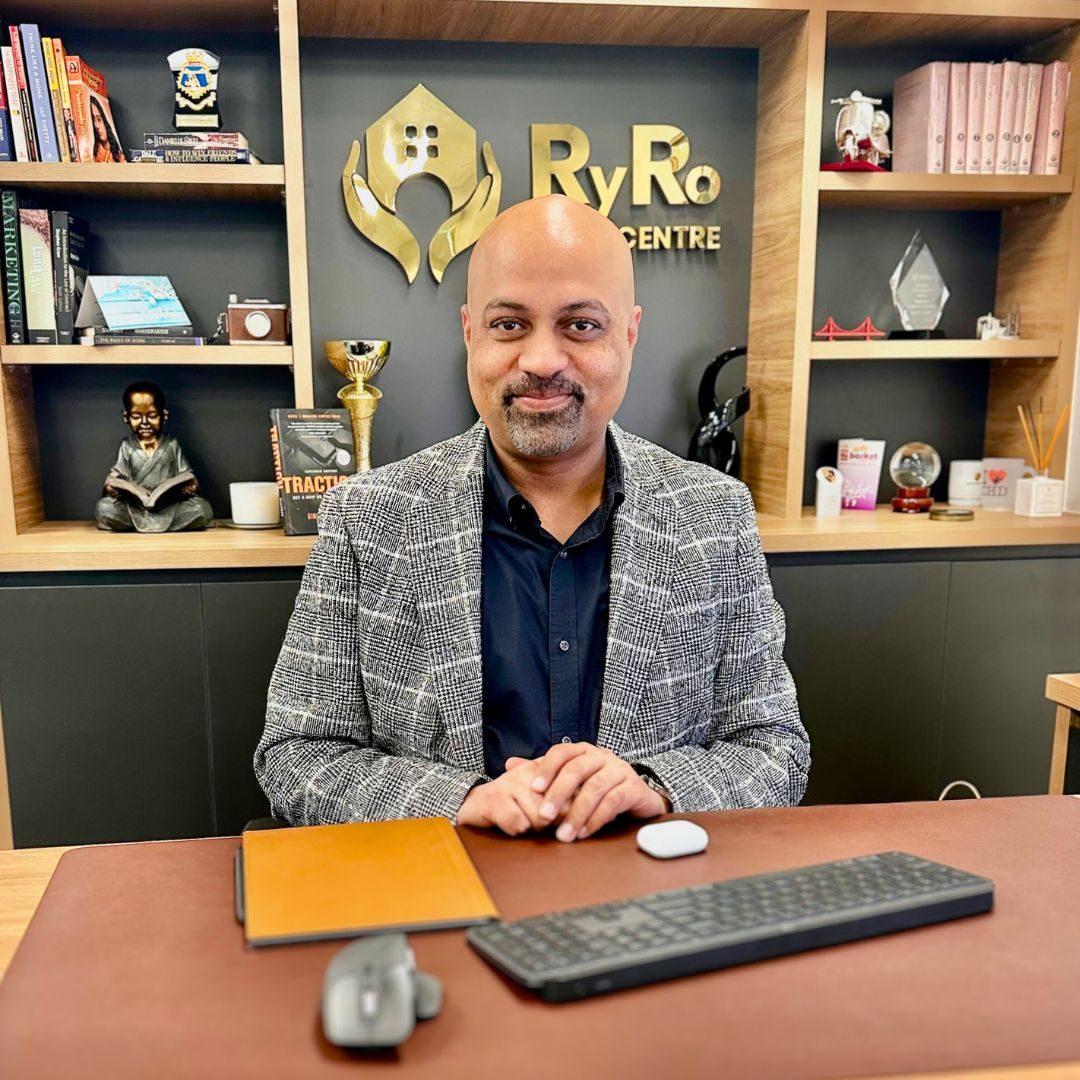
Sumit Joshi, principal broker at RyRo Loan Centre

Book your free trust loan assessment

Tell us your structure and we'll match you to lenders who understand it.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Lenders matched to your trust deed and trustee
  • Compared across 50+ lenders
  • Based in Norwest, Sydney. $0 broker fees
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Trust & company property finance, updated November 2026

Why Borrowing in a Trust or Company Requires a Specialist Broker

Buying property in a family trust or company name is a common way to plan for asset protection, tax flexibility and passing wealth to the next generation. Getting it funded is the hard part.

Most lenders either don't offer trust or company loans at all, or apply them so rigidly that the application collapses on a technicality: the wrong trustee structure, a missed schedule in the trust deed, or a lender policy that doesn't accommodate corporate trustees.

We work with lenders who deal with these structures regularly, know what documentation is required, and can fund them efficiently. We also work alongside your accountant and solicitor so the loan supports your broader plan, not just the purchase. Read our guide to buying property in a trust for the background.

What a well-run trust structure does for you

Done well, a trust or company structure can give years of flexibility in how income is distributed, keep property assets separate from personal liability, and give your accountant a structure to plan distributions with each year. Whether it suits you is a question for your accountant. Our job is making sure the structure you choose can be funded, at competitive pricing, by a lender that understands it.

50+

Lenders compared including trust loan specialists

$0

Broker fees: paid by the lender

360+

Google reviews, rated 5.0

From a client with a complex loan structure, on Google

Kesan Ramamoorthy

4 years ago on Google

Google

Simply Awesome! RyRo made my home loan refinance look very easy but I know having a complex loan structure, it's a very difficult job to do. So thank you Sumit for all your help and constant updates throughout the loan process.

Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan Centre · any loan, any entity, every step until settlement

The short answer

Can you get a home loan in a trust?

Quick answer

Trust home loans, in one paragraph

Yes. A family trust, unit trust or company can borrow to buy property, but fewer lenders offer it and each sets its own rules. Expect the lender to review the trust deed, check the trustee has the power to borrow and mortgage, and ask the people behind the trust to guarantee the loan. Most lenders treat it as investment lending.

Living in a home your trust owns is possible with some lenders, on stricter terms. Tell us the purpose of the purchase upfront and we will only approach lenders whose policy fits it. If you are buying in your own name instead, see our investment property loans.

Hands signing loan paperwork at a desk
The trustee signs for the trust. The people behind it usually sign guarantees too.Photo: Scott Graham / Unsplash
  • The deed gets read

    The lender, and often its solicitors, check the deed allows borrowing and mortgaging.
  • People sign guarantees

    Trustees, directors or main beneficiaries usually guarantee the loan.

Structures explained

Trust vs Company: Understanding Your Structure

The structure you use to hold property has significant consequences for tax, asset protection, and finance access. Here's how the main structures compare.

  • Discretionary (Family) Trust

    The trustee holds legal title and decides each year how income is distributed. The structure families use most for property.

    Key points
    • Trustee (individual or corporate) holds legal title; beneficiaries receive income distributions
    • Income can be distributed to different family members each year, as your accountant advises
    • Assets may be protected from beneficiaries' personal creditors, depending on how the trust is set up
    • Capital gains are taxed differently from property in your own name: get advice on hold periods and distributions
    • The most commonly used structure for family property investment
  • Unit Trust

    Beneficiaries hold fixed units, so income and capital follow unit holdings. Often used when unrelated parties co-invest.

    Key points
    • Beneficiaries hold fixed units, not discretionary like a family trust
    • Income and capital distributed in proportion to unit holdings
    • Often used when multiple unrelated parties co-invest in property
    • Transferring units has its own duty and tax rules: ask your accountant
    • Fewer lenders take unit trusts than discretionary trusts
  • Company Purchase

    The company holds title in its own right. Directors usually guarantee the loan, so their own finances still count.

    Key points
    • Company holds legal title to property in its own right
    • Liability sits with the company, but directors who give personal guarantees are liable under them
    • Companies pay company tax on gains and are taxed differently from individuals: speak to your accountant
    • Useful for business owners who want to separate investment property from personal assets
    • Accepted by specialist lenders with personal director guarantees
  • Corporate Trustee Structure

    A company acts as trustee of a discretionary trust. More set-up and upkeep, and accepted by fewer lenders.

    Key points
    • A company acts as trustee of a discretionary trust, often chosen for asset protection
    • Combines trust income flexibility with a company as the legal owner
    • More complex to set up and maintain (company compliance, ASIC fees)
    • Often used by clients building a larger property portfolio
    • Accepted by specialist lenders who understand corporate trustee lending

Lender appetite

Which trust types do lenders accept?

Discretionary trusts are the easiest to fund. Unit, hybrid and corporate trustee structures narrow the list of lenders, and each lender sets its own rules.
The table is a general guide only. What matters is how your deed is written and who the trustee is, which is why we read the deed before we name a lender.

Drafting house plans with a pencil and scale ruler
Every lender reads the deed its own way. We read it first. Photo: Daniel McCullough / Unsplash
How lenders generally treat each trust or company structure
StructureLender choiceWhat lenders look at
Discretionary trust, individual trusteeWidest of the groupDeed powers, trustee guarantees
Discretionary trust, corporate trusteeFewer lendersDeed, company details, director guarantees
Unit trustFewer lendersWho holds the units, guarantees from unit holders
Hybrid trustSpecialist lendersA close review of the deed
CompanySpecialist lendersCompany finances, director guarantees

General guide only. Each lender sets its own structures, limits and pricing. SMSF bare trusts follow separate super rules.

4 key reasons

Why Clients Buy Property in a Trust or Company Structure

The reasons clients give us most often. Whether any of them apply to you depends on your situation, so treat this as general information and test it with your accountant.

  1. Asset protection

    Property held in a properly set up trust may be harder for a beneficiary's personal creditors to reach.

    Read the detail

    Property held in a properly structured trust may be protected from claims against individual beneficiaries, which matters for business owners, professionals and anyone with personal liability exposure. If a beneficiary faces personal insolvency or a legal judgment, trust assets are not automatically available to their creditors. How strong that protection is depends on the deed and the facts, so ask your solicitor.

  2. Tax flexibility

    A discretionary trust lets the trustee decide each year which beneficiaries receive the income.

    Read the detail

    A discretionary trust allows rental income to be distributed among beneficiaries each year, rather than being locked to a single taxpayer. In years when one beneficiary earns less (a spouse returning from parental leave, for example), your accountant may suggest a different distribution. There are rules on how this works and who it can go to, so the decisions sit with your accountant.

  3. Generational wealth transfer

    The trust can continue while the beneficiaries change, so property does not always have to be sold to pass it on.

    Read the detail

    Assets held in a family trust can sometimes stay in the trust as the next generation become the beneficiaries, rather than being sold or transferred. Whether that avoids tax or duty depends on your trust deed and how changes are made, which is advice for your accountant and solicitor. The trust continues; the beneficiaries change.

  4. Portfolio scalability

    Several investment properties held in one entity can make long-term planning simpler.

    Read the detail

    Holding multiple investment properties in a trust keeps them within a single legal entity, which can simplify estate planning and the paperwork of selling or transferring assets over time. For clients building a long-term portfolio, getting the structure right at the start avoids costly restructuring later. For portfolio lending in your own name, see investment property loans.

The trade-offs. Capital gains, land tax, losses and negative gearing can all work differently in a trust or company than in your own name. None of that makes a structure wrong for you; it means it should be modelled with your accountant before you buy. Reading: negative gearing explained.

Lender assessment

How Lenders Assess Trust and Company Loans

Trust and company loans follow a different approval process to individual borrowing. Here's what lenders generally look at.

  1. Step 1

    Trust deed review

    Lenders ask for a copy of the trust deed to confirm it permits borrowing and the trustee has authority to grant a mortgage over trust property. Some deeds contain borrowing restrictions or unusual trustee appointment clauses, issues we look for before application.

  2. Step 2

    Personal guarantees

    The people behind the trust or company usually provide personal guarantees. Where there is a corporate trustee, lenders typically ask the directors to guarantee. Lenders assess the guarantors' personal finances for serviceability.

  3. Step 3

    Serviceability

    Income from the trust (rent, distributions) and the guarantors' personal income are used to show the loan can be repaid. How lenders treat trust income versus personal income varies, and we know which lenders take a reasonable approach for your income structure.

  4. Step 4

    Lender policy on structures

    Some lenders only accept individual trustees. Others accept corporate trustees. Some will not lend to trusts at all. We know each lender's policy and don't waste your time or credit file on lenders who won't accommodate your structure.

  5. Step 5

    Purpose of purchase

    Most lenders treat trust and company loans as investment lending. Fewer will lend where you plan to live in a property the trust owns, and those that do apply stricter terms. We clarify this upfront.

Sumit · 3:07
Two ways to structure your first investment loanSumit Joshi, RyRo Loan Centre · how a loan is structured matters as much as the rate

Guarantees

Do I need a guarantor for a trust loan?

Usually, yes. Most lenders want the people behind a trust or company to personally guarantee the loan, because the entity itself often has few assets of its own.

Who has to sign depends on the lender and the structure. A guarantee means you can be personally liable if the trust or company cannot repay, so speak to your solicitor about what it means for you before you sign.

  • Individual trusteesWhere people are the trustee, they usually sign the loan and a guarantee.
  • Directors of a corporate trusteeLenders typically ask every director to guarantee.
  • Main beneficiaries or unit holdersSome lenders also ask the people who benefit from the trust.
  • Company directorsFor a company purchase, directors usually guarantee personally.
Close-up of a hand signing a printed contract with a pen
A guarantee makes you personally responsible for the loan. Read it with your solicitor.Photo: Jakub Żerdzicki / Unsplash

Get expert advice, free

Not sure your structure will get approved?

Tell us your structure, what you're buying and your goals, we'll identify the right lenders and approach.

“Trust loans fail because of deed issues or wrong lender selection, not because the client isn't creditworthy. We solve both problems before we submit anything.”Sumit Joshi JP, principal broker
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824

Guru Prasadh

3 years ago on Google

Google

Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

Guru Prasadh

Google3 years ago on Google

Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

Eligibility

Who Can Borrow in a Trust or Company Structure?

Borrowing in a trust or company name is available to a wide range of clients. The key requirements are below.

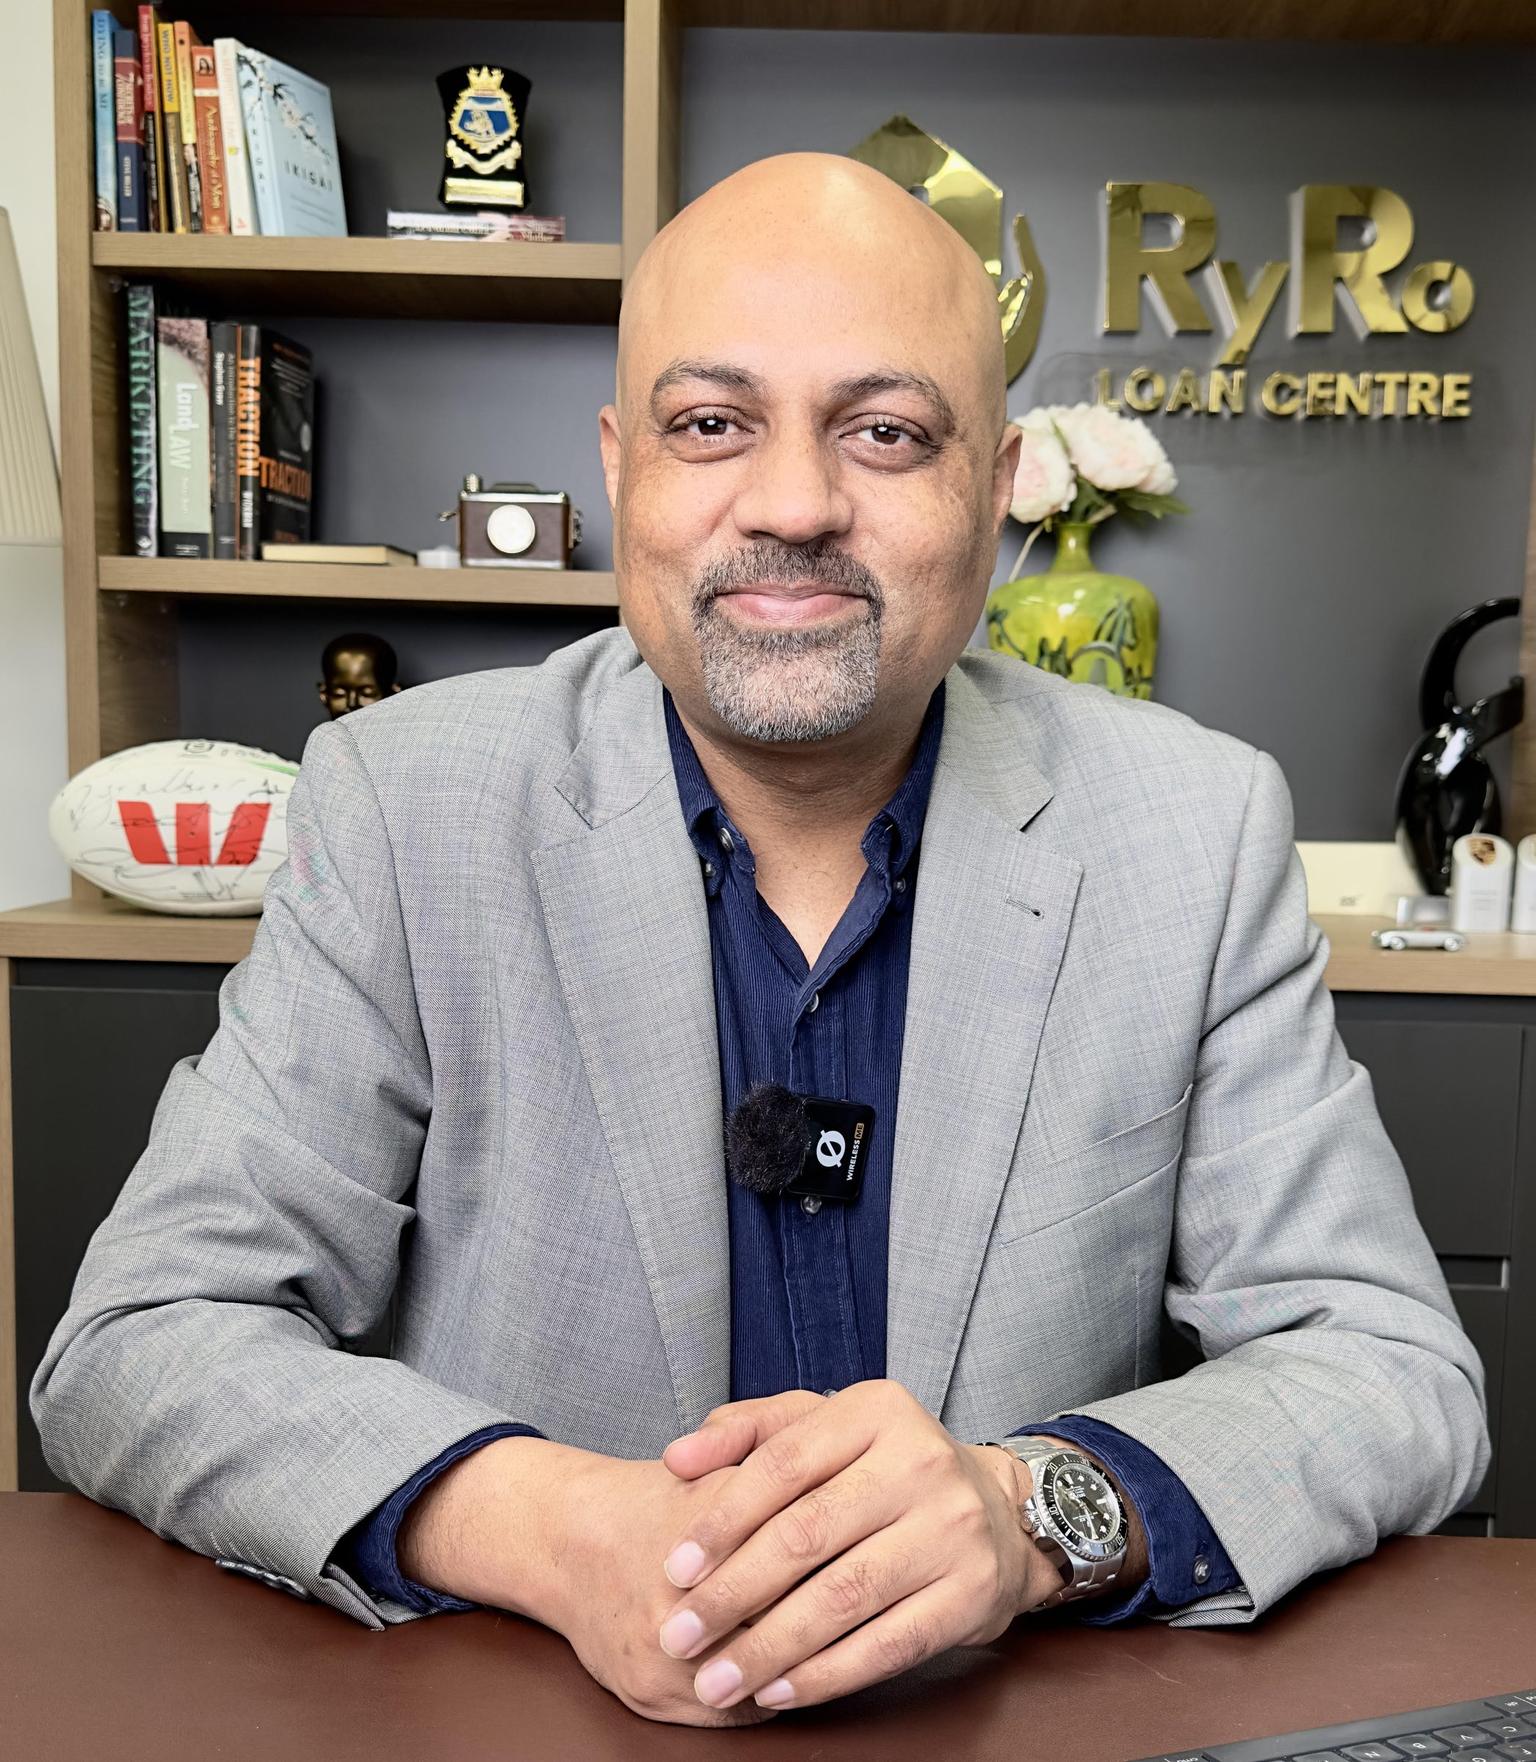
Sumit Joshi seated at his desk in the RyRo Loan Centre office
Sumit Joshi JPReads the trust deed before a lender sees it.
  • A properly established trust or company with appropriate documentationThe full deed and any variations, or the company constitution and ASIC extract.
  • A valid trust deed that permits borrowing and granting a mortgage over trust propertyIf the deed is silent or restrictive, it may need advice from your solicitor first.
  • Trustees or directors who can provide personal guarantees and show serviceabilityTheir own income, debts and credit history are part of the assessment.
  • A purpose the lender acceptsMost lenders treat trust and company loans as investment lending; fewer lend where you will live in the property.
  • Properties that qualify under the lender's investment property guidelinesStandard residential, commercial, or specialist asset classes, depending on the lender.
Free PDF · 2 pages
Photo: Clay Banks / Unsplash

Free 2-page guide

The Self-Employed Loan Document Checklist

Exactly what full doc and low doc lenders want to see, the substitutes when you cannot show two years of returns, and the add-backs that lift what you can borrow.

  • The full doc document set
  • Low doc substitutes: BAS, bank statements, accountant letter
  • Income add-backs to ask your accountant about

Google5.0 from 360+ Google reviews · Emailed to you straight away

4 ways we add value

How RyRo Loan Centre Helps With Trust and Company Loans

  • We know which lenders accept your structure

    We approach only lenders whose policy fits your trust or company, protecting your credit file.

    Read the detail

    There is no point approaching lenders who don't accept trusts or who only accept individual (not corporate) trustees. We know each lender's policy and approach only the right ones, protecting your credit file and saving weeks of wasted effort.

  • We review your trust deed before application

    Restrictive borrowing clauses or unclear trustee appointments cause declines. We look for them first.

    Read the detail

    Common trust deed issues, such as restrictive borrowing clauses, unclear trustee appointment or narrow definitions of permitted investments, can cause lender declines. We review the deed with you before submission and flag anything your solicitor may need to amend or explain to the lender's legal team.

  • We structure the loan to suit the trust's income and purpose

    Trust, rental and personal income presented the way each lender assesses it.

    Read the detail

    Trust income, rental income and trustee personal income need to be presented clearly and in a way that matches the lender's serviceability framework. We know how each lender treats each income type and structure the application accordingly.

  • We work alongside your accountant and solicitor

    The loan has to fit your tax and estate plans, so we keep your advisers in the loop.

    Read the detail

    A trust loan touches tax, estate planning and legal structure. We don't operate in isolation: we work alongside your advisory team so the loan structure supports your broader financial goals and doesn't create unintended tax or legal consequences.

How a trust loan works with RyRo

  1. Step 1

    Tell us the structure and the plan

    A free call about the trust or company, who the trustee is, what you are buying and why.

  2. Step 2

    Send us the deed

    We read the trust deed and company details for anything a lender will question.

  3. Step 3

    We shortlist lenders

    We compare 50+ lenders against your structure, guarantors, deposit and purpose.

  4. Step 4

    We package the file

    Entity documents and every guarantor's paperwork checked before it goes in.

  5. Step 5

    Approval and settlement

    Kathryn tracks the valuation, approval and settlement paperwork until it is done.

Start with a free call

Sumit reads your details and calls you back.

Situations we solve

Trust and company situations we help with

The structures we see most often, and what we do about each.

  • Your family trust wants an investment property

    The trust is set up, the accountant is on board, and you need a lender that will take the deed.

    How we handle it

    We read the deed, confirm who must guarantee and shortlist the lenders whose policy fits, before you make an offer.

  • You have a corporate trustee

    A company acts as trustee, which knocks out some lenders straight away.

    How we handle it

    We go only to lenders that accept corporate trustees, and package the company details and director guarantees together.

  • Your business wants to buy property

    You want the company, not you personally, to hold a property.

    How we handle it

    We check whether a residential or a commercial loan fits the purchase. For premises your business will use, see commercial property loans.

  • You were weighing an SMSF against a trust

    New residential SMSF borrowing ended on 10 August 2026, so you are looking at other structures.

    How we handle it

    A family trust is outside super, so super rules do not apply to it. Your accountant decides which suits you; we fund it. See SMSF loans for what is still possible in super.

  • You are self-employed and paid through a trust

    Your income flows through a trust or company, so no single document shows what you earn.

    How we handle it

    We work out which entity and personal documents a lender needs to see the full picture. See low doc loans if your returns are not lodged yet.

  • Your trust already has a loan

    The trust borrowed years ago and the pricing or structure no longer suits it.

    How we handle it

    A trust can refinance to a lender that accepts its structure. We check the costs of switching and who must guarantee again.

Why RyRo

Why Clients Choose RyRo Loan Centre for Trust Loans

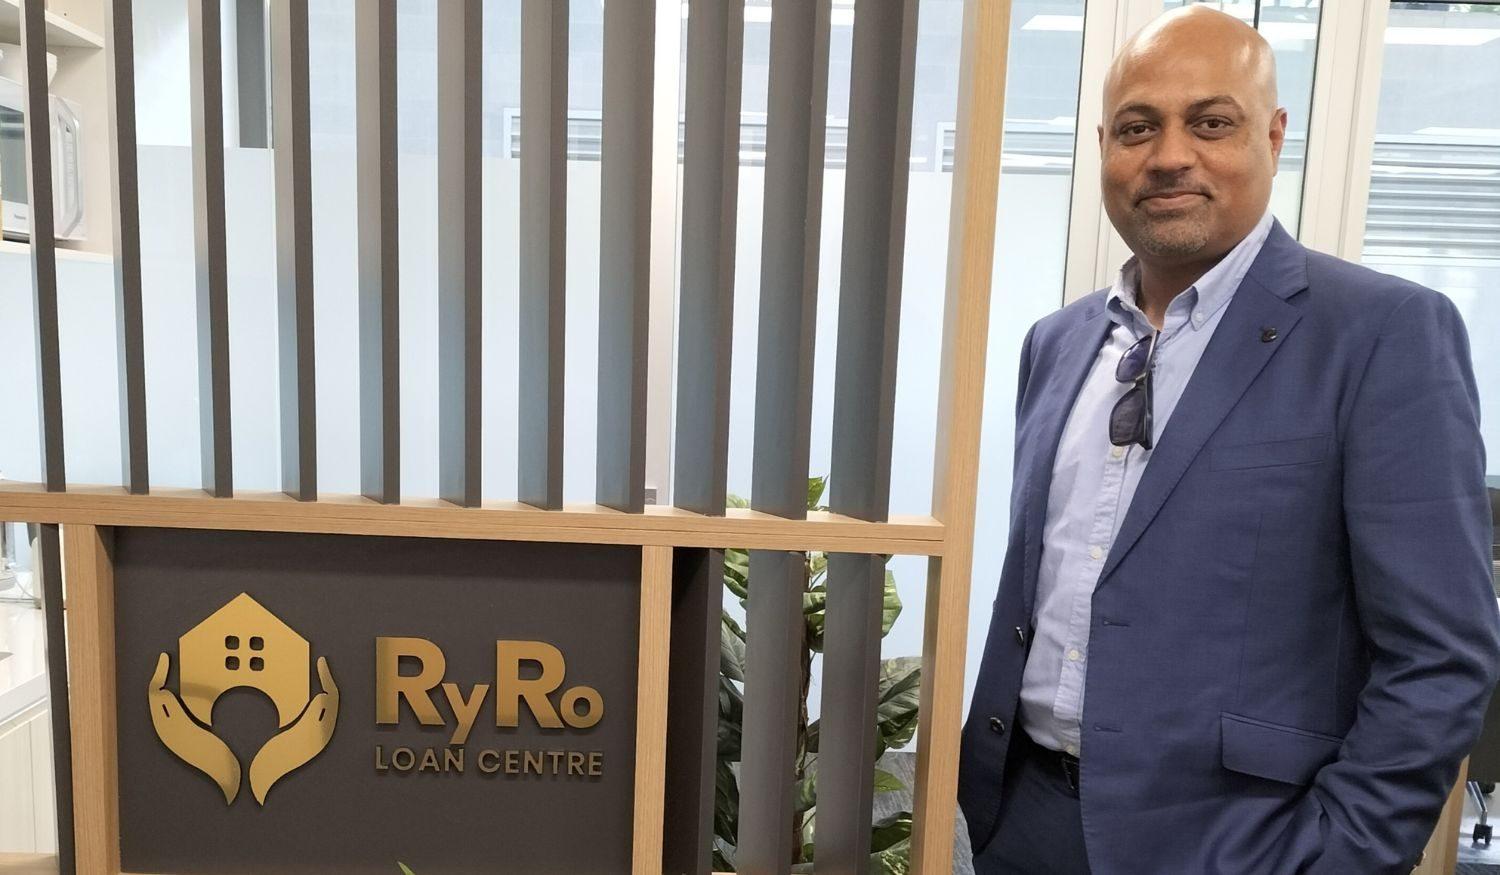
Sumit Joshi, principal mortgage broker at RyRo Loan Centre, in a blue suit at the Norwest office
Sumit Joshi JPPrincipal broker, Credit Rep 446824
Kathryn Thomas, loan processor at RyRo Loan Centre
Kathryn ThomasLoan processor
  • 13+ years

    Specialist lending experience across complex structures.

  • 50+ lenders

    Full market access including trust-specialist lenders.

  • $0

    Broker fees, we're paid by the lender.

  • 360+ reviews

    Rated 5.0 on Google by real clients.

Sumit · 1:18
Cheaper rate or the right strategy?Sumit Joshi, RyRo Loan Centre · cheaper rate or the right strategy

Google reviews

What Our Customers Say

Rated 5.0 out of 5 from 360+ Google reviews. These clients came to us with complex structures, several loans at once, SMSF purchases and growing portfolios. Quoted word for word. Read all 360+ Google reviews.

Google

5.0

From 360+ Google reviews

Sumit · 2:59
From two properties to four in six monthsSumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • Cherrie Sandford

    5 years ago on Google

    Google

    Sumit is extremely professional, supportive and respectful in his business dealings. He went to great lengths to get several simultananeous home loans for me that were extremely complex in nature. He always returned my calls and emails in an efficient timely manner even though contacting me and my husband who works regionally was so difficult. As a woman doing business, he treated me so kindly and I never felt I asked him a silly question, though I'm sure I did. I always felt he would never ever let me down. I HIGHLY recommend Ry Ro loan centre and I would never do business elsewhere now that I've experienced his business services.

    Cherrie Sandford

    Google5 years ago on Google

    Sumit is extremely professional, supportive and respectful in his business dealings. He went to great lengths to get several simultananeous home loans for me that were extremely complex in nature. He always returned my calls and emails in an efficient timely manner even though contacting me and my husband who works regionally was so difficult. As a woman doing business, he treated me so kindly and I never felt I asked him a silly question, though I'm sure I did. I always felt he would never ever let me down. I HIGHLY recommend Ry Ro loan centre and I would never do business elsewhere now that I've experienced his business services.

  • Param Singh

    4 years ago on Google

    Google

    Exceptional service, best with complex loan needs. Highly recommend for any loan service. Sumit is extremely supportive, very prompt and provides you the with the best solution for your finances and investments!! Highly recommended!!

  • Anshuman Bhardwaj

    2 years ago on Google

    Google

    Brilliant team and very responsive I am taking help of Sumit and his team for almost 10 years now from my first home to my 6th investment property . He is very helpful, ,informative and respectful to all my questions and needs. Always available and his Team (Dean) also is very knowledgeable . I have recommended them to lot of my friends and also heard good about them. Thanks team and keep up the good work

    Anshuman Bhardwaj

    Google2 years ago on Google

    Brilliant team and very responsive I am taking help of Sumit and his team for almost 10 years now from my first home to my 6th investment property . He is very helpful, ,informative and respectful to all my questions and needs. Always available and his Team (Dean) also is very knowledgeable . I have recommended them to lot of my friends and also heard good about them. Thanks team and keep up the good work

  • bela chauhan

    10 months ago on Google

    Google

    I had the pleasure of working with Sumit and team for both my SMSF loan and a personal home loan, and I couldn’t be happier with the service. These can be complex processes, especially the SMSF loan, but he made everything feel clear and manageable from the very beginning. What really stood out was how organised and proactive he was constantly keeping me updated and making sure everything stayed on track. Both loans went through smoothly, and I genuinely felt supported the whole way. If you’re looking for someone knowledgeable, reliable, and easy to work with, I would highly recommend Sumit Joshi. Best Wishes 😊

    bela chauhan

    Google10 months ago on Google

    I had the pleasure of working with Sumit and team for both my SMSF loan and a personal home loan, and I couldn’t be happier with the service. These can be complex processes, especially the SMSF loan, but he made everything feel clear and manageable from the very beginning. What really stood out was how organised and proactive he was constantly keeping me updated and making sure everything stayed on track. Both loans went through smoothly, and I genuinely felt supported the whole way. If you’re looking for someone knowledgeable, reliable, and easy to work with, I would highly recommend Sumit Joshi. Best Wishes 😊

Free tools

Calculators for trust and company borrowers

Start with an indicative borrowing figure for the guarantors, then run the costs. None of these asks for your details to show a result.

Get an indicative borrowing figure

Enter the income of the people who will guarantee the loan. It is a starting point: trust lenders apply their own rules to trust and rental income, which we check against your documents.
Open the full borrowing power calculator
Who is applying?
a year
a month
% a year
More details(optional, 3)
a month

Your indicative range

You could borrow around

$489,000 to $541,000

Lower figure: stricter assumptions. Higher: more generous ones.

Rate the loan is tested at
9.00% a year
Repayment at your 6% rate
$2,933 to $3,246 a month
How we worked it out
Income after tax
$6,457 a month
Living expenses used
$2,100 to $2,520 a month
Debts and card limits
$0 a month

A range, not a single figure, because every lender assesses this differently. The lower number uses stricter assumptions and the higher one more generous ones. No lender has approved it.

Assumptions and sources
AssumptionStricterMore generous
Bonus and overtime counted50%80%
Rental income counted70%80%
Card limit as a monthly repayment3.8%3%
Living cost benchmark$2,520/mth$2,100/mth
Debt-to-income cap6x incomeNone
Rate buffer+3 points+3 points
  • Tax uses the ATO 2026-27 resident rates, the low income tax offset, the 2% Medicare levy and HECS or HELP repayments. Each applicant is taxed as a single person.
  • Living costs are the greater of what you enter and the benchmark. Lenders use the Household Expenditure Measure, which is not public, so the benchmark is our conservative stand-in.
  • The loan is 30 years, principal and interest, tested at your rate plus the APRA buffer of 3 percentage points. Rental income has no deductions taken off. Fees, stamp duty and your deposit are not included.
  • Estimate only, not a loan offer or financial advice. Each lender uses its own servicing calculator and policy, so your real figure can sit outside this range.

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

Selling a property to restructure? Estimate your property selling costs.

FAQs

Trust & Company Loan FAQs

More questions? View all FAQs or ask us directly.

General information only, not tax or legal advice. Speak to your accountant or solicitor about your structure.

Can a trust or company borrow?

Can I get a home loan in a family trust name in Australia?

+
Yes, but it is more involved than borrowing in your own name. Not every lender offers trust loans, and those that do have their own rules on reviewing the trust deed, the trustee structure and personal guarantees. The trustee, whether an individual or a company, usually signs the loan and the people behind it are usually assessed for serviceability and asked to guarantee it. We work with lenders that lend to family trusts, including discretionary, unit and hybrid trusts, and match your structure to their policy before anything is lodged.

What types of trusts can borrow money to buy property in Australia?

+
The trust structures we see borrowing to buy property are discretionary (family) trusts, unit trusts and hybrid trusts. Bare trusts are used as the holding trust in SMSF borrowing, and since 10 August 2026 new SMSF borrowing is limited to business real property: premises used wholly and exclusively in a business. Each structure has different tax and asset protection features, and lenders assess them differently. Some lenders only take simple discretionary trusts with individual trustees; others accept corporate trustees. We assess your structure and match it to lenders who can take it.

Can a company borrow to buy residential property in Australia?

+
Yes. A company can buy residential investment property, although fewer lenders offer this than lend to individuals or trusts. A company loan usually needs personal guarantees from the directors. Pricing is often close to investor pricing, but each lender sets its own. The lender looks at the company's financial position, the purpose of the purchase and the guarantors' ability to service the debt. Business owners sometimes hold investment property in a company for liability or estate planning reasons; your accountant can tell you whether that suits you.

What is the difference between borrowing in a family trust versus an SMSF?

+
Both borrow through an entity rather than in your own name, but the rules are completely different. An SMSF loan (an LRBA) is governed by superannuation law: the property is an investment of the fund, you cannot live in it, and since 10 August 2026 new SMSF borrowing is limited to business real property: premises used wholly and exclusively in a business. A family trust loan sits outside super, so those rules do not apply, and the structure is chosen for tax and asset protection reasons. Some clients hold both. See our SMSF loans page for what is still possible in super.

What are the different types of trusts in Australia and how do lenders treat them?

+
The main trust types in property lending are: (1) Discretionary (family) trust: the trustee decides each year how income is distributed. Most trust lenders accept these, usually with guarantees from the people behind the trust. (2) Unit trust: beneficiaries hold fixed units, a bit like shares, often used for joint ventures. Fewer lenders take them. (3) Hybrid trust: a mix of both, which needs a lender that will review the deed closely. (4) Bare trust: the holding trust in SMSF borrowing, under separate super rules. Lender appetite, maximum LVR and documents differ across all four, so we review your deed and match it to lenders before you apply.

Costs, tax and structure

What are the benefits of buying property in a trust structure?

+
People usually choose a trust for asset protection, flexibility in how income is distributed, and estate planning. A discretionary trust can let the trustee decide each year which beneficiaries receive income, and trust assets may be harder for a beneficiary's personal creditors to reach, depending on how the trust is set up. There are trade-offs too: tax on capital gains, land tax and losses can all work differently in a trust. This is general information only. Speak to your accountant before you choose a structure; we then make sure it can be funded.

Do lenders charge higher interest rates for trust or company loans?

+
Pricing for trust and company loans is often close to standard investor pricing, but some lenders add a margin or fees, and each lender sets its own. The bigger difference is choice: fewer lenders offer trust and company loans, so the field is narrower. We compare the lenders that actively support these structures and negotiate within that group, rather than forcing a trust loan into a lender whose policy does not suit it.

Are there tax implications I should consider before borrowing in a trust to buy property?

+
Yes, and they should be worked through with your accountant before you buy. The points people most often raise with us are: the CGT discount works differently for trusts and companies than for individuals; losses made in a trust generally stay in the trust rather than reducing your personal tax; land tax can apply differently to property held in a trust in NSW; and negative gearing inside a trust does not directly offset your salary. None of this means a trust is wrong for you. It means the tax, asset protection and estate planning sides need to be modelled from the start. This is general information, not tax advice.

Applying with RyRo

Will I need to personally guarantee a trust loan?

+
Usually, yes. Most lenders ask the people behind a trust or company, such as individual trustees, the directors of a corporate trustee, or the main beneficiaries, to sign personal guarantees. That means you can be personally liable if the trust or company cannot repay. Each lender sets its own rules on who must guarantee. Speak to your solicitor about what a guarantee means for you before you sign.

What documents do I need for a trust loan?

+
Expect the usual home loan documents for each guarantor (ID, income evidence, statements) plus the entity's documents: a full copy of the trust deed and any variations, details of the trustee and appointor, the company's ASIC extract if there is a corporate trustee, and the trust's or company's tax returns and financials if it already earns income. Lenders differ on exactly what they ask for. Our self-employed document checklist covers most of it.

Who should I talk to first, an accountant or a broker?

+
Talk to your accountant about whether a trust or company suits you, and to a solicitor about setting it up. Talk to us before the deed is signed or before you buy, so we can check the structure works with lenders. Some deeds are drafted in ways that make lending harder, and that is far cheaper to fix before the deed is executed than after a lender declines it.

Can a trust refinance?

+
Yes. A trust or company can refinance to another lender that accepts its structure, to get sharper pricing, release equity for another purchase or tidy up a loan structure. The new lender reviews the trust deed and the guarantors again, so the paperwork is similar to the first application. We check which lenders will take your structure before you apply.

How long does approval take?

+
Usually longer than a loan in your own name, because the lender's credit team and solicitors review the trust deed, the trustee and the guarantees as well as your income. How long depends on the lender and how complete the file is. Sending a full deed, the entity documents and every guarantor's paperwork up front is the best way to avoid delays, which is why we package the file before it goes in.

Free trust loan assessment

Ready to Structure Your Property Purchase in a Trust or Company?

Join 2,500+ Australians who've trusted RyRo Loan Centre. Specialist trust loan advice. $0 broker fees. Most trust loan failures come from lender mismatch or deed issues, not from client creditworthiness. We fix both before we submit a single application.
Sumit Joshi, principal broker at RyRo Loan Centre

Get started

Tell us your structure and what you're looking to buy, we'll assess it and match you to the right lender.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

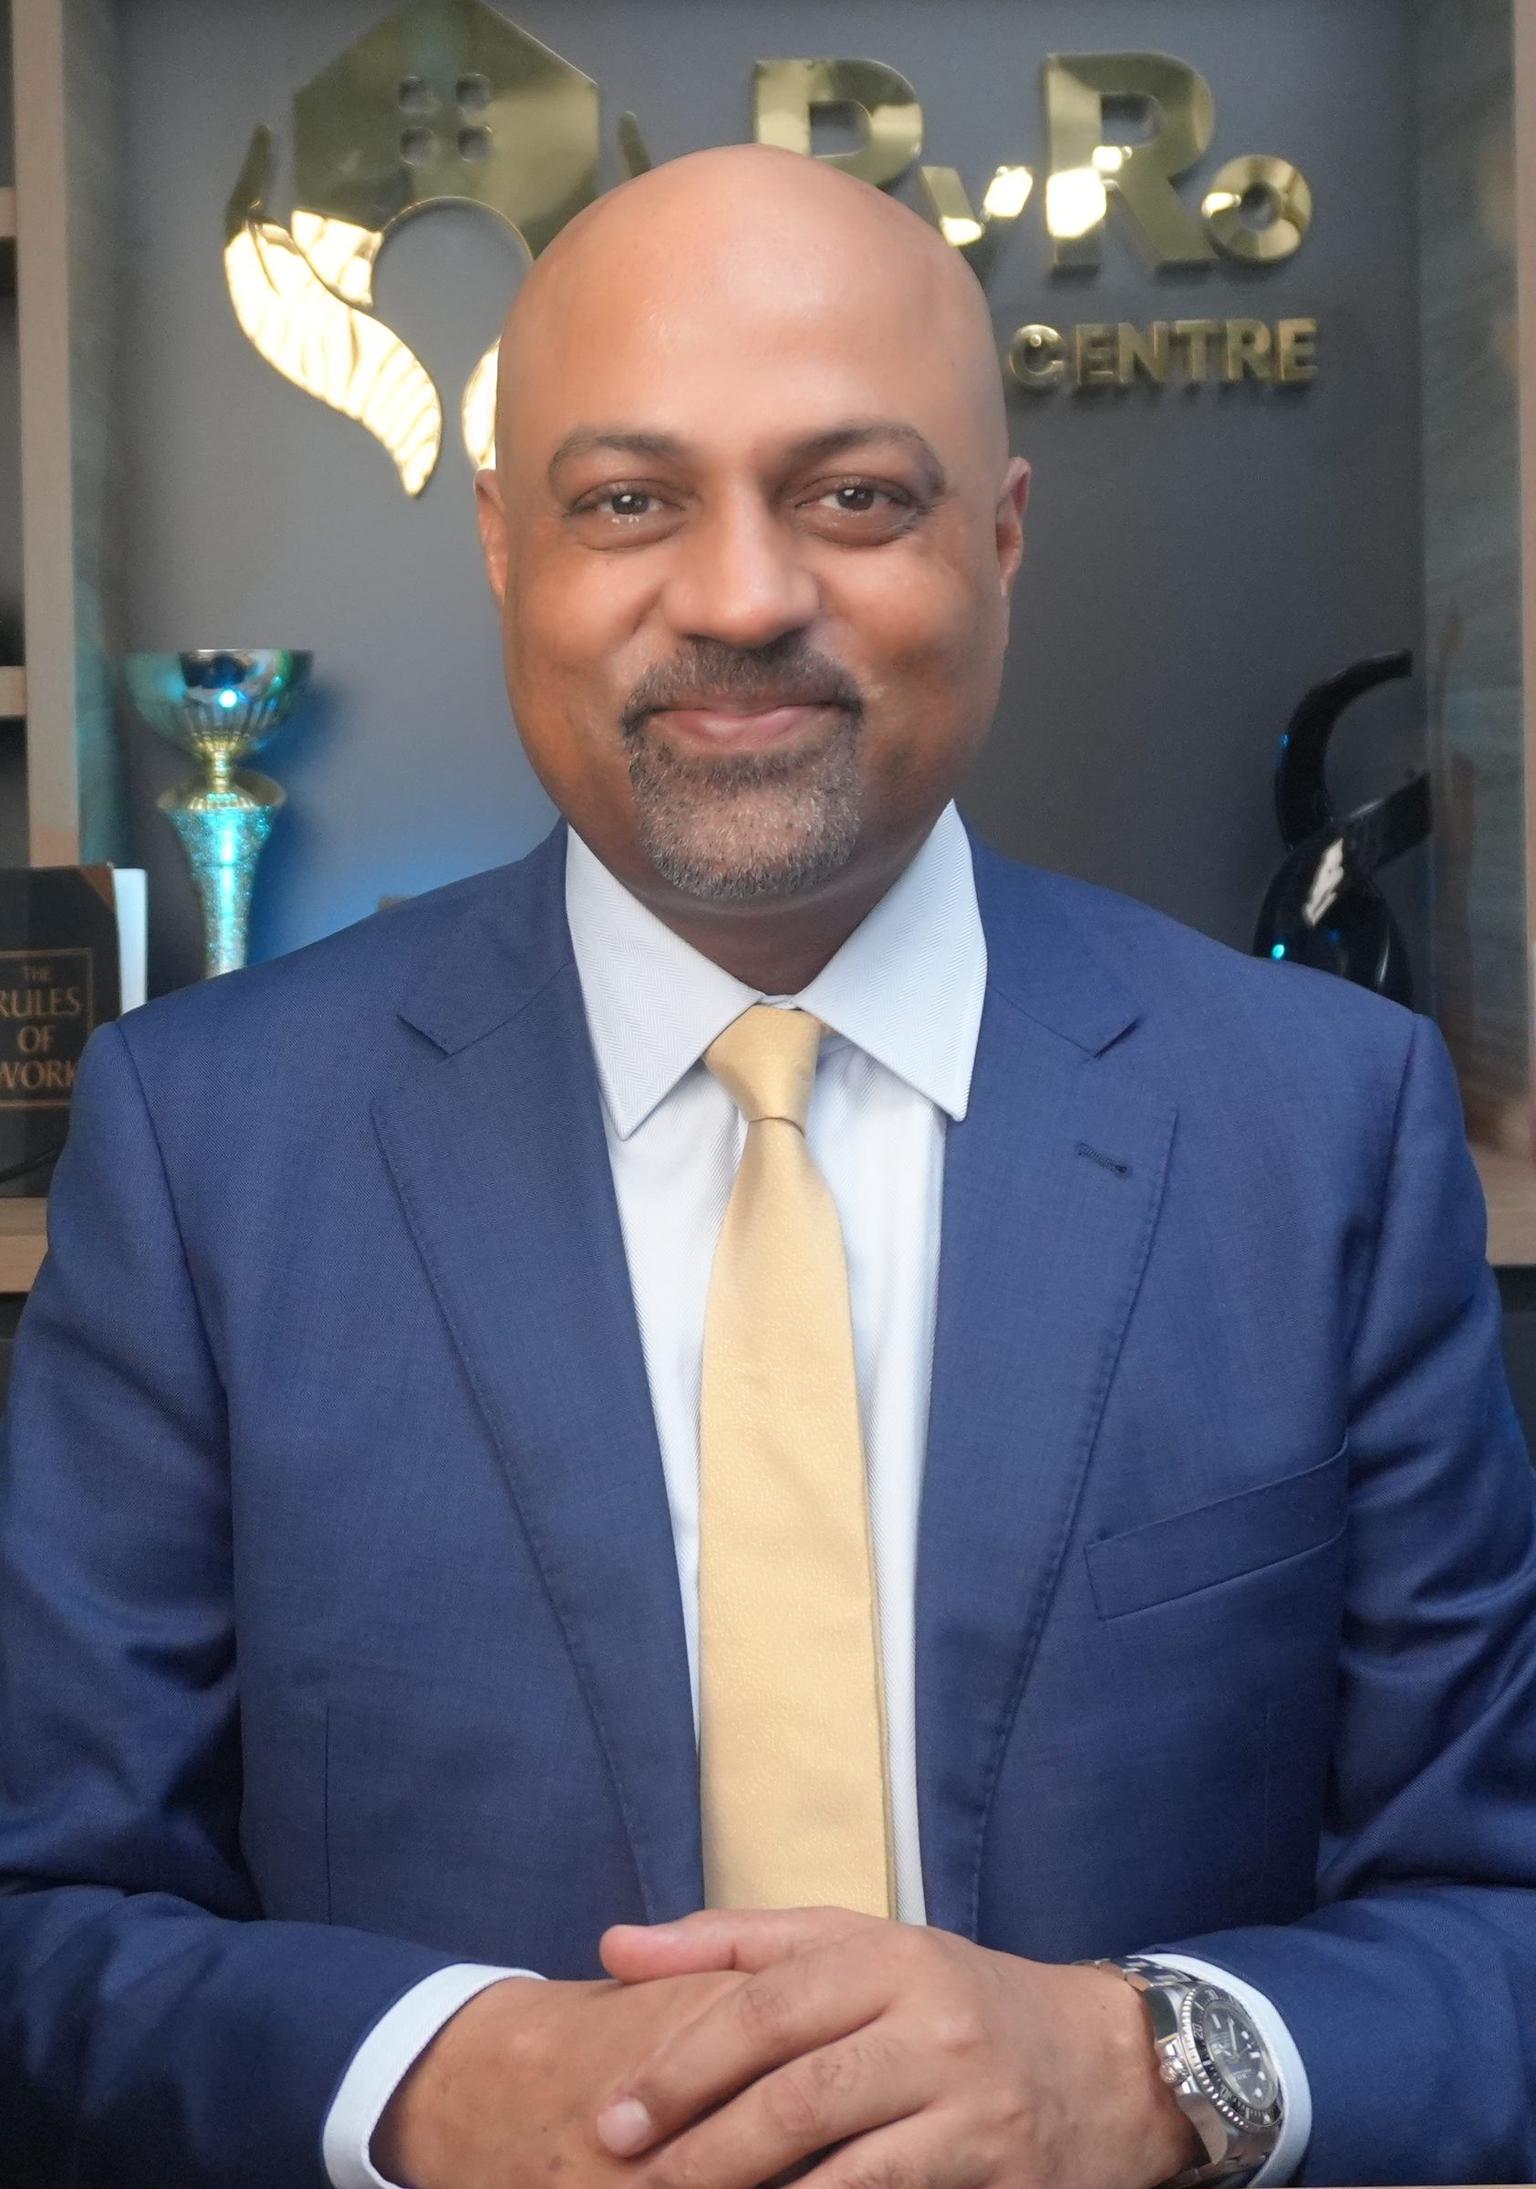
Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reads your structure and calls you back
  • Lenders matched to your deed and trustee
  • Free for home loans: the lender pays us
Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Lenders compared, including trust loan specialists
50+
“Sumit has been assisting us with mortgage products for a few years now. His customer service, knowledge and problem-solving abilities continue to be outstanding. I can’t recommend Sumit and his team highly enough as an ethical and knowledgeable broker who is solution focused and thoroughly able to navigate complex circumstances with sensitivity to achieve sustainable results. Very responsive and would call back straightway with solutions and had the patience and time to explain things to us in simple terms. Sumit was able to achieve a great result through a really difficult time of multiple lockdowns. It was a great result and really appreciated. Thanks once again Sumit!”
Z D · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026. General information only, not tax or legal advice. Speak to your accountant or solicitor about your structure. Lender policies, pricing and fees change.

Get my free loan review