RyRo Loan Centre

Free bridging loan estimate

Bridging Loan Calculator

Buying your next home before you sell? Work out your peak debt, the bridging interest while you own both homes and the loan you keep once your sale settles. Built for Sydney and NSW, and the maths works anywhere in Australia.

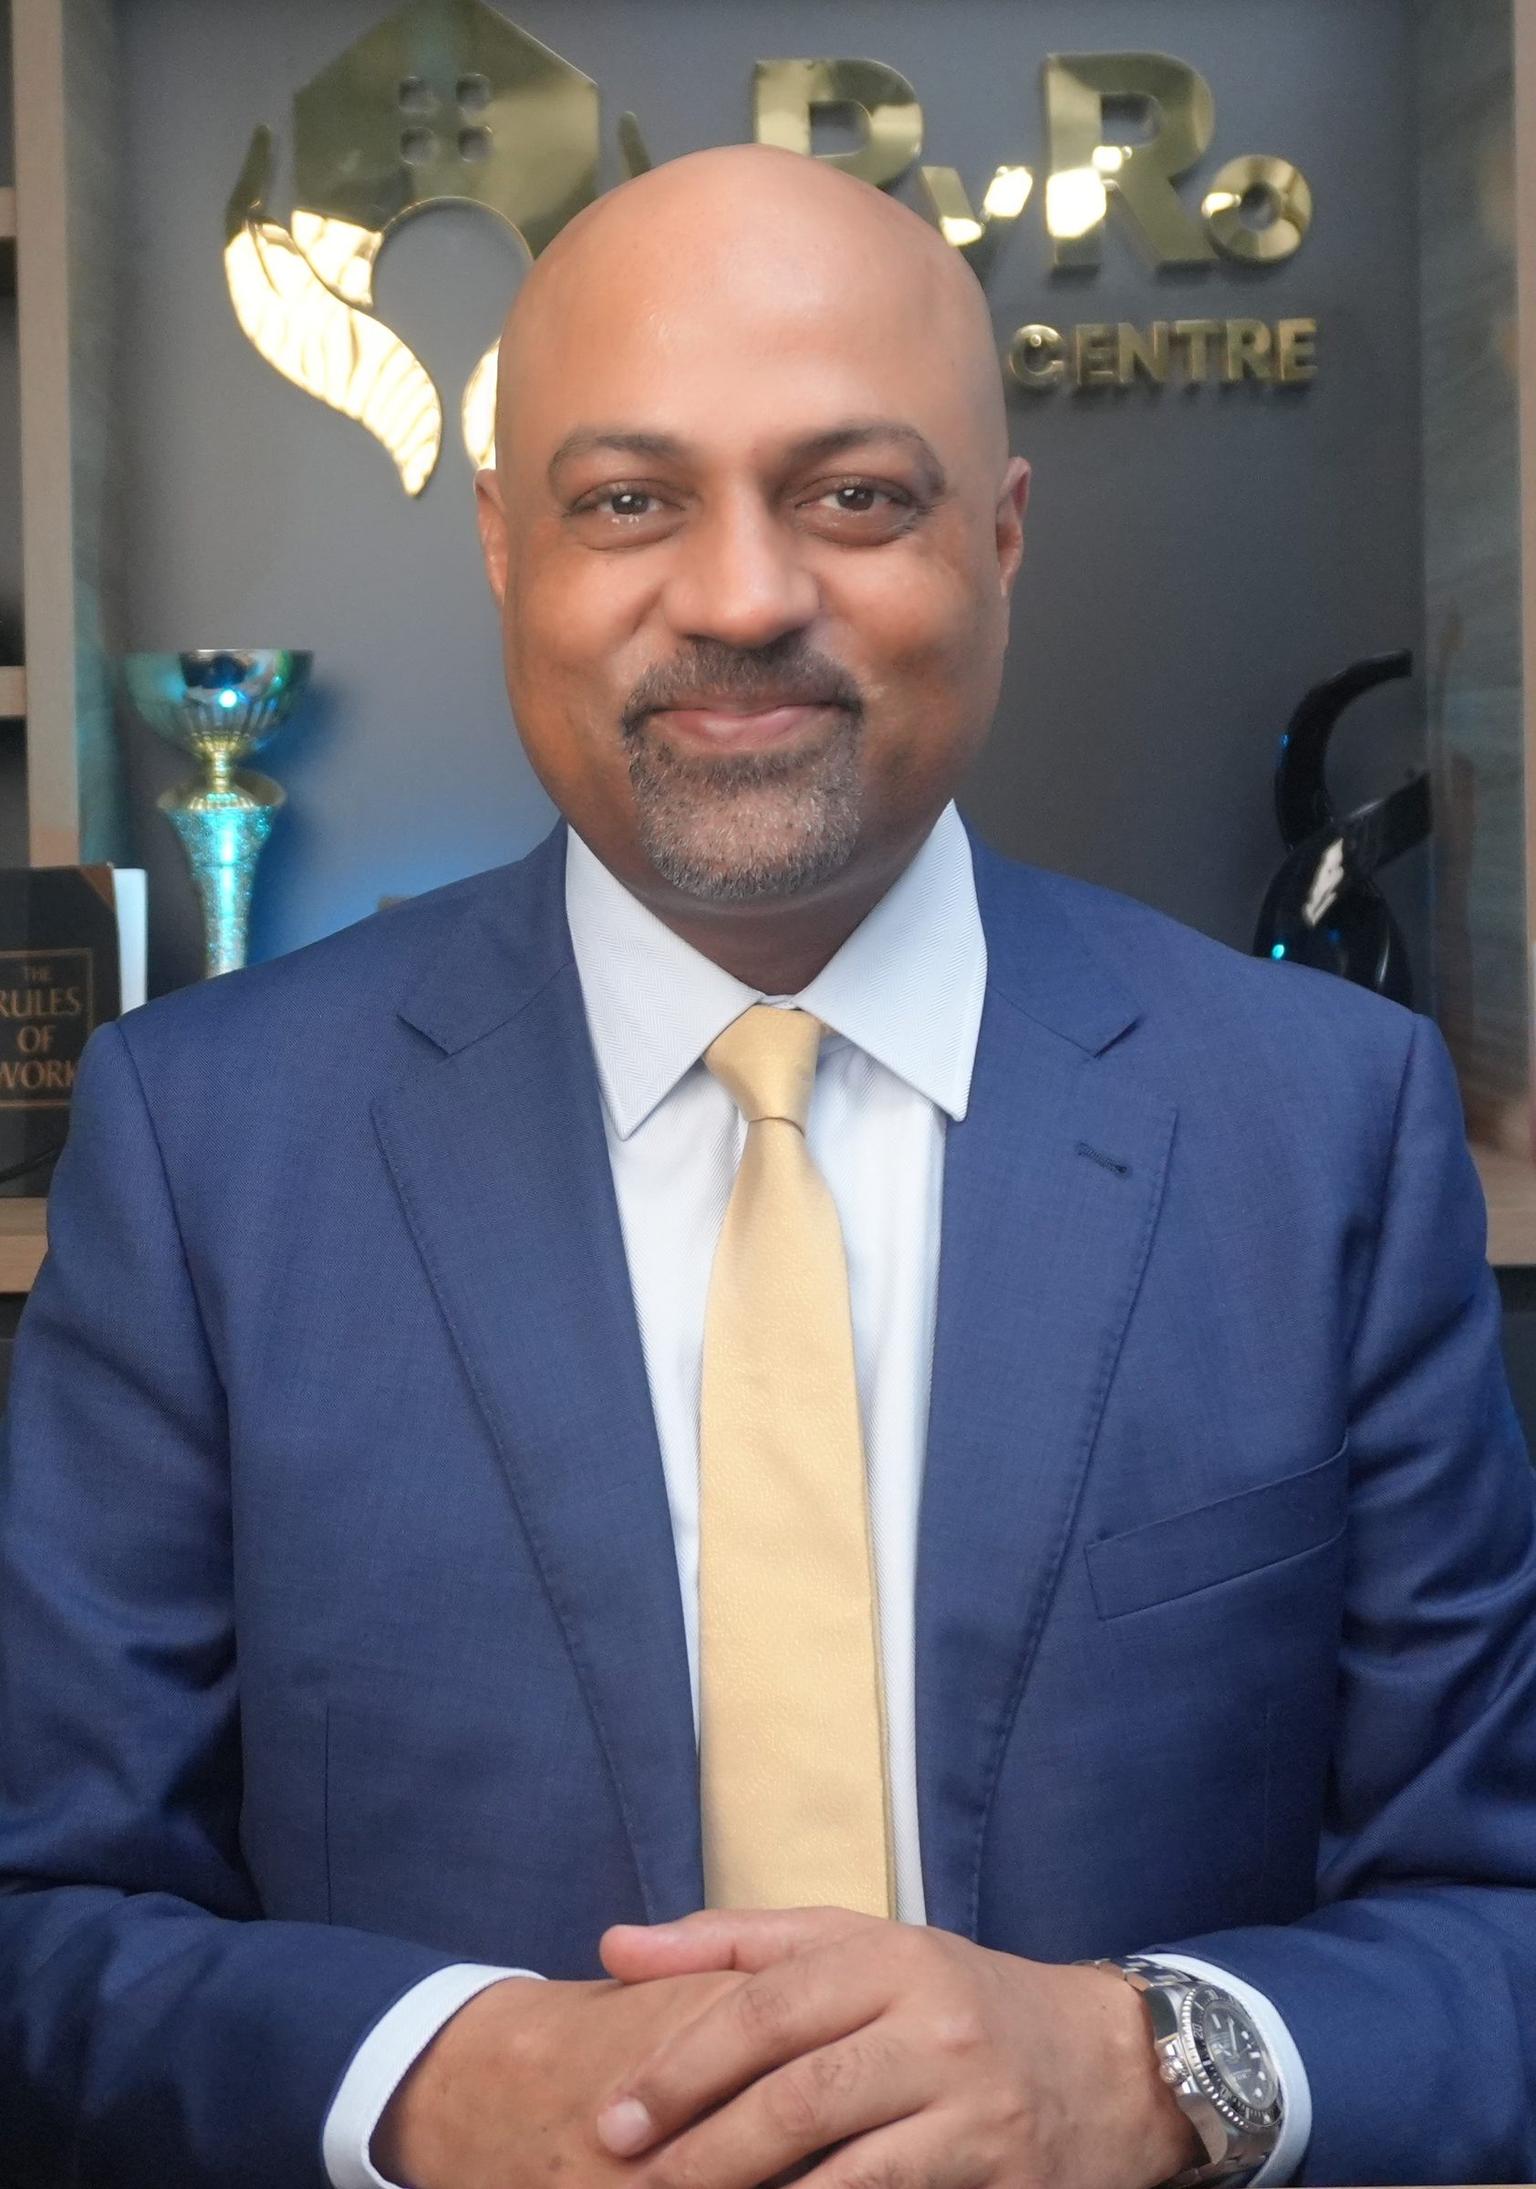
Sumit Joshi, principal broker at RyRo Loan Centre

Get your bridging plan checked

Your real numbers, matched to lenders that bridge.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Peak debt, interest and end debt in seconds
  • Capitalised or interest-only bridging, 1 to 12 months
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Bridging finance calculator

Bridging loan calculator

Enter the home you are selling, the one you are buying and how long the sale might take. Every figure filled in is an example, including the rate.

Last updated: November 2026

The figures filled in are examples only, including the rate. Replace each one with your own.

The home you are selling

The home you are buying

The bridging period

% a year
months
How is the bridging interest paid?
More details(optional, 5)
% inc GST
years

Peak debt while you own both homes

$2,124,287

About 71% of both homes' value together

Bridging interest added over 6 months
$69,981
End debt: the loan you keep
$834,268
Repayment on it over 30 years
$5,273 a month
How it adds up
Expected sale price
$1,400,000
Less selling costs
-$40,000
Sale money for the lender
$1,360,000
Current loan
$450,000
Next home
$1,600,000
NSW stamp duty (general rates)
$69,287
Other buying costs
$5,000
Peak debt
$2,124,287
Plus bridging interest
$69,981
Less sale money
-$1,360,000
End debt: the loan you keep
$834,268

A simple model: one rate for the whole loan, interest on the whole peak debt for every month, no lender fees, valuations or capital gains tax. Stamp duty uses general NSW transfer duty with no concessions. Lenders set their own bridging terms, limits and rates, and assess the end debt against your income.

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

Want the selling side line by line? The property selling costs calculator breaks down agent fees, marketing and the loan payout.

Quick answer

How is a bridging loan calculated?

Add your current loan, the new home, stamp duty and buying costs to get your peak debt. Add the interest for the months until your sale settles. Take off what the sale brings in after selling costs, and what is left is your end debt: the home loan you keep.

Maximum bridging term published by CommBank and Westpac
12 months
Source: CommBank and Westpac bridging loan pages, checked November 2026
Interest is either added to the loan each month or paid as interest only
2 ways
Source: Westpac and CommBank bridging loan pages
NSW stamp duty on a $1,600,000 next home, part of your peak debt
$69,287
Source: Revenue NSW general transfer duty, 2026/27

The formula

How the bridging loan calculator works

Four numbers come out of the calculator. Each one answers a question a lender will ask you.

  • Peak debt

    Your current loan, the new home, stamp duty and buying costs, less your own cash. Lenders look at it against both homes together.

  • Bridging interest

    Interest on the peak debt for each month until your sale settles. Added to the loan, or paid each month as interest only.

  • End debt

    What you still owe once the sale money, after selling costs, pays the loan down. This is the home loan you keep.

  • Repayment on the end debt

    The monthly principal and interest on the end debt over your term. Check the end debt fits your income with the borrowing power calculator.

Sumit · 1:14
Upgrading? Keep your first home or sell itSumit Joshi, RyRo Loan Centre · Sumit on upgrading, from our Instagram

Want the lender's numbers, not an estimate?

We check which lenders bridge for your timeline, how they value both homes and whether they capitalise the interest.

Check my bridging plan

Free. No obligation and no credit check.

Reading your result

What your result means

The calculator lands on one of three answers. Here is what each one tells you.

  • Money left over

    Your sale covers the new home, so any bridging loan is short and cleared at settlement. Common when downsizing.

  • An end debt you can carry

    The usual result when upsizing. The lender checks your income against the end debt with its own buffer.

  • A big share of both homes

    When peak debt is a large share of both homes, fewer lenders will bridge. More cash, a lower price or another way to move may suit.

Why a lender's figure can differ

The calculator uses one rate, charges interest on the whole peak debt every month and leaves out lender fees and valuations. A lender values both homes itself, may set a more cautious sale price and works out interest daily. Each lender sets its own bridging limits.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824

Worked examples

Bridging loan examples in Sydney

Three common moves, run through the same maths as the calculator at an example rate of 6.5%. These illustrate the estimate; they are not client figures or a rate quote.

Upsizing in the Hills, interest added to the loan

Selling for $1,400,000 with $450,000 owing, buying at $1,600,000. The sale takes 6 months and the interest is capitalised.

Peak debt
$2,124,287
Interest added
$69,981
End debt
$834,268
Repayment over 30 years
$5,273 a month

The bridging interest adds to the end debt. Test 9 or 12 months too: each extra month adds more.

The same move, interest only

The same two homes, but the lender asks for interest-only repayments during the bridge.

Peak debt
$2,124,287
Interest-only payment
$11,507 a month
End debt
$764,287
Repayment over 30 years
$4,831 a month

A smaller end debt, but you need the monthly payment from income or savings while you own both homes.

Downsizing, the sale covers the next home

Selling the family home for $1,600,000 with $150,000 owing, buying a $900,000 home. The sale settles in 4 months.

Peak debt
$1,089,687
Interest added
$23,802
Left over
$444,511

No end debt: the bridge is short and the sale clears it. Lenders still check you can carry the bridge itself.

Bridging loan repayments

Capitalised interest or interest only?

On the upsizing example, capitalising adds $69,981 to the loan. Paying interest only costs $11,507 a month instead and leaves a smaller end debt.

Capitalised and interest-only bridging compared
Added to the loanInterest only
Repayments while you own bothNone on the bridgeMonthly interest
Loan balance during the bridgeGrows each monthStays the same
End debtHigherLower
Suits you ifCash flow is tight while you hold two homesYour income or savings can cover the payment

Westpac capitalises the interest on its bridging loan; CommBank asks for interest-only payments (both checked November 2026). Other lenders vary.

Desk calculator beside a laptop and printed budget charts
A slower sale costs more under either option, so test both against 9 and 12 months. Photo: Jakub Żerdzicki / Unsplash

Google reviews

Upgraders on working with Sumit

Real Google reviews of RyRo Loan Centre, word for word.

Google

5.0

From 360+ Google reviews

Sumit · 2:56
Approved in days after her broker went quietSumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • Varsha Mehra

    2 years ago on Google

    Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

    Varsha Mehra

    Google2 years ago on Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

  • Guru Prasadh

    3 years ago on Google

    Google

    Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

    Guru Prasadh

    Google3 years ago on Google

    Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

  • Karl Gilbert

    5 years ago on Google

    Google

    When going thru the stress of purchasing a new home, it helps when you have friends that have gone thru the process. This is how I met Sumit, and the crew at RyRo Loan Centre. They made the whole process as painless and stress free as I could believe possible. Added to that, the fact that we needed the loan quickly approved before the Christmas break, Sumit and his team pulled out all the stops, to make sure we hit the time for settlement at the most difficult time of year. I wish to thank Sumit and his team for all their assistance, and the continual updates on rate information and advice.

    Karl Gilbert

    Google5 years ago on Google

    When going thru the stress of purchasing a new home, it helps when you have friends that have gone thru the process. This is how I met Sumit, and the crew at RyRo Loan Centre. They made the whole process as painless and stress free as I could believe possible. Added to that, the fact that we needed the loan quickly approved before the Christmas break, Sumit and his team pulled out all the stops, to make sure we hit the time for settlement at the most difficult time of year. I wish to thank Sumit and his team for all their assistance, and the continual updates on rate information and advice.

Moving within the Hills? Our Norwest office plans bridging for owners from Castle Hill to Kellyville. Meet a mortgage broker in the Hills District before you make an offer.

How does a bridging loan calculator work?

+
It adds up what you would owe while you own both homes (your current loan, the new home, stamp duty and buying costs), adds the interest for the months until your sale settles, then takes off what the sale brings in after selling costs. What is left is your end debt, the loan you keep. Ours also shows the monthly repayment on that end debt, so you can test it against your budget.

How is bridging loan interest calculated?

+
Interest is charged on the bridging balance for each month you hold both homes. Some lenders add it to the loan each month (capitalised), so you make no bridging repayments but the balance grows. Others ask for interest-only repayments. Our calculator does both: capitalised interest compounds monthly on the peak debt, and interest only shows the monthly payment. Your lender works it out daily at its own rate, so treat ours as a guide.

What is peak debt in a bridging loan?

+
Peak debt is the most you owe while you own both homes: your current loan plus the price of the new home, the stamp duty and buying costs, less any of your own cash you put in. Lenders look at it against the value of both properties together, which is why the calculator shows it as a share of both homes. It falls back to your end debt once your old home sells.

What is end debt?

+
End debt is what you still owe after your current home sells and the sale money, less agent fees and other selling costs, is paid off the loan. It becomes an ordinary home loan on the new home. Lenders care most about whether your income can repay it, so the calculator shows the monthly repayment on the end debt over the term you choose.

How long can a bridging loan run?

+
It depends on the lender. CommBank and Westpac both publish a maximum bridging term of 12 months (checked November 2026), so the calculator lets you test 1 to 12 months. Other lenders set their own limits, and some allow less time when your home is not yet on the market. Run the numbers for a slow sale as well as a quick one before you commit.

Can I use the calculator if I am downsizing?

+
Yes. Put in the price of your smaller home and the calculator shows whether your sale covers it. For many downsizers the end debt is nil and the result shows what is left over, which tells you the bridging loan would be short and cleared at settlement. Lenders still check you can manage the bridge itself, including when the loan runs close to retirement, so talk the plan through with a broker.

Does this bridging loan calculator work anywhere in Australia?

+
The bridging maths works the same in every state. The stamp duty line uses general NSW transfer duty, because most of our clients buy in Sydney. If you are buying in another state, get the duty from that state revenue office and add the difference to other buying costs. Lender bridging rules are national, but each lender sets its own.

Why is my lender's figure different from the calculator?

+
The calculator uses one rate for the whole loan, charges interest on the whole peak debt every month and leaves out lender fees, valuations and capital gains tax. Your lender values both homes itself, may set a lower sale price than you expect, charges interest daily and adds its own buffer when it checks your income. That is why a broker should run your real numbers before you sign a contract.

What to do next

Put your bridging estimate next to the other numbers

Selling costs, stamp duty and your borrowing power decide whether a bridging loan works. Read up on bridging finance or run the other tools.

Free PDF · 12 pages
Photo: Brian Babb / Unsplash

Refinancing and equity

Sydney Upgrader's Bridging Loan Playbook

  • Peak debt and end debt with worked numbers
  • Bridging vs deposit bond vs settlement extension
  • A self-check before you commit
Free PDF · 10 pagesNew November 2026
Photo: Nicolas Gonzalez / Unsplash

Refinancing and equity

The Stress-Free Downsizing Guide (2026 Edition)

  • Sell first, buy first, longer settlement or bridging, compared
  • A worked Sydney example: does your sale cover the next home?
  • How lenders look at borrowers aged 55 and over

Want the worked example in more detail? Read our bridging loan guide for Sydney upgraders, or book a free strategy call.

Free bridging check

Talk to a broker before you buy before you sell

Sumit tests your sale price, timeline and end debt, then matches you to lenders whose bridging rules fit. 5.0 stars from 360+ Google reviews and 2,500+ clients helped. We generally respond within an hour.
Sumit Joshi, principal broker at RyRo Loan Centre

Get your bridging plan checked

Your real numbers, matched to lenders that bridge.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Peak and end debt checked against real lender rules
  • Bridging compared with selling first or a longer settlement
  • Free for home loans: the lender pays us
Sumit · 1:14
Upgrading? Keep your first home or sell itSumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Bridging loan check
Free
“Sumit is an outstanding mortgage broker. He patiently worked through our application and got us an awesome result when many other brokers wouldn't assist as we are small business owners. Thank you!”
Belinda White · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026. Bridging estimates are a guide only, not an offer of credit. Each lender sets its own terms. Prefer to talk first? Book a free strategy call.

Get my free loan review