Daljeet Singh
9 months ago on Google

I have wonderful experience with them they are professional,quick and accurate in terms of loan requirements
Mortgage brokers in Norwest, helping the Hills District and Sydney
Finance lease and hire purchase, RyRo Asset Finance
Use the vehicle or equipment your business needs now and pay for it over time. Rohan Joshi at RyRo Asset Finance compares lease and hire purchase lenders and explains the residual, GST and end of term before you sign.
5.0 from 13 Google reviews for RyRo Asset Finance
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Updated November 2026
Finance lease explained
A finance lease lets your business use a vehicle or piece of equipment while the lender owns it. The lender buys the asset you choose and leases it to you for a fixed term, with fixed monthly payments. A residual value is set at the start, and at the end you decide whether to pay it and keep the asset.
Commercial hire purchase is its close cousin: the lender also buys the asset, but it becomes yours once the last payment is made. Both sit alongside the chattel mortgage, where your business owns the asset from day one. Rohan arranges all three as part of our asset finance service, from the RyRo office in Norwest.
Quick answer
Ownership. With hire purchase the asset becomes yours on the final payment. With a finance lease the lender owns it for the whole term, and you choose at the end whether to pay the residual and keep it.
Step by step
You pick the asset and the supplier. The lender pays for it and leases it to your business. Here is what happens from quote to the end of the term.
Step 1
A vehicle, machine or equipment from a dealer or supplier. Send Rohan the quote or invoice.
Step 2
He matches the asset and your business to lenders whose policy fits, and sets the term and residual with you.
Step 3
The lender pays the supplier. You use the asset and make fixed monthly payments, with GST in each one.
Step 4
Pay the residual and keep the asset, refinance the residual, or sell or trade the asset to clear it.
Free, no obligation.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Daljeet Singh
9 months ago on Google
I have wonderful experience with them they are professional,quick and accurate in terms of loan requirements
Own it at the end
Commercial hire purchase is a hire purchase agreement for business use. The lender buys the asset and hires it to your business, you pay it off in instalments, and ownership passes to you with the final payment.
The lender holds title while you pay. You use, insure and maintain the asset.
Regular payments, with a balloon at the end on many agreements to lower them.
Once the final instalment or balloon is paid, ownership passes to your business.
The ATO treats hire purchase as a sale financed by a loan. Your accountant confirms the detail.
Rohan prices hire purchase and lease on the same asset.
5.0 from 13 Google reviews for RyRo Asset FinanceRyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Looking for the machine itself? See machinery finance or truck finance.
Compare the options
The four ways a business commonly pays for an asset over time. The big questions are who owns it during the term, what happens at the end, and how GST is handled.
| Finance lease | Hire purchase | Chattel mortgage | Operating lease | |
|---|---|---|---|---|
| Owner during the term | The lender | The lender | Your business | The lessor |
| At the end | Pay the residual, refinance or sell | Yours after the last payment | Already yours | Hand it back or renew |
| End amount | Residual value | Optional balloon | Optional balloon | None |
| GST | In each payment | Generally up front | Generally up front | In each payment |
| End value risk | Your business | Your business | Your business | Usually the lessor |
General features only. Each lender sets its own terms, and the tax treatment depends on your situation.
Want to own the asset from day one? Read about chattel mortgage finance and our chattel mortgage guide, or test repayments with a balloon in the chattel mortgage calculator.
Rohan prices the options on your asset.

Residual value
The residual is the amount left owing at the end of a finance lease. It is agreed when you sign, and you do not pay it off during the term. That is why lease payments can be lower than a loan that clears the whole price. On hire purchase and chattel mortgage, the same idea is called a balloon.
Pay it and keep the asset. You pay the residual from cash and the asset is transferred to your business.
Refinance the residual. Rohan arranges a new loan for the residual amount, so you keep the asset and spread the cost.
Sell or trade it. The sale or trade-in pays out the residual. If it sells for more, the difference is yours; if less, your business makes up the gap.
General information
The biggest practical difference between a lease and hire purchase is often tax timing. This is how the ATO describes it in general terms. Your accountant applies it to your business.
GST is in each lease payment, and a GST registered business generally claims a credit on each one. Lease payments for business use are commonly claimed as an expense. If you buy the asset at the end, GST in that price may also be creditable.
The ATO generally lets a GST registered business claim the GST in the purchase price up front. For income tax, hire purchase is treated as a sale with a loan, so the business usually claims depreciation and the interest part.

Rohan sends quotes your accountant can compare.
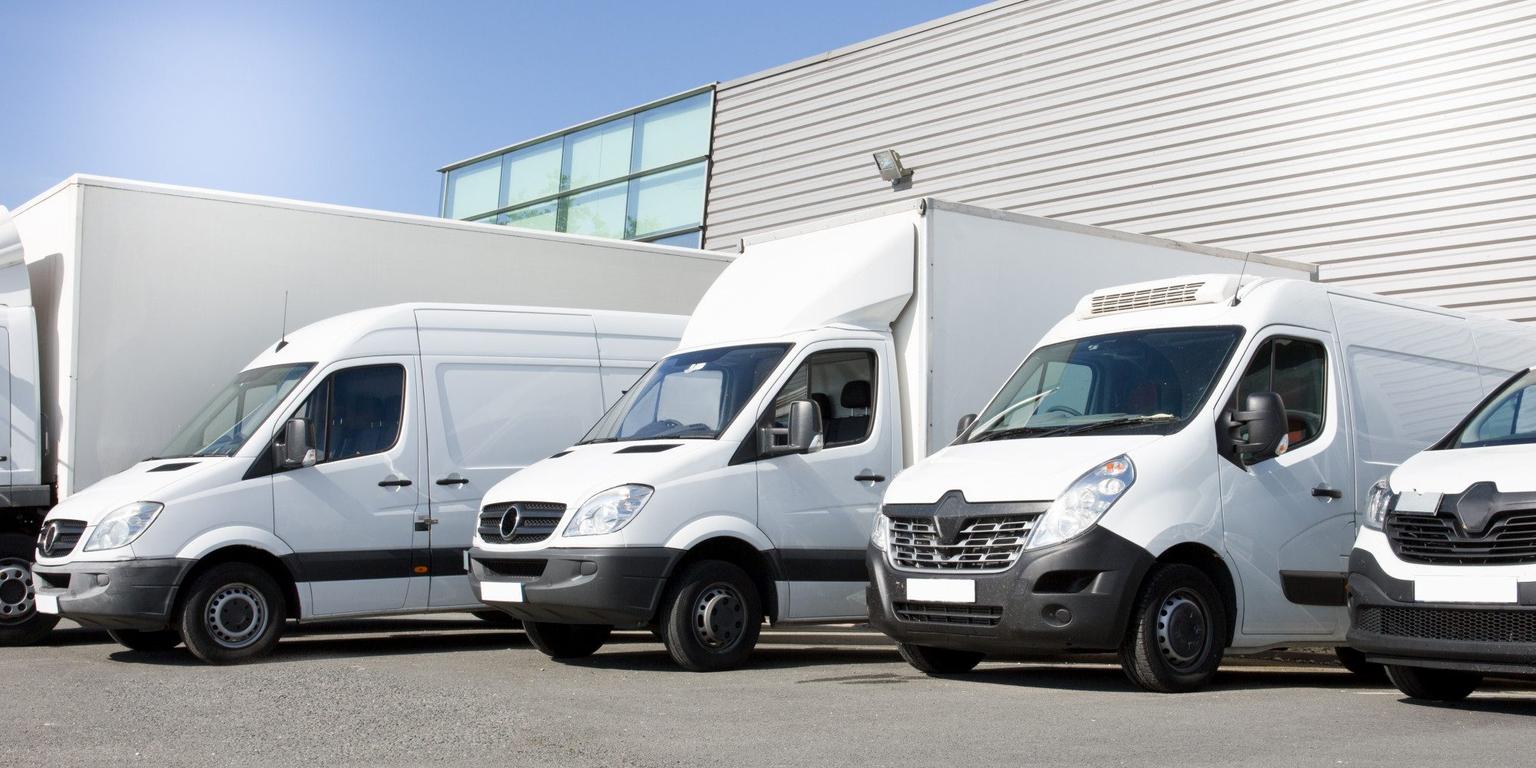
Equipment leasing and hire purchase
Both are business finance for assets used to earn income. These are the businesses we help most often.
Vans, trucks and trailers that earn their keep every day, financed without a large outlay.
Excavators, forklifts, utes and site gear, where the machine pays for itself on the job.
Equipment that dates quickly, where a residual lets you trade up at the end of the term.
Fixed payments you can budget for, with cash kept in the business for wages and stock.
Sole trader buying a work car? See ABN car finance.
Sound familiar?
Most business owners come to Rohan with one of these. Here is what usually gets in the way, and what we do about it.
5.0 from 13 Google reviews for RyRo Asset FinanceThe challenge: You were told a finance lease might suit your tax position, but nobody explained the residual or the end of term.
Rohan prices a lease, hire purchase and chattel mortgage on the same asset, so your accountant can compare them side by side.
The challenge: The dealer or supplier offered a lease on the spot, and the residual at the end looks larger than you expected.
Bring the quote. We compare it with other lenders and check the residual against what the asset is likely to be worth.
The challenge: You already finance a few vehicles or machines and need one more without stretching the business.
Rohan looks at your existing agreements and finds a lender whose policy fits the next one, before you commit to the purchase.
The challenge: The residual is due in a few months and you are not sure whether to pay it, refinance it or trade the asset.
We set out each option in plain English and, if you keep the asset, arrange finance for the residual.
These are common situations, not client stories. Every loan depends on your circumstances and the lender's policy.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
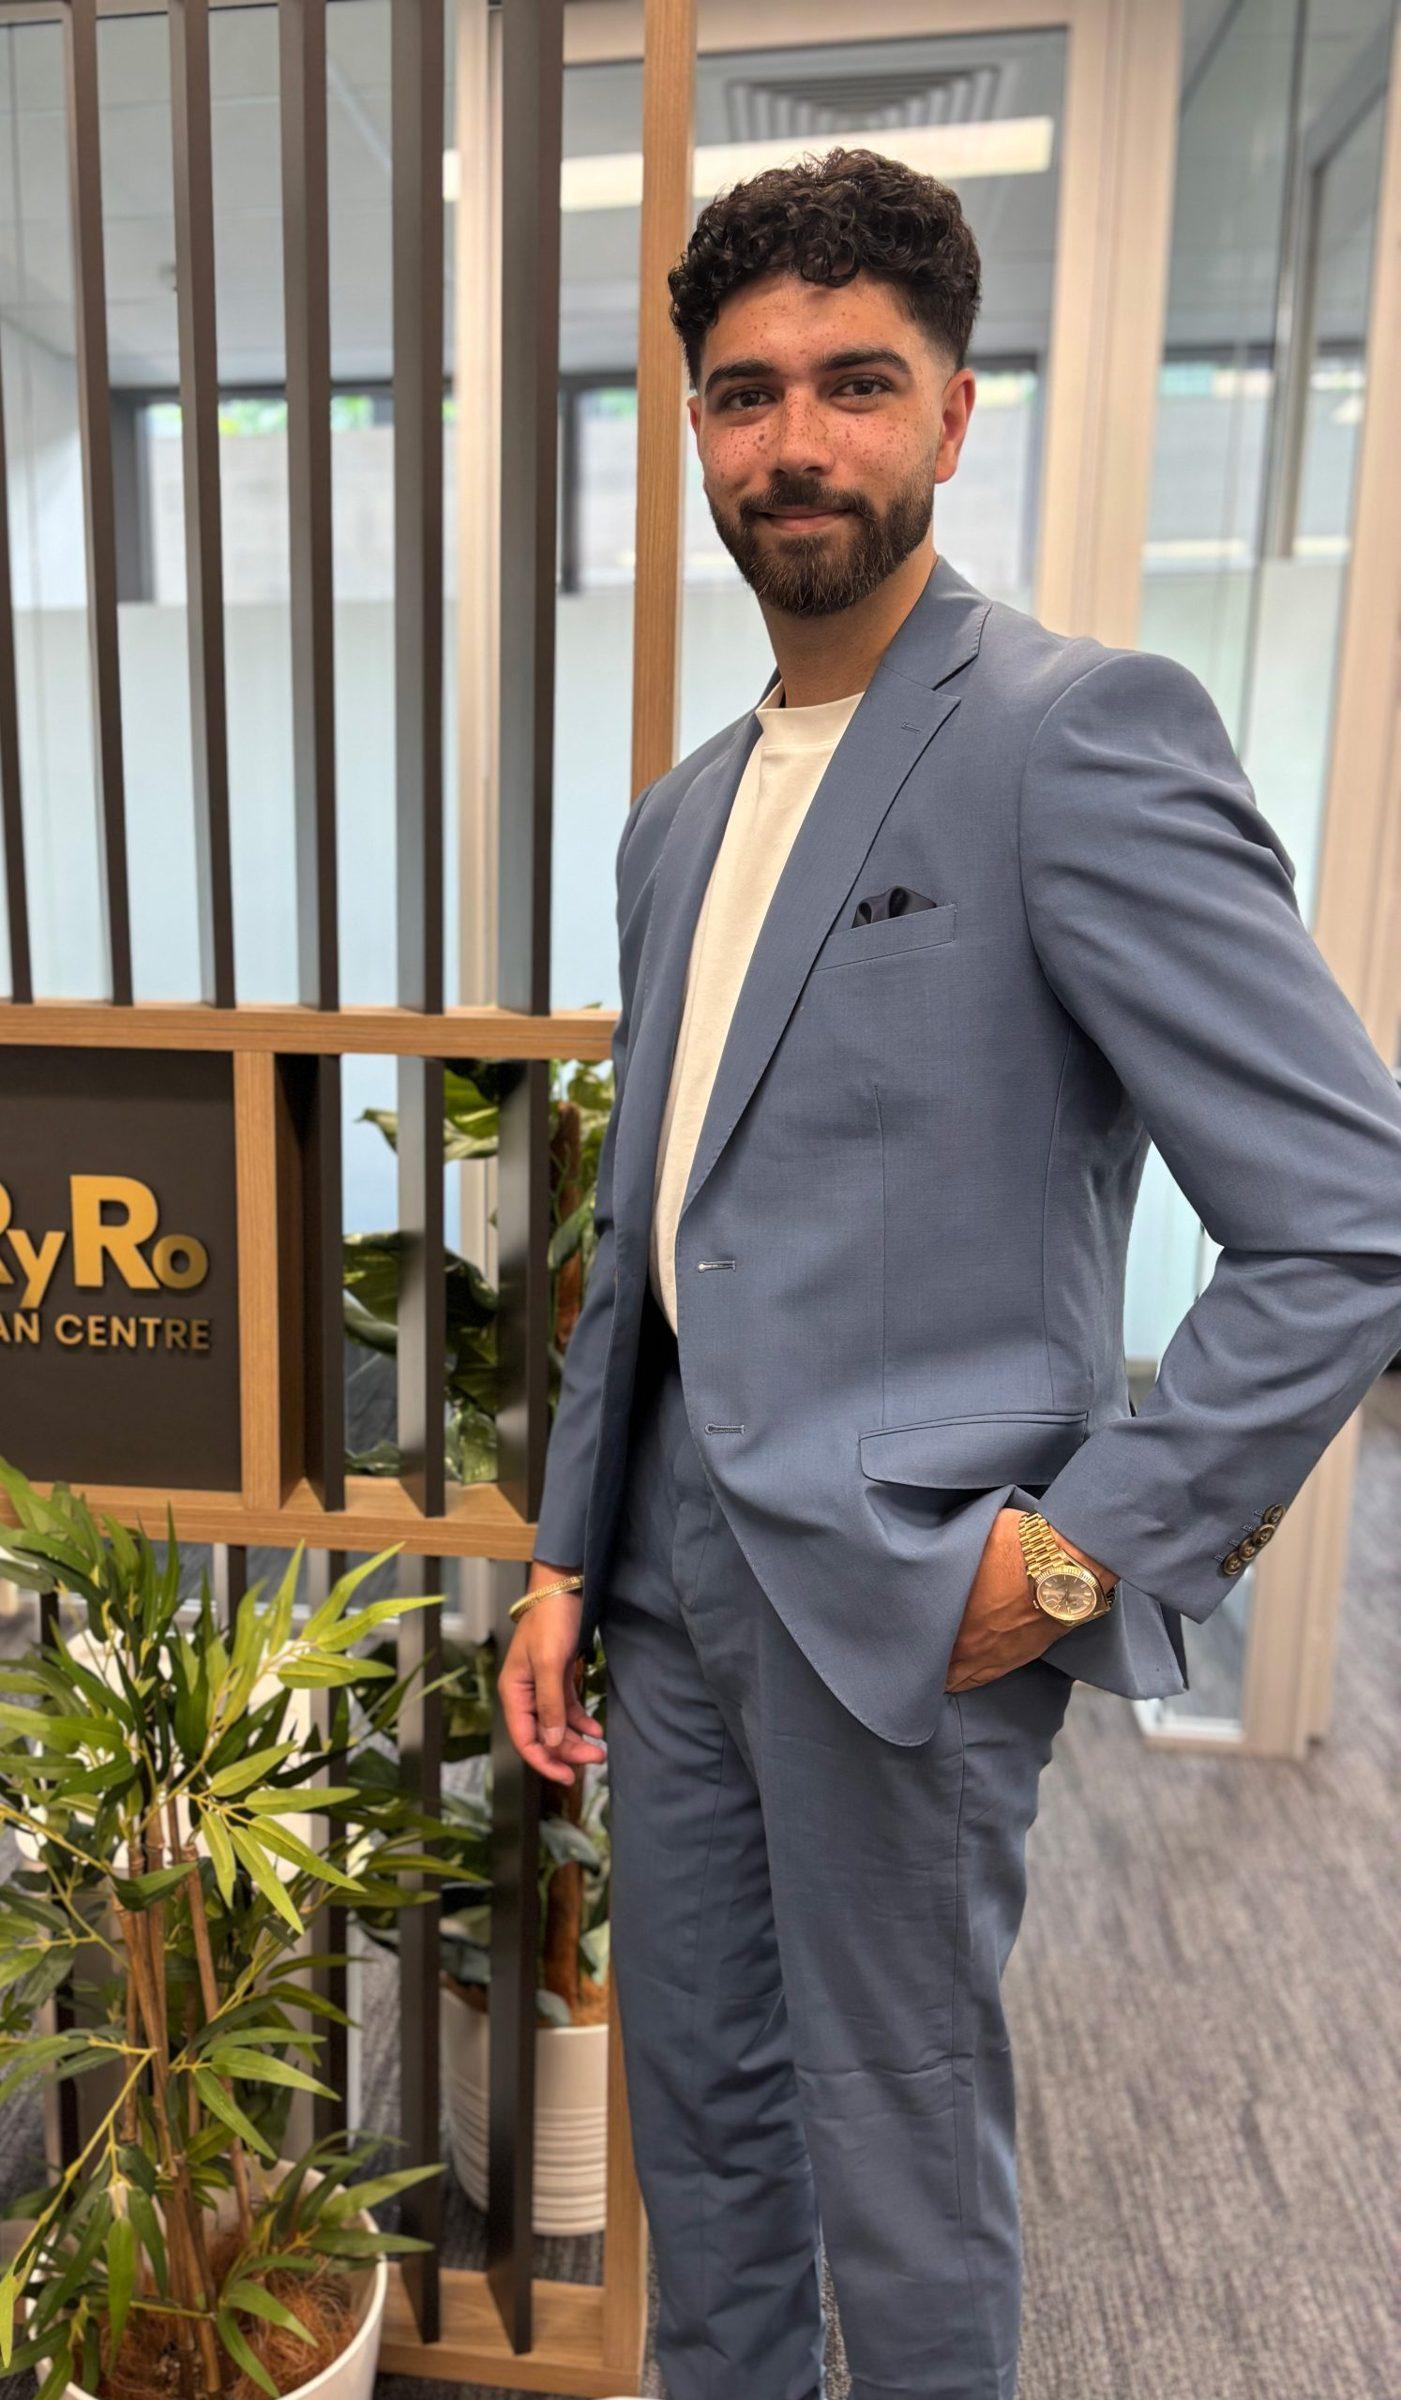
Rohan Joshi
Asset finance broker, RyRo Asset Finance, ACR 565295
Who you will deal with
You deal with one person. Rohan reads your details, prices the structures that fit, and explains the residual, the balloon and the end of term before you sign. His clients mention the same things in their Google reviews: clear explanations, quick answers and simple paperwork.
RyRo Asset Finance is a separate company from RyRo Loan Centre, working from the same Norwest office. If you would rather talk it through first, book a free strategy call.
Free, no obligation.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Google reviews
Real Google reviews of RyRo Asset Finance, word for word.
5.0
From 13 Google reviews for RyRo Asset Finance
Sumit Garg
a year ago on Google
Rohan been nothing short of excellent for us. Being proactive, professional and keeping things very simple and easy to deal with. Gave us an excellent deal and whole process was easy as. Thank you for being so helpful is getting us over the line in getting the new car
krunal shah
11 months ago on Google
Thank you for your support to get my business car loan done in 1 day. Highly recommend
Mark Donovan
a month ago on Google
Rohan provided exceptional service, was communicative and transparent through the entire process. I ended up with a far better deal than I would have got on my own.
David John
8 months ago on Google
We had a great expreience dealing with Rohan for vehicle finance. I would highly recommend him. He was very professional and easy to deal with.
Run the numbers
Talk to Rohan
We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.
Rohan Joshi
Asset finance broker, RyRo Asset Finance
More videos from Rohan
“I had an excellent experience with Rohan for my car loan. He was professional, responsive and extremely helpful throughout the entire process. He explained all the options clearly, found a competitive loan that suited my circumstances and made the paperwork simple and stress-free. I highly recommend RYRO services to anyone looking for a reliable and trustworthy car loan broker.”
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.