RyRo Loan Centre

Already own a home

Already Own a Home? Refinance, Use Equity or Buy a Second Home

Your home is worth more than a roof. Whether you want a better rate, cash for a renovation, a deposit for an investment or a move to your next place, Sumit compares 50+ lenders and sets up the loans the right way.

Sumit Joshi, principal broker at RyRo Loan Centre

What do you want your home to do next?

Free call with Sumit. No credit check, no obligation.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Refinance, equity, renovating, upgrading or investing
  • One broker from first call to settlement
  • Based in Norwest, Sydney. $0 broker fees on home loans
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Start here

What Are Your Options When You Already Own a Home?

Owning a home gives you choices first home buyers do not have. Most owners who contact us want to do one of six things. Pick yours and go straight to the detail.

Quick answer

Can I get a new loan if I already have one?

Yes. You can refinance, borrow against your equity, renovate, buy before you sell or buy an investment, as long as your income and the property values support it.

  • Hands signing loan paperwork at a deskRefinance

    Refinance to a better deal

    Move your loan to a lender with a sharper rate or better features. We compare the market and do the switching costs maths first.

    Is this you?

    This is for you if your loan has not been reviewed in two years or more, your fixed term is ending, or you suspect new customers are paid less than you. If the numbers do not stack up after costs, we tell you to stay put.

  • Aerial view of curving suburban streets lined with new family homesEquity

    Use the equity in your home

    Turn the value you have built into a deposit, a renovation budget or a buffer, with the right structure from day one.

    Is this you?

    This is for you if your home has gone up in value or your loan has come down, and you want to put that equity to work. We work out your usable equity, how a lender will value it and whether a top up, split or new loan suits.

  • Desk calculator beside a laptop and printed budget chartsCheck up

    Get a home loan health check

    Not ready to switch? We check your rate, fees, offset and structure against the market and tell you what is worth changing.

    Is this you?

    This is for you if you have not looked at your loan in a while, your circumstances have changed, or you simply want to know whether you are on a fair deal. Bring your last statement and we do the comparison.

  • Sandstone cottage with a red roof behind a brick fenceInvest

    Buy an investment property

    Keep your home and use it to help fund an investment. We set up the loans so the debts stay separate and easy to track.

    Is this you?

    This is for you if you want a second property that earns rent. Lenders assess the rent, your income and both loans together, and the structure you pick now shapes what you can do next. Talk to your accountant about tax before you buy.

  • Modern white kitchen with a marble benchtopRenovate

    Renovate or extend your home

    Fund a kitchen, an extension or a knock down rebuild with equity, a top up or a construction style loan.

    Is this you?

    This is for you if you love the area but the house no longer fits. Small jobs can often come from equity or a top up; bigger structural work may need a loan that pays the builder in stages. We match the loan to the scope.

  • Modern two-storey house with a lit entry and garage at duskUpgrade

    Buy before you sell

    Found your next home before the current one has sold? A bridging loan covers the gap between the two settlements.

    Is this you?

    This is for you if you are upsizing or moving and do not want to rent in between. Lenders look at your peak debt while you own both homes and your end debt once the first one sells. We map both before you sign.

Buying your first home instead? See all home loans or book a free strategy call and we will point you to the right place.

Which one fits you

Which Loan Fits Your Situation?

Find the line that sounds like you. Each one points to the page that covers it, and the button sends your details to Sumit with that goal already ticked.

  • If this is you

    Your rate has not been reviewed in two years, or your fixed term ends soon

    Start with Refinancing. Switching lenders, break costs and the paperwork.

    Review my loan
  • If this is you

    You are not sure your loan is still a fair deal and want a check before you change anything

    Start with Home loan health check. Rate, fees, offset and structure against the market.

    Check my loan
  • If this is you

    You want to free up cash or a deposit from the value you have built

    Start with Using your equity. Usable equity, valuations and top up or split loans.

    Check my equity
  • If this is you

    You want to keep your home and buy a property to rent out

    Start with Investment loans. Loan structure, rental income and your next purchase.

    Plan my investment
  • If this is you

    You want to renovate, extend or rebuild the home you are in

    Start with Renovation loans. Equity, top ups and staged payments to your builder.

    Price my renovation
  • If this is you

    You are buying your next home before the current one sells

    Start with Bridging loans. Peak debt, end debt and the timeline between settlements.

    Plan my move

More than one fits? That is common. A refinance, an equity release and an investment purchase can often happen in one plan. Ask Sumit to map the whole plan.

Sumit · 1:18
Cheaper rate or the right strategy?Sumit Joshi, RyRo Loan Centre · cheaper rate or the right strategy

Buying a second home

How to Buy a Second Home When You Already Own One

To buy a second home, most owners use the equity in their first home for the deposit, then take a new loan for the rest. The lender checks your income against both loans, so work out your usable equity and borrowing power first, then decide whether to keep or sell the first home.

5 steps to a second home

  1. 01

    Work out your usable equity

    Lenders often count up to 80% of your home’s value, less what you still owe, as usable equity. That is a lender convention, not a rule.
    How usable equity is worked out

    Usable equity is the part of your home's value a lender will let you borrow against. A common starting point is 80% of the value less your current loan, because borrowing above 80% of the value usually brings Lenders Mortgage Insurance into play. Some lenders go higher with LMI; the valuation they order is what counts, not the estimate from a property website.

    Our guide to using equity to buy your next home walks through the maths step by step.

  2. 02

    Check what you can borrow with two loans

    The lender assesses your income against both debts. Rent from the first home counts, but usually not at the full amount.
    What changes when you hold two loans

    With two properties, the lender looks at your total debt, your living costs and a buffer on the repayments. If you keep the first home as a rental, most lenders count only part of the rent to allow for vacancies and costs. Run a first estimate with our borrowing power calculator, then we test it against the lenders that suit you.

  3. 03

    Decide: keep the first home or sell it

    Keeping it can grow your wealth but raises your debt. Selling frees the equity and simplifies things. The next section weighs both.
  4. 04

    Structure the loans before you sign

    Separate loans for each property keep the debts clear for you, your accountant and the next lender you deal with.
    Why structure matters

    How the loans are set up decides how easy it is to track interest, change lenders or sell one property later. We usually keep each property's debt in its own loan and avoid tying both homes to one lender where we can. Your accountant should look at the structure before you buy an investment.

  5. 05

    Get pre-approval, then buy with confidence

    Pre-approval tells you your budget and lets you bid or make offers knowing the finance side is in hand.
Map my second home plan

Free, no credit check.

Clients who upgraded with us

  • Varsha Mehra

    2 years ago on Google

    Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

    Varsha Mehra

    Google2 years ago on Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.
  • Guru Prasadh

    3 years ago on Google

    Google

    Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

    Guru Prasadh

    Google3 years ago on Google

    Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

Sumit · 1:14
Upgrading? Keep your first home or sell itSumit Joshi, RyRo Loan Centre · for upgraders

Upgrading

Keep Your First Home or Sell It?

There is no right answer for everyone. It comes down to whether you can carry both loans comfortably, what you need the equity for and how long you plan to hold.

Keeping it can suit you if

  • The rent and your income cover both loans with room to spare
  • You have enough usable equity for the new deposit and costs
  • You want to hold the property for the long term

Selling can suit you if

  • You need the sale money for the next home
  • A gap in rent would put you under pressure
  • You would rather have one loan and a simpler life

Want both options costed side by side? Ask Sumit to compare keep and sell with your real numbers.

House keys with a house-shaped key ring held up inside a front door
Moving up? Plan the finance for both homes before you sign.Photo: Jakub Żerdzicki / Unsplash
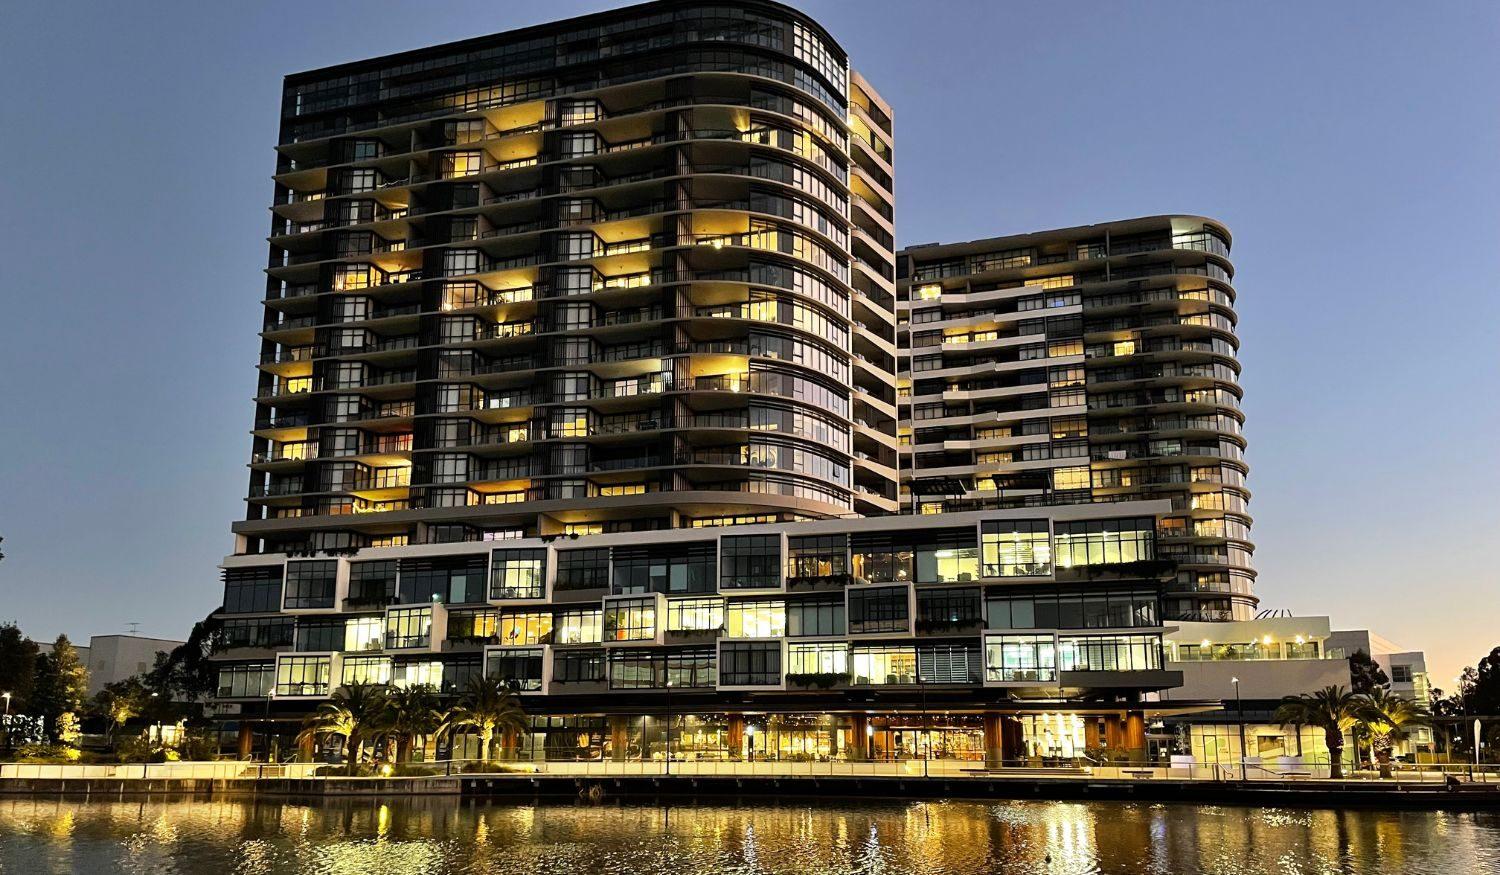
Tower A Esplanade building at Norwest at dusk, home of RyRo Loan Centre
Our office at Tower A, Norwest, in Sydney's Hills District.

Selling? See what you walk away with

Agent commission, marketing, legal costs and the loan payout come off the sale price. Check the cash you will have for the next deposit.
Open the full property selling costs calculator

Your sale

%
Mortgage to pay out?
More details(optional, 2)

Add styling, repairs and loan fees in the full property selling costs calculator.

Total selling costs

$31,983

2.7% of the $1,200,000 sale price

Net proceeds after the loan
$568,017
Cost breakdown
Agent commission
$24,000
Marketing and advertising
$6,000
Conveyancer or solicitor
$1,800
NSW discharge registration fee
$183
Sale price
$1,200,000
Less selling costs
-$31,983
Less loan paid out
-$600,000
Net proceeds after the loan
$568,017

Before settlement adjustments (council rates, water, strata) and moving costs. Capital gains tax may apply to an investment property: ask your accountant.

Figures last checked against:

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

Your current loan

Refinance, Equity or Both?

Refinancing changes who you borrow from or what you pay. Using equity changes how much you borrow. Plenty of owners do both in one step.

Refinance only

Same loan amount, a better rate, lower fees or features such as offset.
More detail

Worth a look if your loan has not been reviewed in two years or more, or your fixed term is ending. We weigh the saving against discharge fees, any break costs and LMI if your loan is above 80% of the value. See refinancing with a Sydney broker.

Equity release

Borrow more against your home, with your current lender or a new one.
More detail

Used for a deposit on another property, a renovation or a buffer. Keeping the extra in its own split makes it easy to track. Read about using the equity in your home.

Both at once

Move to a new lender and increase the loan in one application.
More detail

One valuation, one application and one settlement. It suits owners who want a sharper rate and money for the next step. We check whether a top up with your current lender is simpler before we recommend a switch.

Clients who refinanced with us

  • O D

    2 weeks ago on Google

    Google

    My wife and I are very happy and very greatful for all the help Sumit from RYRO LOAN CENTRE has helped us once again. We are so blessed to have had the opportunity to meet such a kind, hard working and wonderful person who will go above and beyond to get our home loan refinancing approved. So thank you very much summit. We will definitely be going back to RYRO team when we buy our next property. We will also recommend RYRO Loan Centre, especially Sumit to our family & friends! They are simply the BEST!! 😊

    O D

    Google2 weeks ago on Google

    My wife and I are very happy and very greatful for all the help Sumit from RYRO LOAN CENTRE has helped us once again. We are so blessed to have had the opportunity to meet such a kind, hard working and wonderful person who will go above and beyond to get our home loan refinancing approved. So thank you very much summit. We will definitely be going back to RYRO team when we buy our next property. We will also recommend RYRO Loan Centre, especially Sumit to our family & friends! They are simply the BEST!! 😊

  • gopichand paladugu

    a year ago on Google

    Google

    It's been an amazing experience working with Sumit, he helped me through initial Mortgage loan and recently in refinancing my loan. He helped me in every step of the process and patiently explained any questions we had. I strongly recommend him, if you are looking for mortgage broker services.

    gopichand paladugu

    Googlea year ago on Google

    It's been an amazing experience working with Sumit, he helped me through initial Mortgage loan and recently in refinancing my loan. He helped me in every step of the process and patiently explained any questions we had. I strongly recommend him, if you are looking for mortgage broker services.

Sumit · 0:52
What equity is, and how much you can useSumit Joshi, RyRo Loan Centre · equity and usable equity

Find out what your home can do for you

Tell us your loan, your home's rough value and your goal. Sumit compares the options and calls you back.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
Review my loan and equity

Free, no obligation. We generally respond within an hour.

Case studies

Three homeowners we helped restructure in 2026

Real clients, details kept private. The figures are from the loans we arranged; your rate and outcome depend on your circumstances.

Talk through my loan

Free, no obligation.

  • Refinance
  • Owner occupied
  • Fixed rate

Homeowners lock in two years of repayment certainty

Property value
$2.35M
Loan amount
$735K
2-year fixed rate
4.99%
  1. 1. The situation

    The clients owned their home, valued at about $2.35M, with a loan of around $735K.

  2. 2. What we did

    Reviewed fixed, variable and split options across our lender panel.

    +2 more in the full story

  3. 3. The result

    A known repayment for the next two years, which made the household budget easy to plan.

    +2 more in the full story

Read the full story

The situation

The clients owned their home, valued at about $2.35M, with a loan of around $735K. With rates rising through 2026 they wanted to stop guessing what their repayments would be from one month to the next.

What we did

  • Reviewed fixed, variable and split options across our lender panel.
  • Kept the loan at a similar amount (about $735K) so they were not borrowing more than they needed.
  • Moved the full loan to a 2-year fixed rate of 4.99%.

The result

  • A known repayment for the next two years, which made the household budget easy to plan.
  • Protection from any further rate rises during the fixed period.
  • A loan-to-value ratio of roughly 31%, which keeps their options open when the fixed term ends.

Rate shown is the rate this client received in 2026. Rates change often and depend on your circumstances, so yours may differ.

Google reviews

What Homeowners Say About Us

Real Google reviews of RyRo Loan Centre, word for word.

Google

5.0

From 360+ Google reviews

Sumit · 2:59
From two properties to four in six monthsSumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • Vandana Kanwar

    a year ago on Google

    Google

    Amazing service!!! Sumit always guided us about how to manage our finances and investments. He was always available to answer our questions- in person or over the phone. I recognise how time consuming this must be for him; but at no time has he made us feel that it was an inconvenience to him. He not only gave us the best product at the best rate, that suited our refinancing and investment needs but also made the whole process so easy and smooth. We highly recommend their services to anyone who is looking for a good and reliable mortgage broker.

    Vandana Kanwar

    Googlea year ago on Google

    Amazing service!!! Sumit always guided us about how to manage our finances and investments. He was always available to answer our questions- in person or over the phone. I recognise how time consuming this must be for him; but at no time has he made us feel that it was an inconvenience to him. He not only gave us the best product at the best rate, that suited our refinancing and investment needs but also made the whole process so easy and smooth. We highly recommend their services to anyone who is looking for a good and reliable mortgage broker.

  • Gurbaksh Dhillon

    2 years ago on Google

    Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

    Gurbaksh Dhillon

    Google2 years ago on Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

  • Sanjay Wadhwani

    2 years ago on Google

    Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

    Sanjay Wadhwani

    Google2 years ago on Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

  • Anshuman Bhardwaj

    2 years ago on Google

    Google

    Brilliant team and very responsive I am taking help of Sumit and his team for almost 10 years now from my first home to my 6th investment property . He is very helpful, ,informative and respectful to all my questions and needs. Always available and his Team (Dean) also is very knowledgeable . I have recommended them to lot of my friends and also heard good about them. Thanks team and keep up the good work

    Anshuman Bhardwaj

    Google2 years ago on Google

    Brilliant team and very responsive I am taking help of Sumit and his team for almost 10 years now from my first home to my 6th investment property . He is very helpful, ,informative and respectful to all my questions and needs. Always available and his Team (Dean) also is very knowledgeable . I have recommended them to lot of my friends and also heard good about them. Thanks team and keep up the good work

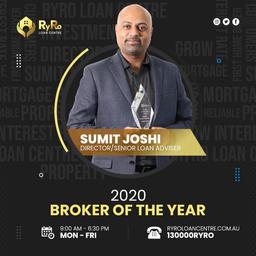
Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie
Sumit Joshi, 2020 Broker of the Year

Broker of the Year 2020Awarded to Sumit Joshi

Who you will deal with

The Ryro Team

Sumit Joshi JP · Principal broker · Credit Rep 446824

Most owners are sitting on options they have never been shown. My job is to lay them out and set the loans up so the next step is easy.

You deal with Sumit from the first call. He reviews your current loan, works out your equity, compares lenders across the panel and stays on it until settlement. Kathryn then works with your conveyancer and the lender so settlement day runs on time.

We work from the Norwest office and help owners across the Hills District and all of Sydney, in person or by phone and email.

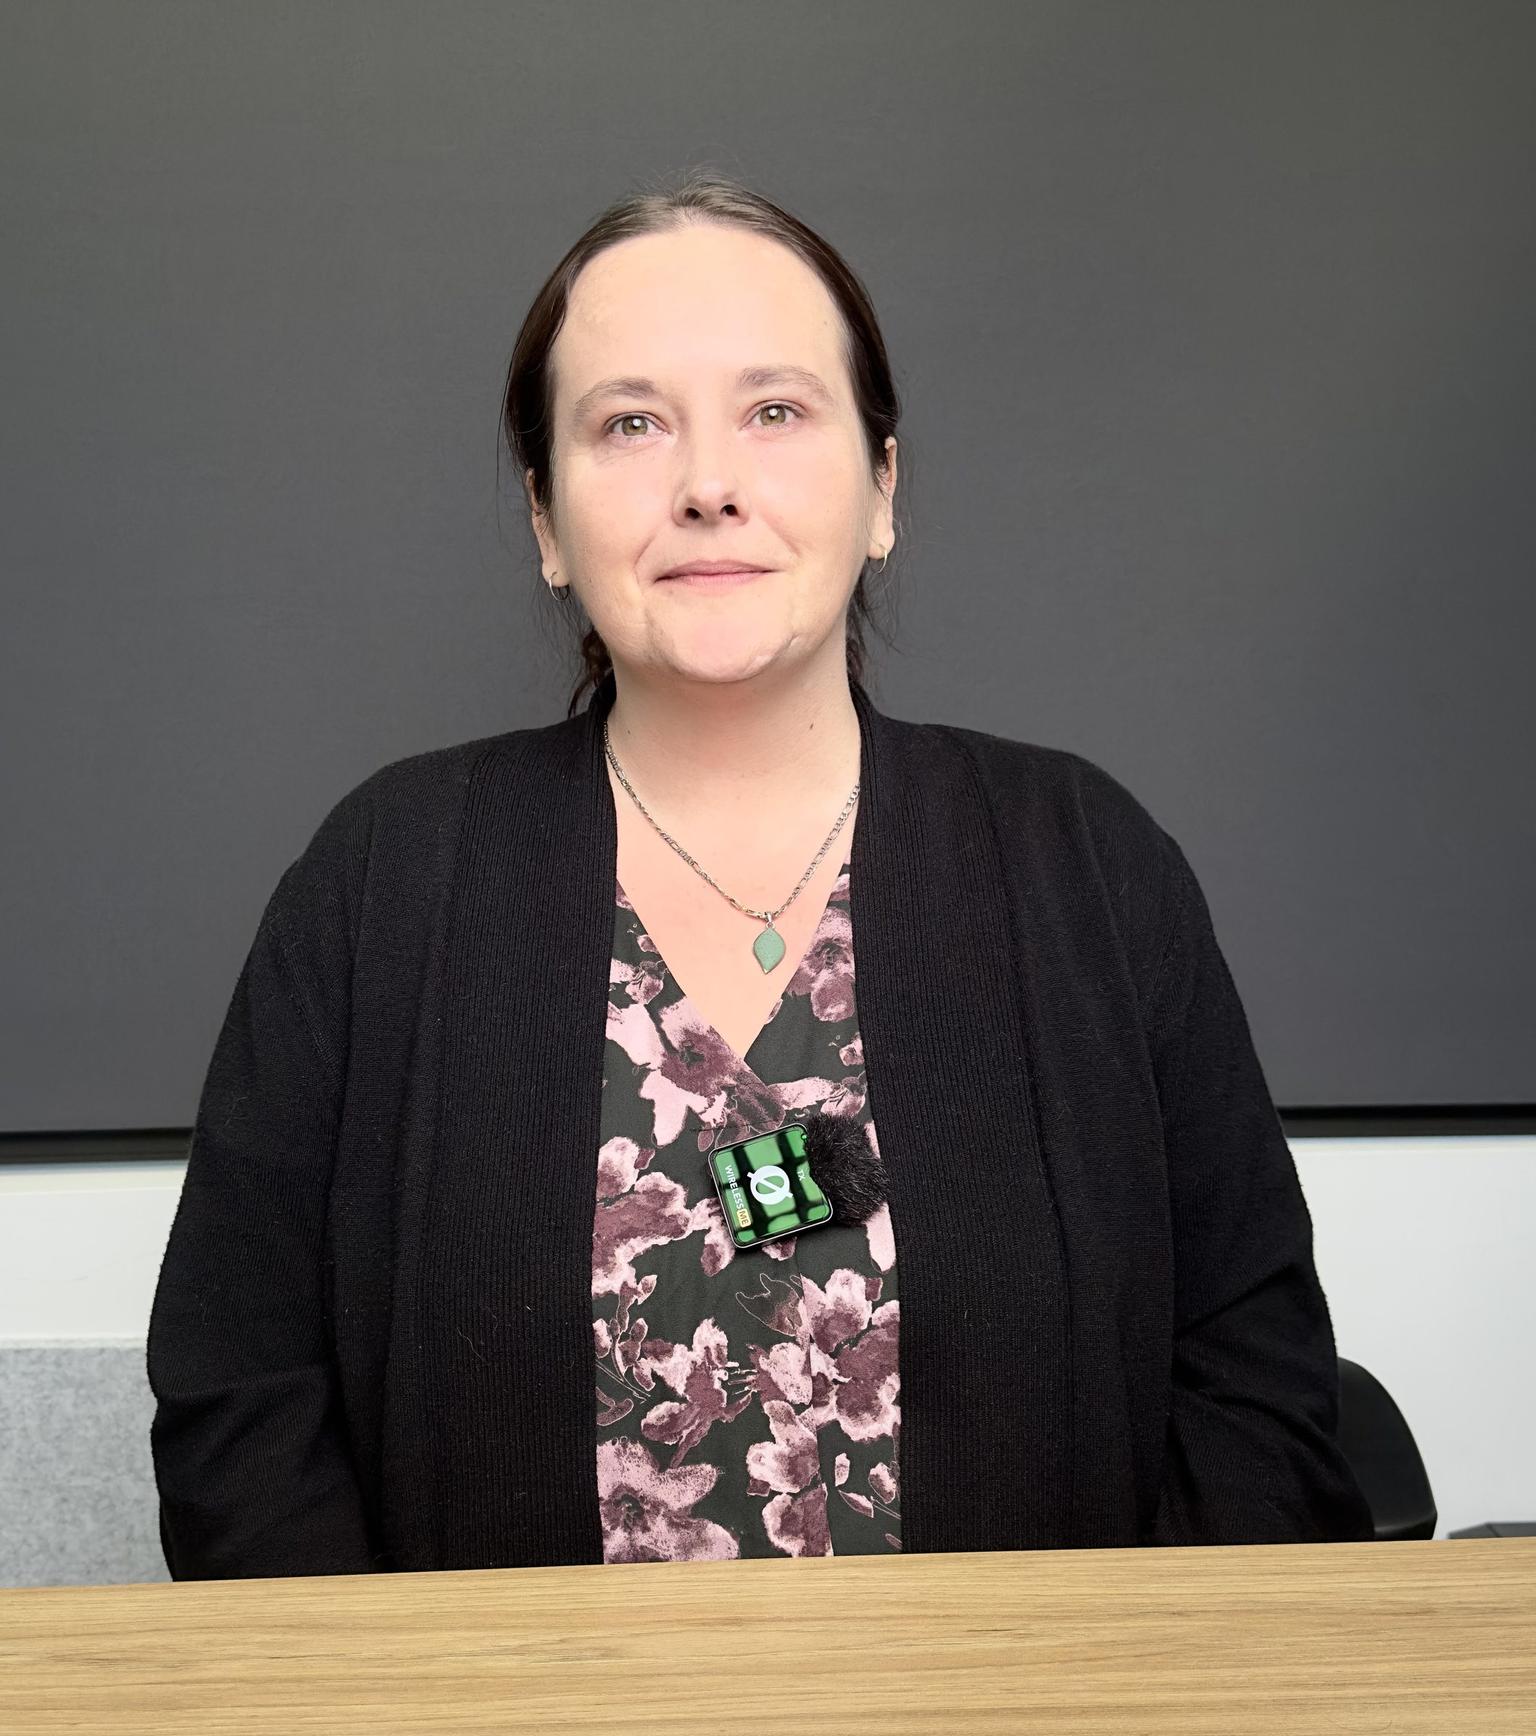
Kathryn Thomas, loan processor at RyRo Loan Centre

Kathryn ThomasSettlement and client liaison. Kathryn works with your conveyancer and the lender from exchange to settlement day.

  • We generally respond within an hour
  • Free strategy call, no obligation

Why Sydney borrowers choose RyRo

Rated by clients, recognised by lenders

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • MFAA 10 year member badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • AFG Excellence Awards finalist 2024 badge
  • AFG Excellence Awards finalist 2023 badge
  • AFG Excellence Awards finalist 2022 badge
  • AFG Award winner 2019 badge
  • AFG Award winner 2018 badge
  • AFG Award winner 2017 badge
  • AFG Award winner 2016 badge
  • AFG Award winner 2015 badge
  • AFG Award winner 2014 badge
  • AFG Award winner 2013 badge

AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026

Jagdeep Gill

a year ago on Google

Google

We had an absolutely outstanding experience with RyRo Loan Centre and I cannot thank Sumit enough for his incredible support throughout my investment loan process. It was very challenging process to get loan through SMSF but team made the whole process easy. RyRo Loan Centre is truly one of the best in the business and I cannot recommend them enough. Thanks Team

Jagdeep Gill

Googlea year ago on Google

We had an absolutely outstanding experience with RyRo Loan Centre and I cannot thank Sumit enough for his incredible support throughout my investment loan process. It was very challenging process to get loan through SMSF but team made the whole process easy. RyRo Loan Centre is truly one of the best in the business and I cannot recommend them enough. Thanks Team

Read all 360+ Google reviews

Answers on demand

Frequently Asked Questions

Answers to common questions about home loans, deposits, approval times, refinancing and upsizing, and how we help Sydney and NSW borrowers.

10 answers in 3 topics

Buying a second home

  • It can be, if the numbers work with room to spare. A second property can grow your wealth through rent and long term growth, but it adds debt, costs and risk. Before you commit, check that you can cover both loans if rates rise or the property sits empty for a while, and talk to your accountant about tax. We map the borrowing side for you.

    Investment property loans
  • Enough to cover the deposit and buying costs on the new property, such as stamp duty. Lenders often let you use up to 80% of your current home’s value less your loan, and more with LMI. The exact amount depends on the lender’s valuation, your income and how much you want to borrow in total.

    Using your home equity
  • Yes. Many owners use the equity in their first home for the deposit and keep it as a rental or a holiday home. The lender assesses both loans against your income. If you plan to sell the first home later, a bridging loan can cover the time you own both.

    Bridging loans
  • Keep it if the rent and your income cover both loans comfortably and you want to hold for the long term. Sell it if you need the cash for the next home, want a smaller debt or would struggle to cover a gap in rent. Tax, costs and your plans all matter, so get your accountant’s view too.

Your current loan

  • Yes. You can move to a new lender and increase the loan in one application, as long as the new lender’s valuation and your income support it. Some people keep the extra amount in a separate split so it is easy to track. We check whether staying with your current lender and topping up is the simpler option.

    Our refinancing service
  • A bridging loan lets you settle on your new home before the current one sells. During the bridging period you carry the peak debt, which is both loans combined. Once your old home sells, the sale proceeds pay down the loan to the end debt. Lenders set a time limit for the sale, so plan the timeline with us before you sign.

    Bridging loans guide for upgraders
  • Usually, yes. Smaller jobs can often be funded with equity through a top up or a split loan. Larger structural work, such as an extension or a knock down rebuild, may need a loan that pays the builder in stages as the work is done. The lender may value the home on its finished value for larger jobs.

    Renovation loans
  • A free review of the loan you already have. We compare your rate, fees and features such as offset against what lenders offer today, check that the structure still suits you, and tell you whether refinancing, repricing with your lender or staying put makes the most sense. Bring your latest statement.

    Home loan health check

Tax and costs

  • We are a broker, not a tax adviser, so we do not give tax advice. Tax on a second property depends on how you use it, whether it is rented and how long you hold it. Speak to your accountant before you buy, and read the ATO’s guidance on the main residence exemption. We then set up the loans to match the plan your accountant gives you.

  • No. RyRo Loan Centre charges $0 broker fees on home loans, including refinancing and equity releases, because the lender pays us when a loan settles. The review and strategy call are free, and if your current loan is already a good deal we will tell you to keep it.

View all FAQs

From the blog

Guides for Homeowners

The questions owners ask us most: how equity works when you buy again, whether to rent out the first home, and how to buy before you sell.

Free PDF · 12 pagesChecked August 2026
Photo: Andrew Bright / Unsplash

Free 12-page guide

Sydney Upsizer's Move Planner 2026

Moving up is two property deals running at once. Every cost on both sides, your usable equity, and whether to sell first or buy first.

  • A buy and sell cost worksheet
  • Usable equity, worked line by line
  • Sell first or buy first: a decision tree

Google5.0 from 360+ Google reviews · Emailed to you straight away

Talk to Sumit

Ready to Put Your Home to Work?

Join 2,500+ Australians who've trusted RyRo Loan Centre with their lending. $0 fees. Expert advice. No credit check.
Sumit Joshi, principal broker at RyRo Loan Centre

Plan My Next Move

We'll call you to talk through your loan and your goal. No obligation, no credit check.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reads your details and calls you back
  • No obligation and no credit check
  • Free for home loans: the lender pays us
Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Lenders on our panel
50+
“Sumit has been amazing through the whole process of refinancing our home loan. So professional and friendly. I highly recommend him to anyone who is looking for a mortgage broker!”
Annaliza Benitez · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026.

Get my free loan review