Daljeet Singh
9 months ago on Google

I have wonderful experience with them they are professional,quick and accurate in terms of loan requirements
Mortgage brokers in Norwest, helping the Hills District and Sydney
Chattel mortgage finance, RyRo Asset Finance
Buying a vehicle or machine for your business? Rohan Joshi at RyRo Asset Finance compares chattel mortgage lenders for your ABN, your paperwork and your asset, then handles the application for you.
5.0 from 13 Google reviews for RyRo Asset Finance
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Updated November 2026
Chattel mortgage explained
A chattel mortgage is the most common way Australian businesses finance a vehicle or piece of equipment. The lender pays for the asset, your business owns it from day one, and the lender holds security over it until the chattel loan is repaid.
Step 1
A new or used vehicle, truck, machine or piece of equipment, from a dealer or, with some lenders, a private seller.
Step 2
The lender pays the seller in full. The asset is in your business name from that day.
Step 3
Its interest is recorded on the Personal Property Securities Register (PPSR) until the loan is repaid.
Step 4
Weekly, fortnightly or monthly over a fixed term, with an optional balloon left to the end.
Step 5
After the last payment, including any balloon, the security is removed and the asset is clear.
Quick answer
A business loan to buy a vehicle or equipment, where your business owns the asset from the start and the lender takes a mortgage over it as security. You repay it over a set term, often with a balloon at the end.

Want the long version? Read our chattel mortgage guide.

Chattel finance for business owners
A chattel mortgage fits a business that wants to own the asset and use it mainly for work. These are the owners Rohan helps most often.
A ute, van or trailer you use on the job every day, financed by the business that earns from it.
A prime mover, tipper or light truck, from your first truck to the next one in a growing fleet.
Excavators, loaders, bobcats and attachments, new or used, where the machine is the security.
Companies, trusts and sole traders buying a work car, workshop gear or practice equipment.
Buying mostly for personal use? A consumer car loan is usually the better fit. For every type of business asset, see our asset finance broker page.
Compare your options
The big difference is who owns the asset during the loan. That one point changes the GST, the tax treatment and what happens at the end.
| Chattel mortgage | Finance lease | Hire purchase | Car loan | |
|---|---|---|---|---|
| Who owns it | Your business, from day one | The lender; you rent it | The lender, until the last payment | You, with the lender holding security |
| Best for | Business assets you want to own | Using an asset without owning it | Owning at the end of the term | Mainly personal use |
| End of term | Pay any balloon; asset is clear | Pay the residual, return or upgrade | Final payment; ownership passes | Pay any balloon |
| GST | May be claimable on the price | Included in each rental | Depends on how you account for GST | Usually not relevant |
| Assessed on | Your business | Your business | Your business | Your personal income |
General information. Tax treatment depends on your business; ask your accountant.
Weighing a lease? Our finance lease and commercial hire purchase page covers the rental side. For the side by side detail, read chattel mortgage vs hire purchase on our asset finance page.
Rohan explains each structure for your asset.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Chattel mortgage loans
Any movable asset your business uses mainly for work can be a chattel. The asset is the security, so lenders look closely at its type, age and resale value.
Light trucks, tippers, prime movers and trailers for owner-drivers and fleets.
Excavators, loaders, bobcats and other plant for building and earthmoving work.

Work vehicles used mainly for the business, including canopies and fit-outs where the lender allows.
Manufacturing, workshop, medical and dental equipment that earns its keep in the business.
Tell Rohan the asset, price and age.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Balloon payments
A balloon (or residual) is a lump sum left owing at the end of the term. It lowers your regular repayments, which helps cash flow while the asset earns. The trade-off is more interest overall, because that part of the loan is never paid down during the term.
When it falls due you can pay it out, refinance it, or sell or trade the asset to clear it. How large a balloon a lender allows depends on the asset, its age and the term, so Rohan checks it against what the asset is likely to be worth at the end.
Less is repaid each period, freeing up cash for the business.
The balloon carries interest for the whole term.
Pay it, refinance it or trade the asset. Decide before you sign.
Estimated repayment per month
$1,437.75
60 monthly repayments paid in advance, then a balloon of $16,000
GST in the price: $7,273
One eleventh of a GST-inclusive price. A GST-registered business may be able to claim GST on a business asset as a credit on its BAS. Whether you can, how much and when depends on your business use and how you account for GST. We recommend consulting your accountant.
Estimate only, not a quote or tax advice. It leaves out fees and charges, and the rate is the one you type in. Your real repayment depends on the lender, the asset and your business.
Figures last checked .
This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.
Free, no obligation. Your numbers go with your enquiry.
5.013 RyRo Asset Finance reviews
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Want to compare more scenarios? Open the full chattel mortgage calculator.
5.0 from 13 Google reviews for RyRo Asset FinanceRyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.

GST and tax
Because the business owns the asset from the start, the ATO treats a chattel mortgage as a purchase. A GST-registered business that holds a tax invoice can generally claim the GST in the price as a credit, and as the owner it may be able to claim depreciation and interest for the business share of use.
How much, and when, depends on your business. Ask your accountant these questions before you sign.
The ATO explains that under a chattel mortgage the purchaser takes title from the time of purchase, and sets out when the GST credit can be claimed for cash and non-cash accounting. See the ATO pages on when you can claim a GST credit and GST on hire purchase and leasing. Checked November 2026.
Chattel mortgage finance
Every lender sets its own rules, but most look at the same things. Knowing them before you apply means one clean application rather than several enquiries on your credit file.
Daljeet Singh
9 months ago on Google
I have wonderful experience with them they are professional,quick and accurate in terms of loan requirements
Free, no obligation.
Self employed with paperwork gaps? See low doc options for ABN holders.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Sound familiar?
Most business owners come to Rohan with one of these. Here is what usually gets in the way, and what we do about it.
5.0 from 13 Google reviews for RyRo Asset Finance
The challenge: The dealer offered a chattel mortgage on the spot, with a balloon and fees you have not compared.
Bring the quote. Rohan compares it with other lenders and explains the balloon, fees and payout terms in plain English.
The challenge: Your business is new, so the first lender you tried wanted two years of trading.
We look for lenders that weigh your time in the industry, deposit and credit file, not only ABN age.
The challenge: You already have loans on other vehicles or machines and want to add one more without stalling.
We look at your existing commitments and find a lender comfortable with the whole fleet, not just the new asset.
The challenge: The lump sum on your current loan is due soon and paying it out in one go would hurt cash flow.
We look at refinancing the balloon, or trading the asset and rolling into new finance, before the due date.
These are common situations, not client stories. Every loan depends on your circumstances and the lender's policy.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
How it works
Step 1
The asset, its price, your ABN and how you use it. Two minutes on the form.
Step 2
He matches your business, paperwork and asset to lenders whose rules fit, before any application.
Step 3
You see the repayments, balloon and fees in writing. Rohan prepares and lodges one application.
Step 4
Once approved and signed, the lender pays the seller and the asset is yours to put to work.
Step 1 takes about two minutes.
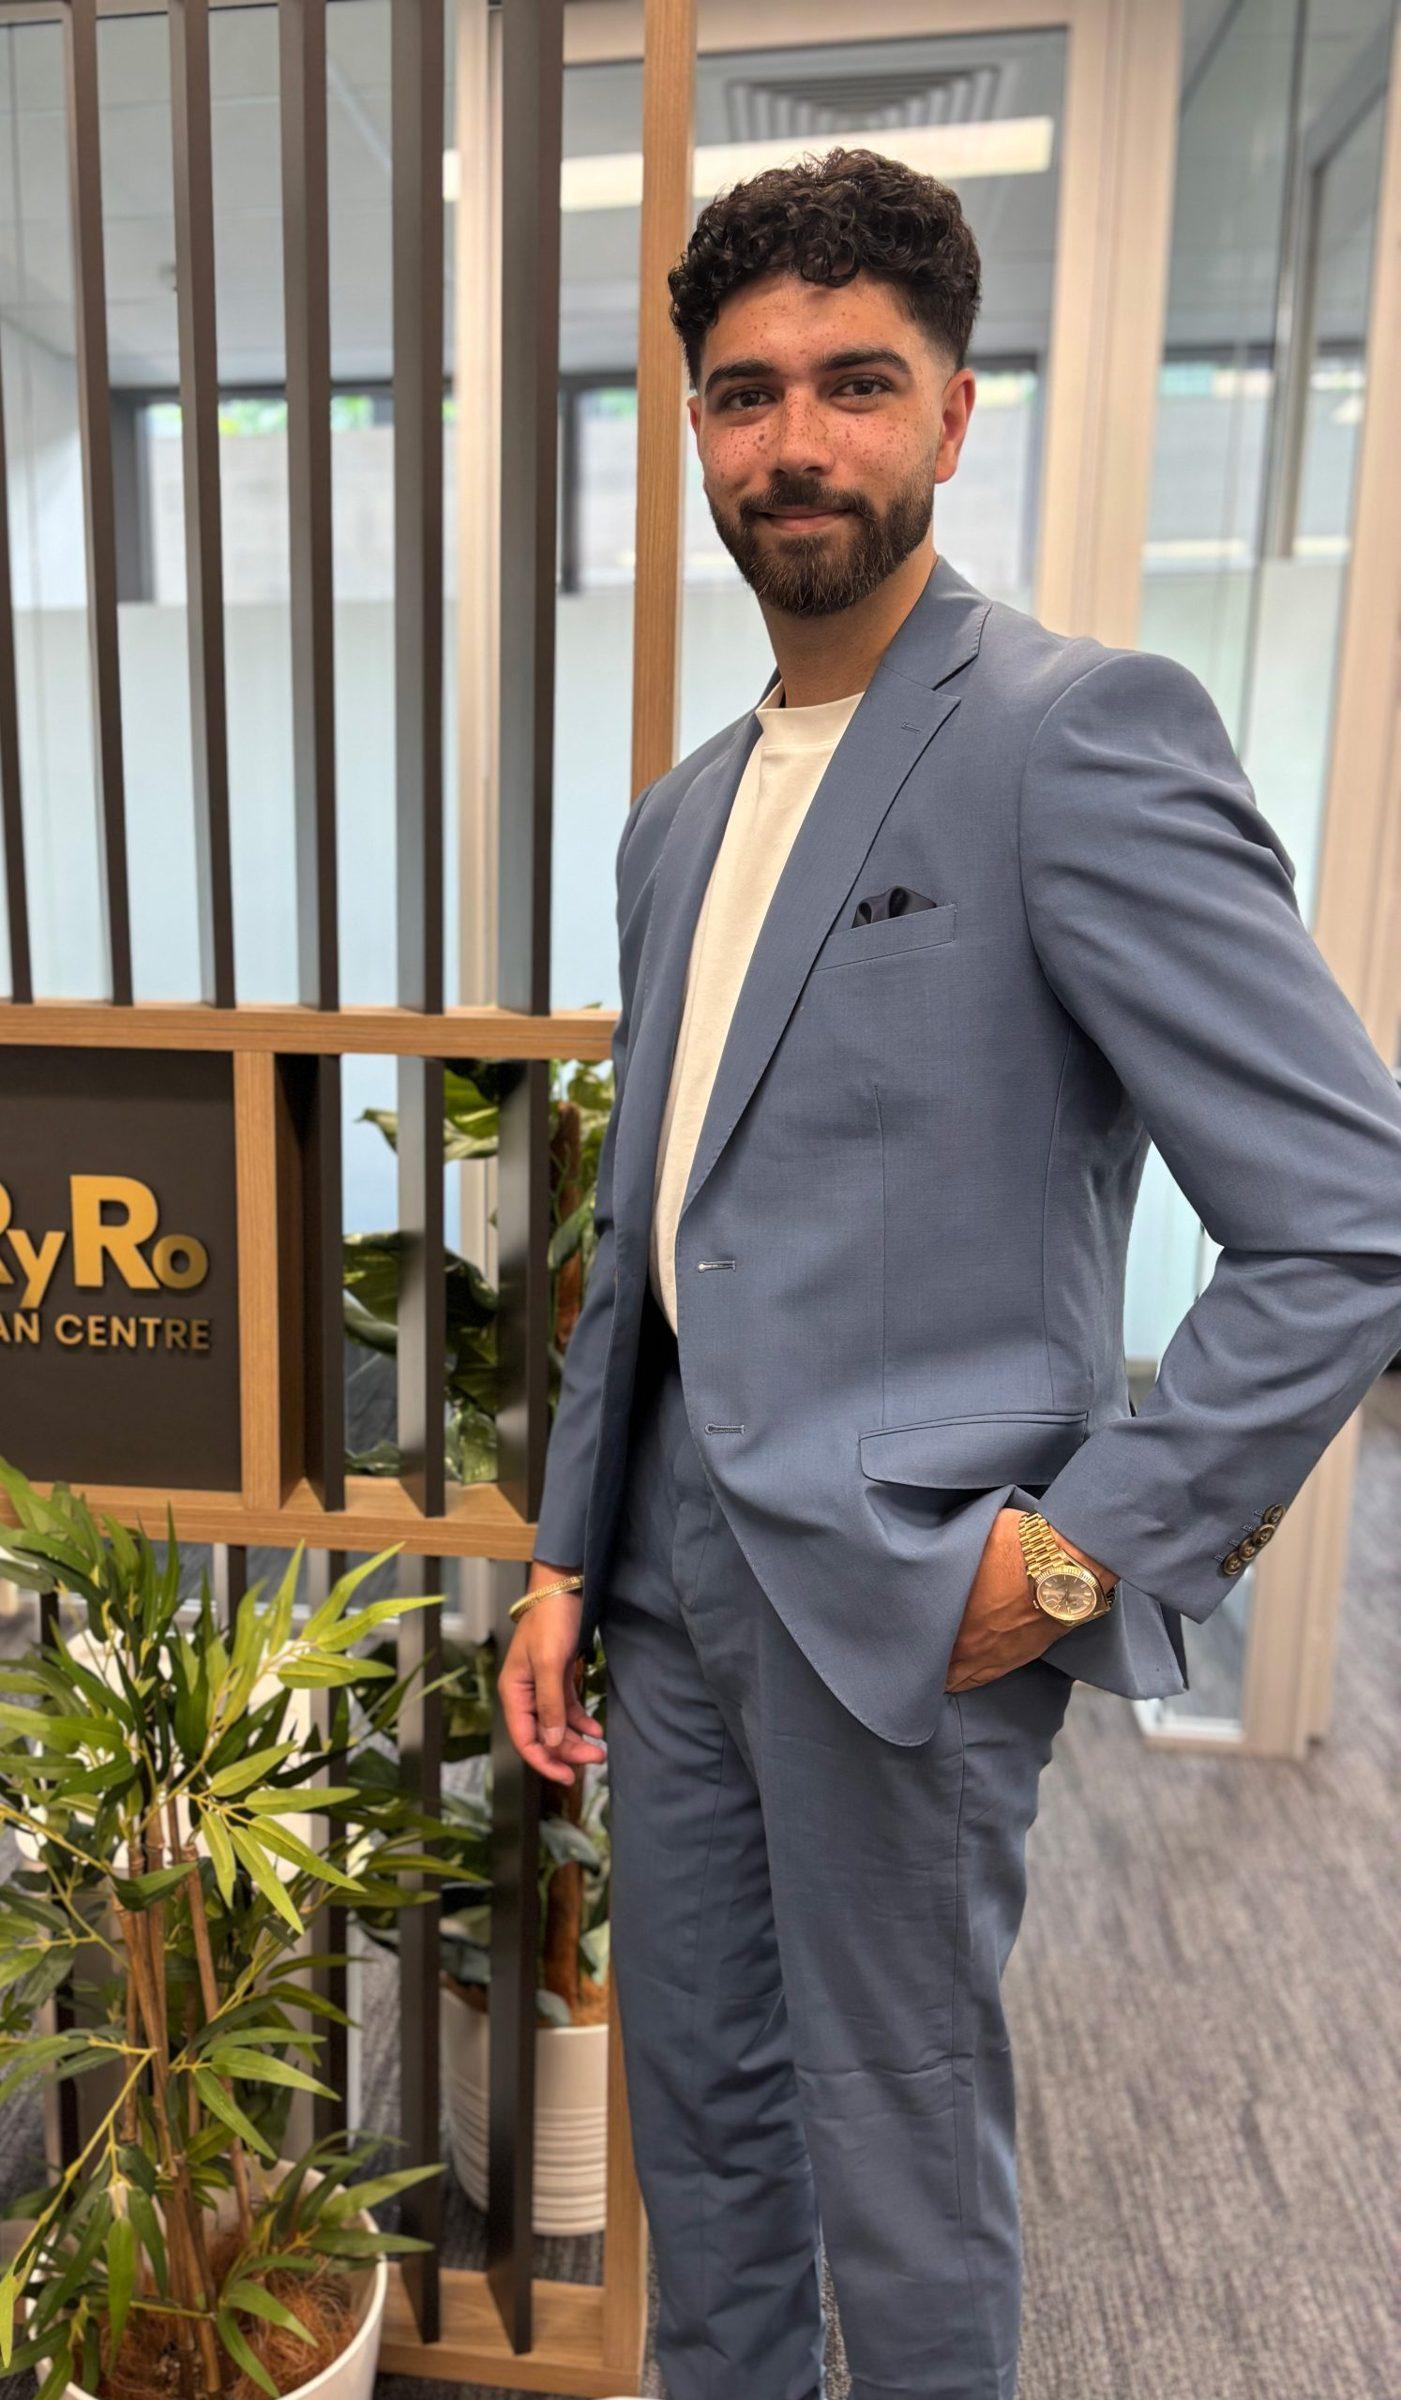
Rohan Joshi
Asset finance broker, RyRo Asset Finance, ACR 565295
Who you will deal with
You deal with one person. Rohan reads your details, works out whether a chattel mortgage, lease or hire purchase fits, compares lenders and keeps you updated until the asset is in your hands. His clients mention the same things in their Google reviews: clear explanations, quick answers and simple paperwork.
RyRo Asset Finance is a separate company from RyRo Loan Centre, working from the same office as our Norwest mortgage brokers. If you also need a home or commercial loan, Sumit and the RyRo Loan Centre team look after that.
Free, no obligation.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Google reviews
Real Google reviews of RyRo Asset Finance, word for word.
5.0
From 13 Google reviews for RyRo Asset Finance
krunal shah
11 months ago on Google
Thank you for your support to get my business car loan done in 1 day. Highly recommend
Rayen Naidoo
2 months ago on Google
I engaged Ryro Finance to arrange finance for my vehicle, and the experience was excellent. They didn’t just compare car loan options—they took a holistic approach by considering my future financial goals and any upcoming asset purchases to ensure the finance structure suited my long-term plans. They provided valuable advice on the ideal deposit amount, explained the best approach to financing a vehicle, and secured one of the most competitive interest rates available to me. I would highly recommend Ryro Finance, not only for vehicle finance but for any financing requirements. Their personalised advice, professionalism, and long-term financial planning set them apart.
Mark Donovan
a month ago on Google
Rohan provided exceptional service, was communicative and transparent through the entire process. I ended up with a far better deal than I would have got on my own.
Sumit Garg
a year ago on Google
Rohan been nothing short of excellent for us. Being proactive, professional and keeping things very simple and easy to deal with. Gave us an excellent deal and whole process was easy as. Thank you for being so helpful is getting us over the line in getting the new car
Keep reading
Our chattel mortgage guide goes deeper on how the loan is set up. The comparison checklist helps you test a dealer quote before you sign.
Free 2-page guide
Car loan, novated lease, dealer finance or chattel mortgage: compare the real cost, not the advertised rate, before you sign.

From Rohan Joshi, RyRo Asset Finance
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Talk to Rohan
We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.
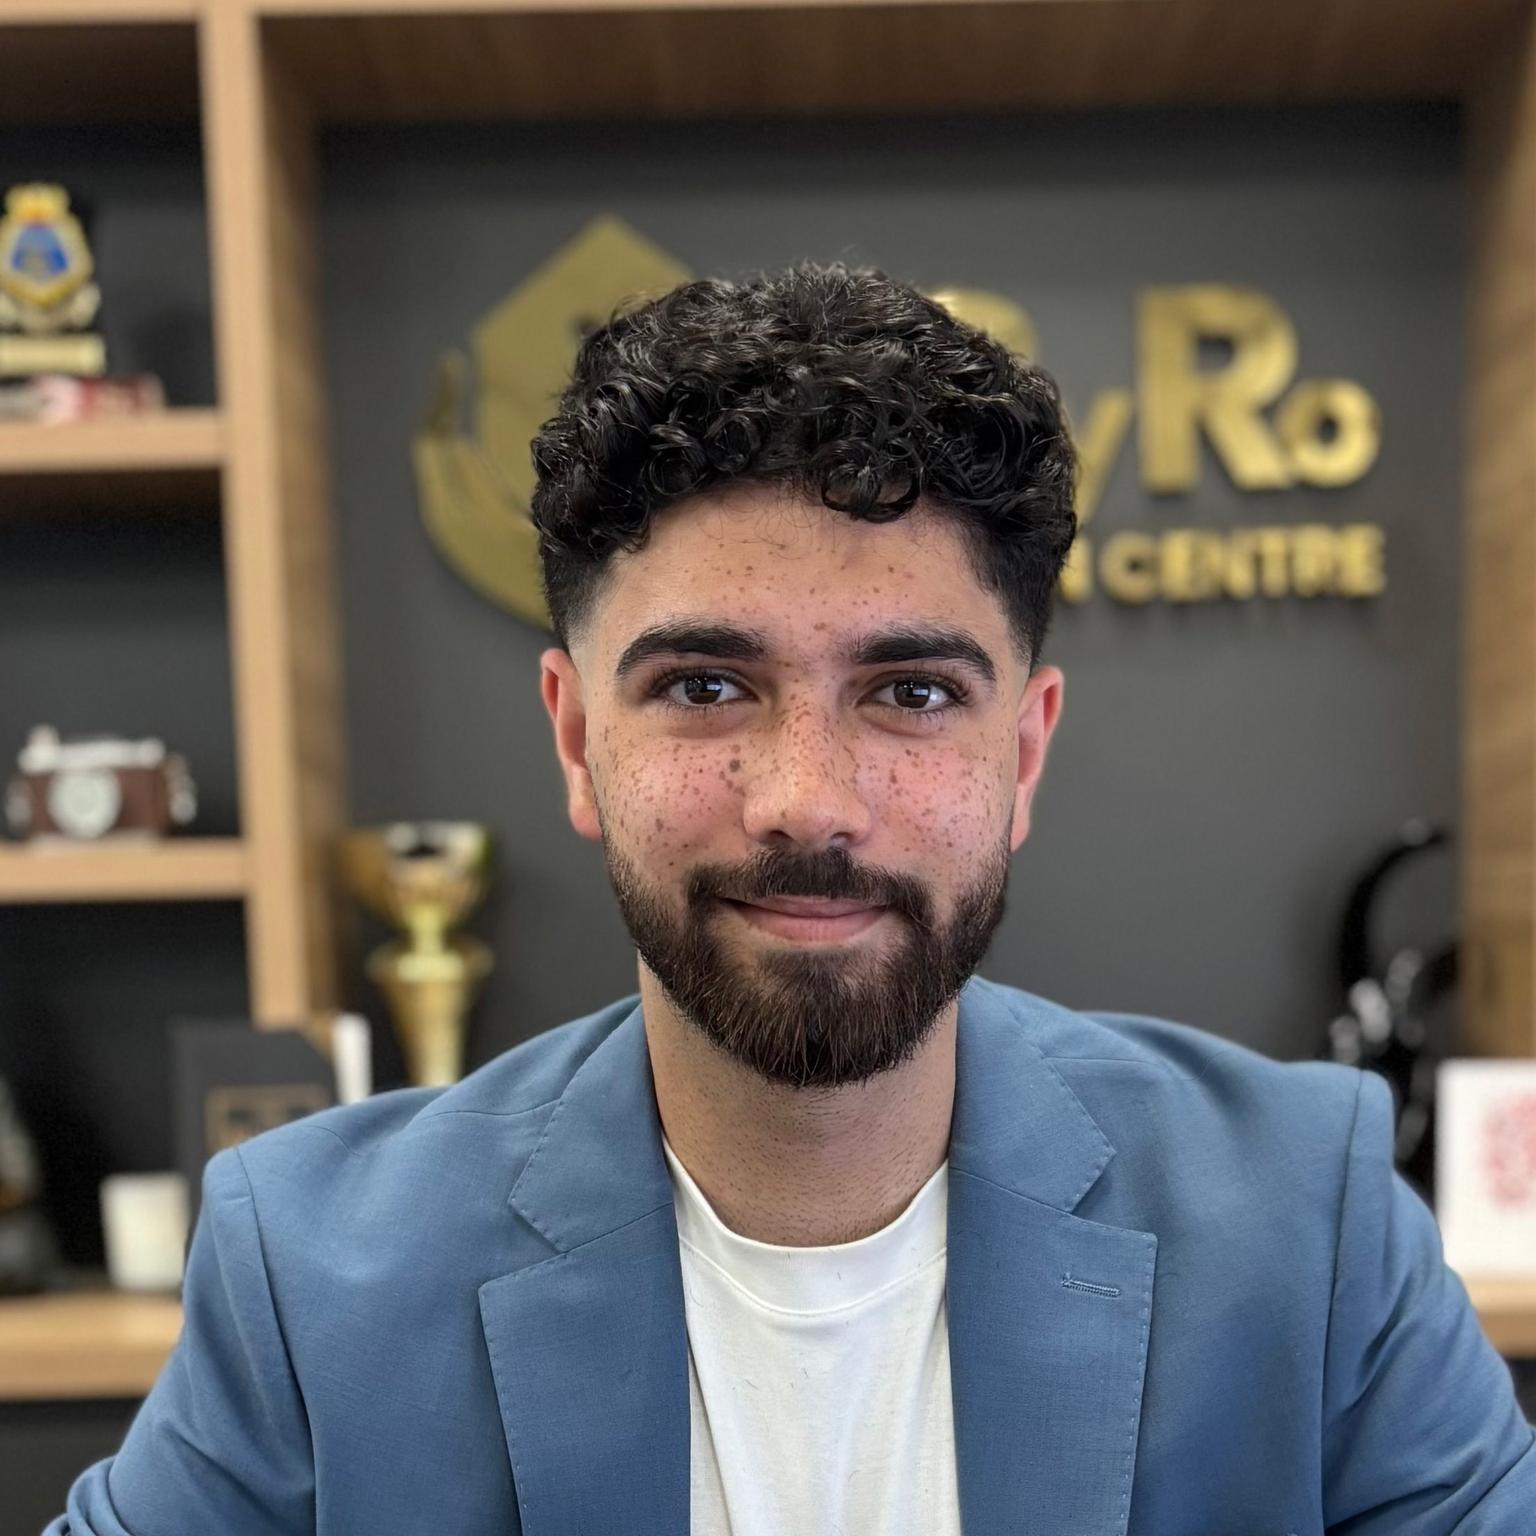
Rohan Joshi
Asset finance broker, RyRo Asset Finance
More videos from Rohan
“I had an excellent experience with Rohan for my car loan. He was professional, responsive and extremely helpful throughout the entire process. He explained all the options clearly, found a competitive loan that suited my circumstances and made the paperwork simple and stress-free. I highly recommend RYRO services to anyone looking for a reliable and trustworthy car loan broker.”
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.