RyRo Loan Centre

Home loan health check, Sydney

Free home loan health check for Sydney homeowners

Has your home loan been left alone for a while? Sumit checks your rate, fees, offset, structure and fixed rate expiry against what lenders offer today, then tells you plainly whether to stay, reprice, refinance or restructure.

Sumit Joshi, principal broker at RyRo Loan Centre

Get your free home loan health check

Tell Sumit about your loan. He reviews it and calls you back. No obligation.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Your loan checked against 50+ lenders
  • A clear answer, even if it is "stay where you are"
  • Free, no obligation and no credit check
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

Home loan health check, updated November 2026

What is a home loan health check?

A home loan health check is a free review of the loan you already have. Sumit compares your rate with what lenders offer borrowers like you today, then checks your fees, offset, structure, fixed rate expiry, equity and other debts.

It is not a sales pitch to refinance. Plenty of health checks end with a better rate from the lender you already have, or a small change such as an offset set up properly. If a switch does pay, our refinancing service handles it.

  • A review, not an application

    We work from your statements. Nothing goes to a lender and nothing touches your credit file unless you decide to apply.

  • Your loan against the panel

    Priced across 50+ lenders, including your own, for your loan size, equity and income.

  • A plain answer

    Stay, reprice, refinance or restructure, with the numbers behind it and the costs of any change set out first.

Quick answer

How often should I review my home loan?

Once a year, and any time something changes: a fixed rate about to end, a rate rise, a new job or baby, or plans to renovate or invest. A loan nobody has looked at for two years or more is the one most worth checking.

Weatherboard cottage behind a white picket fence
Your home has probably changed in value since you took the loan. Your loan may not have kept up.Photo: Paddy Pohlod / Unsplash

The check

What we check in your home loan health check

Eight things, in plain English. Rate is only one of them. The structure, the offset and what you plan to do next often matter as much.

Yoni Marlow

5 years ago on Google

Google

Working with Sumit has been the best. I’ve made three purchases using Sumit as my broker. Further more he is always available to work on getting better rates from the bank during the duration of the loans. Definitely recommend!

  • Your rate against today

    We price your loan size, equity and income across our lender panel, so you see how your rate compares for a borrower like you right now.

  • Fees you may not need

    Annual package fees, account fees and offset fees. We check whether each one still earns its keep on the way you use the loan.

  • Offset and redraw

    Is your spare cash actually in the offset? Is it a full offset? We check how the offset and redraw work and whether you use them well.

  • Structure and splits

    Principal and interest or interest only, fixed and variable splits, and whether home and investment debts sit in separate loans.

  • Fixed rate expiry

    When your fixed term ends, what it rolls onto, and whether to plan a rollover, a new fixed term or a switch before it does.

  • Your LVR and LMI position

    If your home has grown in value, your loan to value ratio may have dropped. That can open better pricing, or show where LMI would apply again.

  • Debts to consolidate

    Car loans, credit cards and personal loans. We look at whether rolling them in helps, and what a longer term would cost you in interest.

  • Borrowing power for what is next

    Renovating, investing or upgrading soon? We check what you could borrow, so the loan you keep today does not block the next move.

Check my home loan

Free, no obligation. Sumit reads every enquiry.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824

Two minute check

Tick through your own home loan check

Read each line and see how many are true for you. If two or more are not, your loan is worth a proper look.

  • I know the rate I pay today, not the one I started on.It is on your latest statement or in your banking app.
  • I know if and when my fixed rate ends.And what rate the loan rolls onto after that.
  • My spare cash sits in a full offset account.Savings in an everyday account do not reduce your interest.
  • I know what fees I pay on the loan each year.Package, account and offset fees all count.
  • My home and investment debts are in separate splits.Mixing them can make the tax side harder. Ask your accountant.
  • I have a rough idea what my home is worth now.More equity can mean better pricing.
  • I have no card or car loan costing far more than my home loan.High interest debts are worth a look.
  • I know what I could borrow if I wanted to renovate, invest or upgrade.It changes as your income and debts change.

Two or more you could not tick? Let Sumit check it for you.

Get my free check

What happens next

Three ways a home loan health check can end

We tell you which one fits, with the numbers behind it. Any change that costs more than it saves, we tell you not to make.

  • Hands signing loan paperwork at a desk
    Stay, switch or restructure: the paperwork only starts once you decide.Photo: Scott Graham / Unsplash
  • Outcome 1

    Stay and get your rate repriced

    If your lender is still a good fit, we help you ask for a sharper rate. Knowing what other lenders would offer makes that request much stronger.

  • Outcome 2

    Refinance to a better deal

    If another lender comes out ahead after switching costs, our home loan refinancing team runs the whole switch for you, from application to discharge.

  • Outcome 3

    Restructure what you have

    Add an offset, split the loan, fix part of it, or release home equity for a renovation or an investment, often without changing lenders.

Case studies

Where a loan review has led for our clients

Three real files from 2026. One couple refixed for certainty, one moved off low doc pricing they no longer needed, and one released renovation money without refinancing the existing loans. Client details are private; the numbers are real.

Review my loan

Free, no obligation.

  • Refinance
  • Owner occupied
  • Fixed rate

Homeowners lock in two years of repayment certainty

Property value
$2.35M
Loan amount
$735K
2-year fixed rate
4.99%
  1. 1. The situation

    The clients owned their home, valued at about $2.35M, with a loan of around $735K.

  2. 2. What we did

    Reviewed fixed, variable and split options across our lender panel.

    +2 more in the full story

  3. 3. The result

    A known repayment for the next two years, which made the household budget easy to plan.

    +2 more in the full story

Read the full story

The situation

The clients owned their home, valued at about $2.35M, with a loan of around $735K. With rates rising through 2026 they wanted to stop guessing what their repayments would be from one month to the next.

What we did

  • Reviewed fixed, variable and split options across our lender panel.
  • Kept the loan at a similar amount (about $735K) so they were not borrowing more than they needed.
  • Moved the full loan to a 2-year fixed rate of 4.99%.

The result

  • A known repayment for the next two years, which made the household budget easy to plan.
  • Protection from any further rate rises during the fixed period.
  • A loan-to-value ratio of roughly 31%, which keeps their options open when the fixed term ends.

Rate shown is the rate this client received in 2026. Rates change often and depend on your circumstances, so yours may differ.

Timing

When to get a home loan health check

Any time is fine. These four moments are when a check is most likely to find something worth changing.

  • Your fixed rate is ending

    When a fixed term ends, the loan usually rolls onto a variable rate you did not choose.

    What we check first

    The roll-off date and rate, your lender's rollover offer, and whether to refix, go variable or move. Start a few months before the end date so there is time to compare.

  • Rates have just gone up

    A cash rate rise flows into your repayments. It is a good time to see where your rate sits now.

    What we check first

    How your rate compares for your profile today, whether an offset or extra repayments could soften the rise, and whether your lender will reprice.

  • Life has changed

    A new baby, a new job, a separation, starting a business or planning a renovation all change what your loan needs to do.

    What we check first

    Your income and borrowing power now, whether the structure still fits, and how to plan for what is coming before you need to apply.

  • It has been two years or more

    If nobody has looked at your loan for two years, your balance, equity and the market have all moved on.

    What we check first

    Your current rate against today's pricing for your profile, the fees you are paying, and whether your equity now opens better pricing.

Already own a home and planning a move?

If the health check is the first step towards a renovation, an investment property or your next home, see our page for existing homeowners. It covers using equity, buying before you sell and keeping your first home. Wondering about timing a switch? Our guide on when to refinance a home loan sets out the signs.

Sumit · 1:18
Cheaper rate or the right strategy?Sumit Joshi, RyRo Loan Centre · cheaper rate or the right strategy

Run your numbers

See what your offset and extra repayments are worth

A health check often finds money in the loan you already have. Savings sitting outside the offset, or a few dollars a week extra, can cut years and interest off the loan.

  • Money in the offset

    Every dollar in a full offset account reduces the balance you pay interest on, while staying yours to use.

  • Compare two rates

    Put your balance and a lower rate into our loan repayment calculator to see the monthly difference on your own loan.

Sumit · 0:35
$50 a week extra could save you $100,000Sumit Joshi, RyRo Loan Centre · $50 a week extra on a $700k loan, at an assumed 5.5%

Try the offset calculator on your own loan

Enter your balance, rate and what you keep in savings. Then bring the result to Sumit and he will check it against your actual loan.
Open the full home loan offset calculator
% a year

Your estimate

Interest saved with the offset

$202,175

And the loan is paid off 4 years 8 months sooner.

Total interest, no offset
$695,029
Total interest, with offset
$492,854
With and without the offset
Your loan with and without the offset
MeasureNo offsetWith offset
Total interest$695,029$492,854
Paid off in30 years25 years 4 months
Monthly repayment$3,597$3,597

That is about $3,084 less interest in the first year alone. Your offset catches up with the loan balance in about 24 years 2 months.

Assumptions

Assumes a 100% offset, principal and interest with the same monthly repayment in both cases, the rate staying the same and no fees. Lenders charge interest daily; this works monthly, so treat it as a close guide.

Figures last checked .

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

How it works

How a home loan health check works with RyRo

Four steps. You only send more paperwork if you decide to change something.

  1. Step 1

    Tell us about your loan

    Two minutes on the form, then send your latest statement. No credit check.

  2. Step 2

    Sumit prices your loan

    He compares your rate, fees and structure with lenders whose policy fits your profile, including your current lender.

  3. Step 3

    You get a plain answer

    Stay, reprice, refinance or restructure, with the costs of any change set out first.

  4. Step 4

    We do the legwork

    A repricing request, a refinance or a restructure: we prepare it and keep you updated to the end.

What to send us

  • Your latest home loan statement for each loan (balance, rate, repayments, fees).
  • The end date of any fixed rate.
  • A rough idea of what your home is worth. We can order an estimate.
  • Other debts: car loans, credit cards and their limits.
  • Payslips or tax returns only if you decide to move or borrow more.

Not sure where to find something? Ask Sumit and he will tell you.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
Start my health check

Step 1 takes about two minutes.

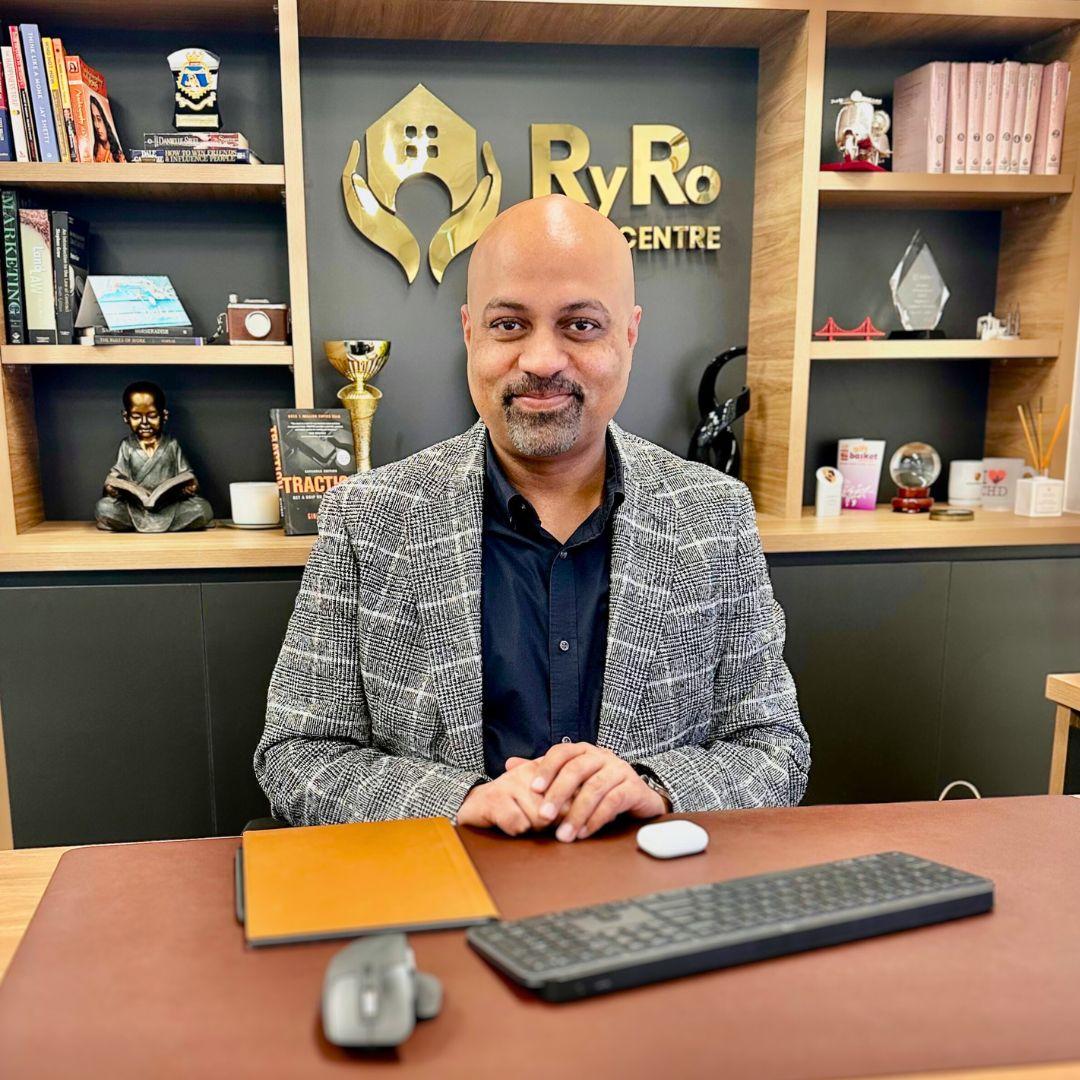
Sumit Joshi at the RyRo Loan Centre office in Norwest

Sumit Joshi JP

Principal broker, Credit Rep 446824

Who you will deal with

A broker who picks up the phone

Sumit does your health check himself. He has reviewed home loans for Hills District and Sydney families for years, and many of his Google reviews come from clients he has helped more than once.

  • A panel of 50+ lenders, from the big banks to smaller lenders and credit unions.
  • Your current lender is in the comparison too. If staying is best, he says so.
  • Home loans, equity and investment in one place, so the structure fits your next step.
  • AFG Excellence Awards Finalist 2025
  • AFG Excellence Awards Finalist 2024
  • AFG Excellence Awards Finalist 2023
  • AFG Excellence Awards Finalist 2022
  • Top Broker nominee. Sumit Joshi has been nominated in the Top Broker category every year since 2022.
  • Top Mortgage Groups nominee. RyRo Loan Centre has been nominated in the Top Mortgage Groups category every year since 2022.
  • AFG Excellence Awards finalist. Finalist five years in a row, 2022 to 2026.
  • AFG Award Winner. Seven consecutive years, 2013 to 2019.

Based in Norwest. Meet us at the office (see our Norwest mortgage broker page) or do it all by email. We review loans for homeowners right across Sydney, as a Sydney mortgage broker.

Ask Sumit to check my loan

Free, no obligation.

Google reviews

What clients say about reviewing their loan with Sumit

Rated 5.0 out of 5 from 360+ Google reviews. These mention refinancing and restructuring, word for word.

Google

5.0

From 360+ Google reviews

Sumit · 2:56
Approved in days after her broker went quietSumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • Guru Prasadh

    3 years ago on Google

    Google

    Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

    Guru Prasadh

    Google3 years ago on Google

    Sumit has been my mortgage broker for over couple of years, and this time he and his team helped me to refinance my loan & they provided best possible advice with regard to rates and assisted in loan restructure as well. The paper work was easy to follow and without hassles. Sumit is always a very approachable person and someone who would be willing to walk the extra mile to provide additional insights. I would highly recommend his services for both new home buyers & investors.

  • Kesan Ramamoorthy

    4 years ago on Google

    Google

    Simply Awesome! RyRo made my home loan refinance look very easy but I know having a complex loan structure, it's a very difficult job to do. So thank you Sumit for all your help and constant updates throughout the loan process.

  • Anil Kumar

    3 years ago on Google

    Google

    I have been working with Sumit from last 3 years now and no complaints. He is a trusted advisor who always provides me with worthy information, I trust him as he comes up with best deal in your own interest. Thanks to him and his team, Kathryn for helping me refinance just now, hassle free. Highly recommend.

    Anil Kumar

    Google3 years ago on Google

    I have been working with Sumit from last 3 years now and no complaints. He is a trusted advisor who always provides me with worthy information, I trust him as he comes up with best deal in your own interest. Thanks to him and his team, Kathryn for helping me refinance just now, hassle free. Highly recommend.

  • Gurbaksh Dhillon

    2 years ago on Google

    Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

    Gurbaksh Dhillon

    Google2 years ago on Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

FAQs

Home loan health check FAQs

Have a question not covered here? Ask Sumit directly or book a free strategy call.

What is a home loan health check?

+
A home loan health check is a free review of the loan you already have. A broker compares your rate with what lenders offer borrowers like you today, then looks at your fees, offset and redraw, loan structure, fixed rate expiry, your equity and any other debts. You get a plain answer: stay where you are, ask your lender to reprice, refinance to another lender, or restructure the loan you have.

How often should I review my home loan?

+
Once a year is a good habit, and any time something big changes. Lenders change their pricing often, and your own position changes too: your balance drops, your home grows in value and your income moves. A loan nobody has looked at for two years or more may no longer match the pricing your profile could get today. Also review it before a fixed rate ends, after a rate rise, and when your income, family or plans change.

Does a home loan health check cost anything?

+
No. A health check with RyRo Loan Centre is free and there is no obligation to change anything. If the answer is to stay, we tell you, and we can help you ask your lender for a better rate. If you do refinance or take a new loan through us, the lender pays our commission, so home loan broking costs you nothing. Any lender fees for switching are set out before you decide.

Will a home loan health check affect my credit score?

+
No. Reviewing your loan does not need a credit enquiry. We work from your loan statements and what you tell us about your income and debts. A credit check only happens if you decide to apply for a new loan or a change with a lender, and we tell you before any application goes in so nothing lands on your file by surprise.

Can my current lender lower my rate without refinancing?

+
Often, yes. Many lenders will reprice a loan for an existing customer who asks, especially one with a good repayment record and a lower loan to value ratio than when they started. Knowing what other lenders would offer you makes that request much stronger. We price your loan across our panel first, so you know whether the offer your lender comes back with is a fair one or whether moving is worth it.

What do I need for a home loan health check?

+
Your most recent home loan statement for each loan is enough to start. It shows your balance, rate, repayments and fees. Add the end date of any fixed rate, a rough idea of what your home is worth, and any other debts such as car loans or credit cards. If the check shows a switch makes sense, we then ask for payslips or tax returns and only what the new lender needs.

What happens if the health check says I should stay?

+
Then you stay, and you know your loan is doing its job. Sometimes the best result is a small change with your current lender: a rate review, moving savings into an offset account, dropping a package fee you no longer use, or splitting the loan. We will tell you if switching would cost more than it saves. We would rather you trust our advice next time than move for the sake of it.

Should I get a health check before my fixed rate ends?

+
Yes. When a fixed term ends, most loans roll onto the lender's standard variable rate, which can be higher than the rates on offer to borrowers like you. Starting a few months before the end date gives you time to compare, ask your lender for a better rollover rate, or line up a refinance to settle close to the expiry. Breaking a fixed rate early can cost a break fee, so timing matters.

Is a home loan health check the same as refinancing?

+
No. A health check is the review; refinancing is one possible result. Plenty of health checks end with no switch at all: a repriced rate with the same lender, an offset set up properly, or a split that suits your plans. If refinancing does come out ahead after costs, our refinancing team handles the whole switch, from the application to the discharge of your old loan.

Free home loan health check

Ready to find out if your home loan is still working for you?

Send Sumit a few details about your loan. He will check your rate, fees, offset and structure against the market and tell you plainly whether to stay, reprice, refinance or restructure.
Sumit Joshi, principal broker at RyRo Loan Centre

Get your free home loan health check

Leave your details and Sumit will call you to go through your loan. No obligation.
Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

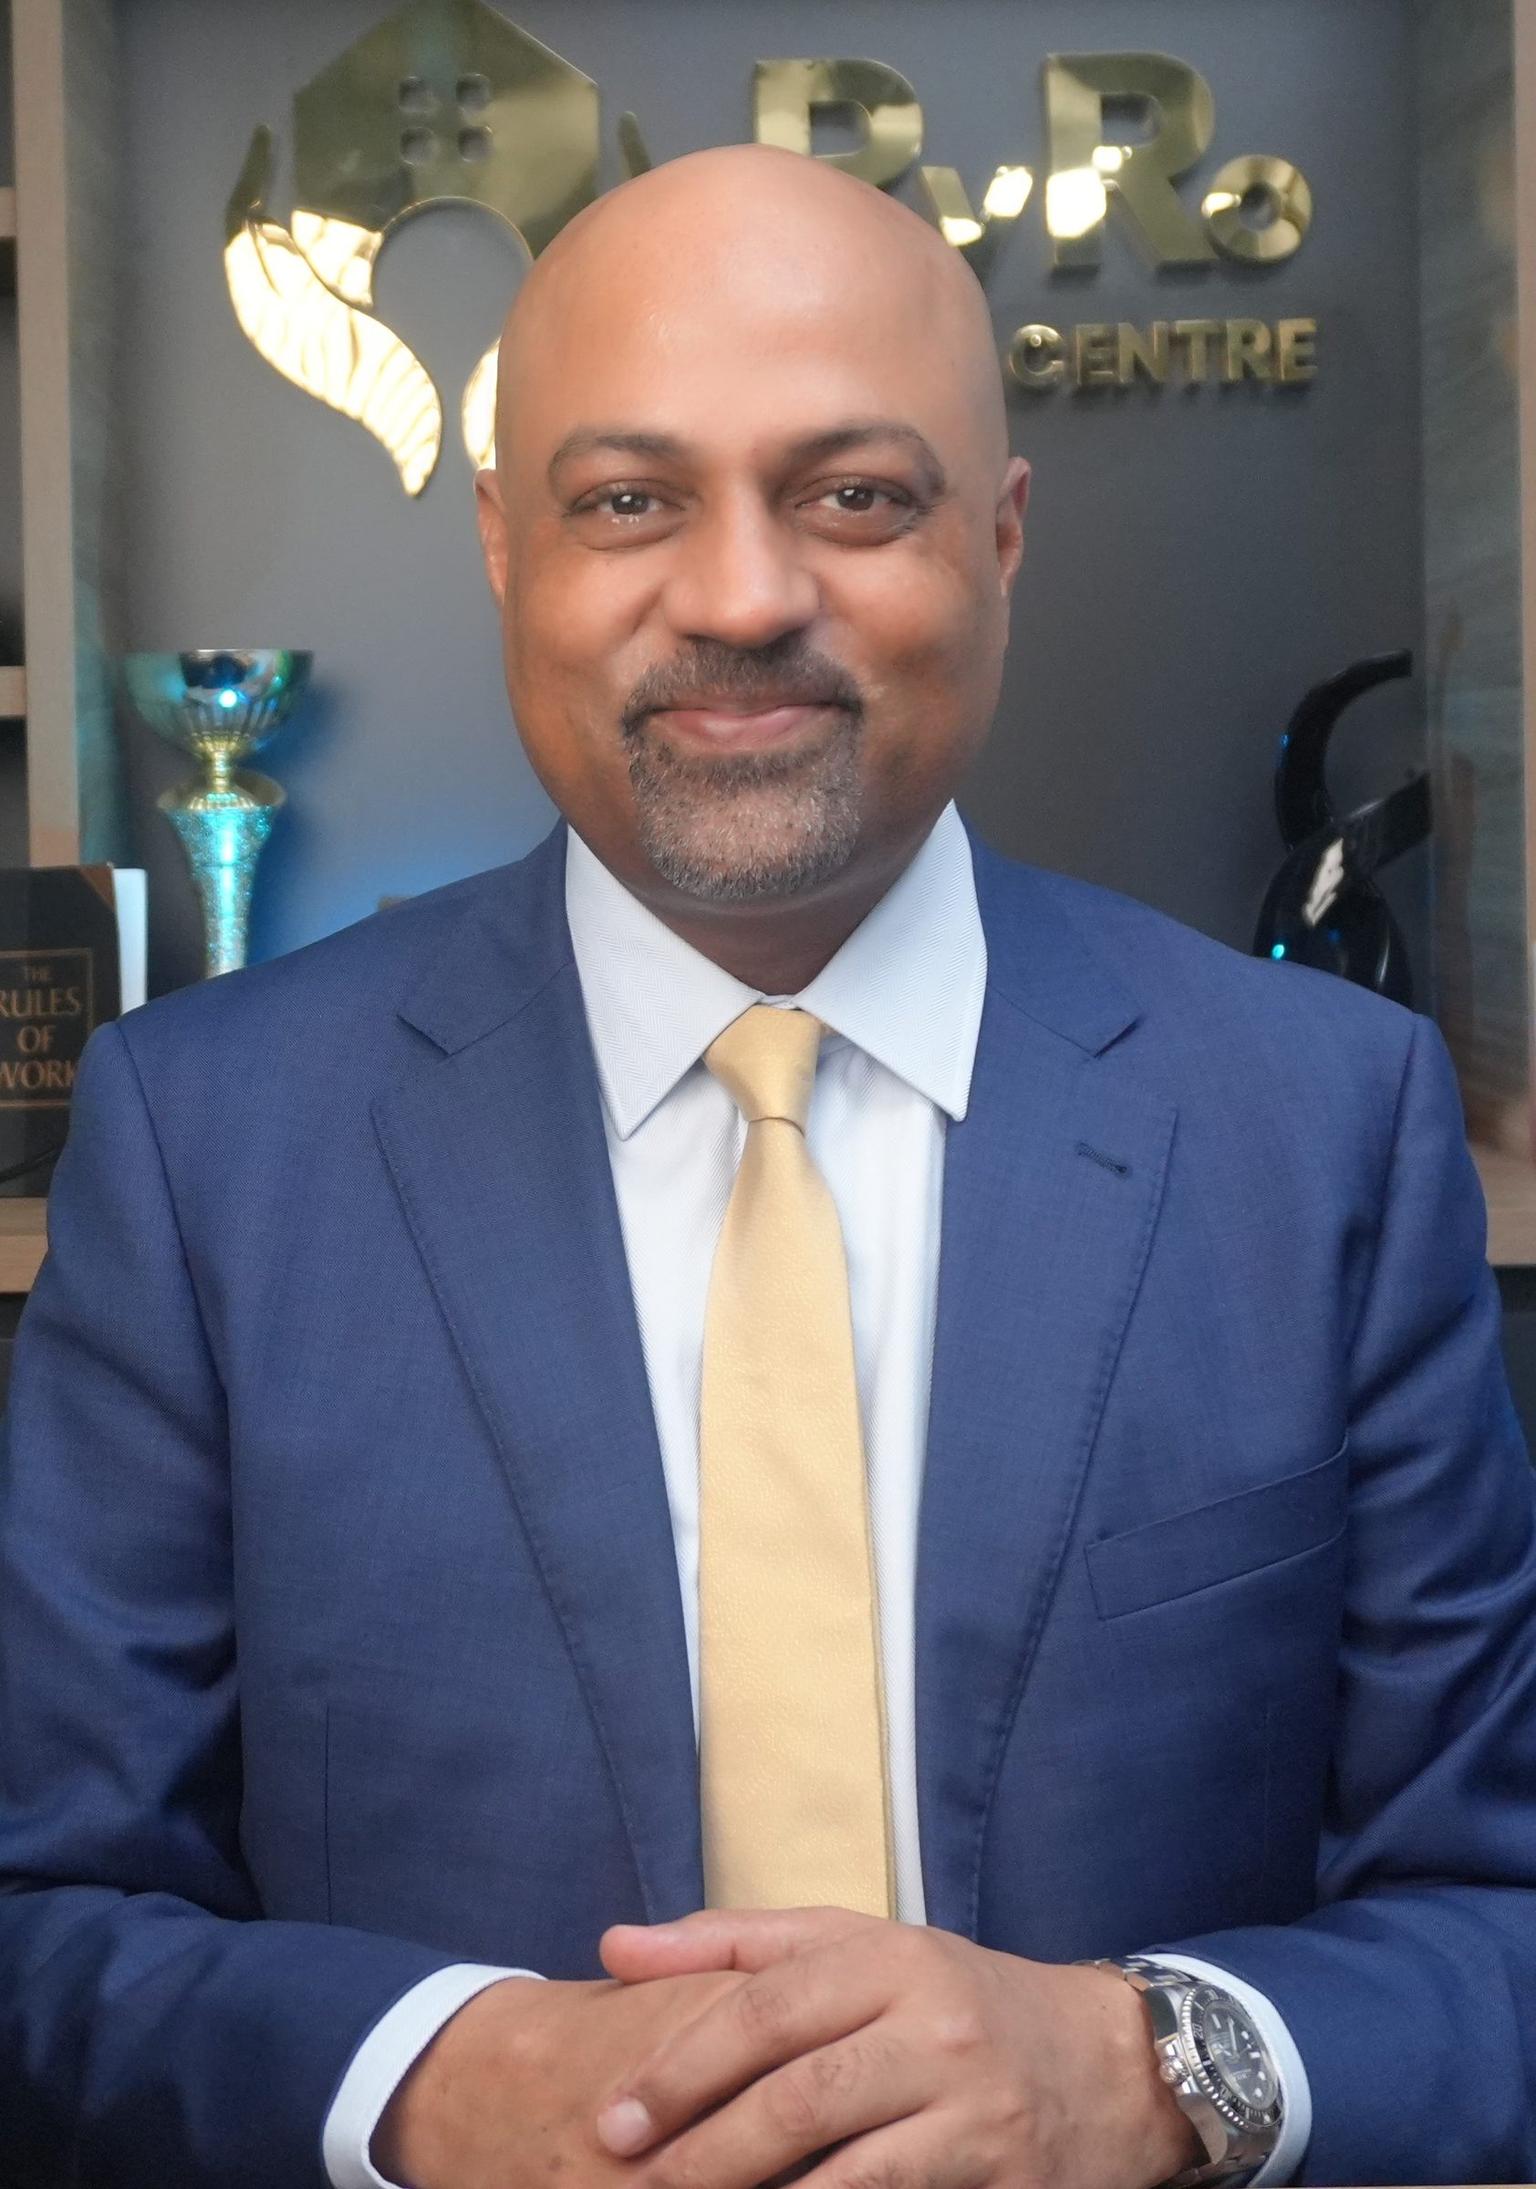
Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reviews your loan and calls you back
  • No obligation and no credit check
  • Free for home loans: the lender pays us
Sumit · 1:18
Cheaper rate or the right strategy?Sumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Lenders your loan is checked against
50+
“We have consulted with RyRo Loan Centre for 2 refinancing packages and on both occasions Sumit has ensured that our needs were met far beyond expectations. Sumit has exceptional knowledge in the field and makes the process very simple and efficient.”
Krish Gopal · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026. General information only. Rates, fees and lender policies change and depend on your circumstances.

Get my free loan review