Daljeet Singh
9 months ago on Google

I have wonderful experience with them they are professional,quick and accurate in terms of loan requirements
Mortgage brokers in Norwest, helping the Hills District and Sydney
ABN car finance, RyRo Asset Finance
Run your own business? Lenders look at ABN holders differently, so Rohan Joshi at RyRo Asset Finance matches your ABN, paperwork and vehicle to the lenders whose policy already fits.
5.0 from 13 Google reviews for RyRo Asset Finance
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Updated November 2026
ABN car finance explained
ABN car finance is a vehicle loan for people who earn through an Australian Business Number rather than a wage. The lender assesses your business: how long your ABN has been registered, whether you are registered for GST, and what your tax returns, BAS or bank statements show.
It covers cars, utes and vans, new or used. When the vehicle is mainly for work, it is usually written as a business loan. When it is mainly for personal driving, it is a consumer loan assessed on your self employed income. Rohan works out which fits before you apply, as part of our wider work as a car finance broker in Sydney.
Rohan works from the RyRo office in Norwest, so business owners across the Hills District can meet him in person, or handle it all by phone and email from anywhere in Sydney.
Quick answer
Not quite. ABN car finance is any vehicle loan for a business owner. A low doc car loan is one way of getting it, using BAS or bank statements when your tax returns are not available.


Car finance for ABN holders
If your income comes through an ABN, these are the people we help most often.
A ute, van or car you drive to jobs every day, financed on your business income rather than payslips.
IT, health, engineering and other contractors paid on invoice, including those who recently moved from PAYG.
A business that is months old rather than years. Fewer lenders, but often still a path with the right evidence.
Companies, trusts and partnerships buying a vehicle in the business name, from one car to a second work ute.
Need something heavier? See ute finance for ABN holders or truck finance.
Low doc car finance
A full doc loan uses your tax returns. A low doc car loan uses other evidence when the returns are not ready or do not show what you earn now. Here is how they usually compare.
| Full doc | Low doc | |
|---|---|---|
| Income evidence | Tax returns and notices of assessment | BAS, bank statements or accountant letter |
| Suits | Established businesses with lodged returns | Strong recent trading, returns not lodged |
| Lender choice | The widest | Narrower, varies by lender |
| Typical trade-off | More paperwork up front | Can mean a higher rate or deposit |
General lender practice. Each lender sets its own rules.
Free, no obligation.
Self employed car loan
These are the items lenders commonly ask ABN holders for. Not every lender asks for all of them, and the minimums differ from lender to lender.

Daljeet Singh
9 months ago on Google
I have wonderful experience with them they are professional,quick and accurate in terms of loan requirements
Some lenders accept a short letter from your accountant or tax agent confirming your business income, in place of lodged returns. Lenders that accept one usually want it on the firm's letterhead and from a registered tax agent, and they may check it. Ask your accountant early, as it can take a few days.
If you are also self employed and planning to buy a home, the paperwork overlaps with low doc home loans, which Sumit and the RyRo Loan Centre team handle.
New business, first vehicle
A young ABN narrows the field, but it does not always close it. Some lenders support new businesses when other parts of the application are strong. These are the things that commonly help.
Years in the same trade or field before your ABN, even as an employee.
Money in the deal lowers what the lender is asked to carry.
Some lenders treat home ownership as a sign of stability.
No defaults and few recent enquiries. A thin file can still work with some lenders.
Rohan checks ABN age against each lender's policy first.
5.0 from 13 Google reviews for RyRo Asset FinanceRyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Loan types
The main question is how you will use the vehicle. Mostly for work points to a business loan; mostly personal points to a consumer loan.
| Chattel mortgage | Consumer car loan | |
|---|---|---|
| Best for | A vehicle used mainly for business | A vehicle used mainly for personal driving |
| Who owns it | The business, from day one | You, with the lender holding security |
| How it is assessed | Your business and its trading | Your income and living costs |
| Balloon option | Commonly available | Available with some lenders |
A business purpose loan usually asks you to sign a declaration that the vehicle is mainly for business.
Read our chattel mortgage guide for the detail, or try different terms in the loan repayment calculator.
Business use and tax
The tax treatment of a work vehicle depends on your business structure, the vehicle and how you use it. We do not give tax advice. Rohan sets up the finance; your accountant confirms the tax. Ask them these questions before you sign.
A balloon is a lump sum left to the end of the loan. It lowers the regular repayments, but you pay it at the end, refinance it or trade the vehicle. It suits steady cash flow and a vehicle that holds its value. Rohan checks the balloon against what the vehicle is likely to be worth at the end.
Estimated repayment per month
$999.36
60 monthly repayments paid in advance, then a balloon of $18,000
GST in the price: $5,455
One eleventh of a GST-inclusive price. A GST-registered business may be able to claim GST on a business asset as a credit on its BAS. Whether you can, how much and when depends on your business use and how you account for GST. We recommend consulting your accountant.
Estimate only, not a quote or tax advice. It leaves out fees and charges, and the rate is the one you type in. Your real repayment depends on the lender, the asset and your business.
Figures last checked .
This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.
Free, no obligation. Your numbers go with your enquiry.
5.013 RyRo Asset Finance reviews
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Sound familiar?
Most business owners come to Rohan with one of these. Here is what usually gets in the way, and what we do about it.
5.0 from 13 Google reviews for RyRo Asset Finance
The challenge: Your latest year was your best, but the return is still with your accountant and the bank wants it.
We look at low doc lenders that accept recent BAS, bank statements or an accountant letter instead.
The challenge: You left a PAYG job to contract or start a trade business, so your ABN is young.
We find lenders that weigh your time in the industry, deposit and credit file, not only ABN age.
The challenge: You need a ute or van with a canopy, racks or shelving fitted, and the job cannot wait.
We check whether the lender will include the fit-out and line up the documents before you commit.
The challenge: The yard offered business finance on the spot, with a balloon you were not expecting.
Bring the quote. We compare it with other lenders and explain the balloon and fees in plain English.
These are common situations, not client stories. Every loan depends on your circumstances and the lender's policy.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
How it works
Step 1
Your ABN, GST status, how you are paid and the vehicle you want. Two minutes on the form.
Step 2
He matches your ABN age, paperwork and vehicle to lenders whose rules fit, before any application.
Step 3
You send only the documents that lender needs. Rohan prepares and lodges the application.
Step 4
Once approved, the funds go to the dealer or seller and you collect the keys.
Step 1 takes about two minutes.
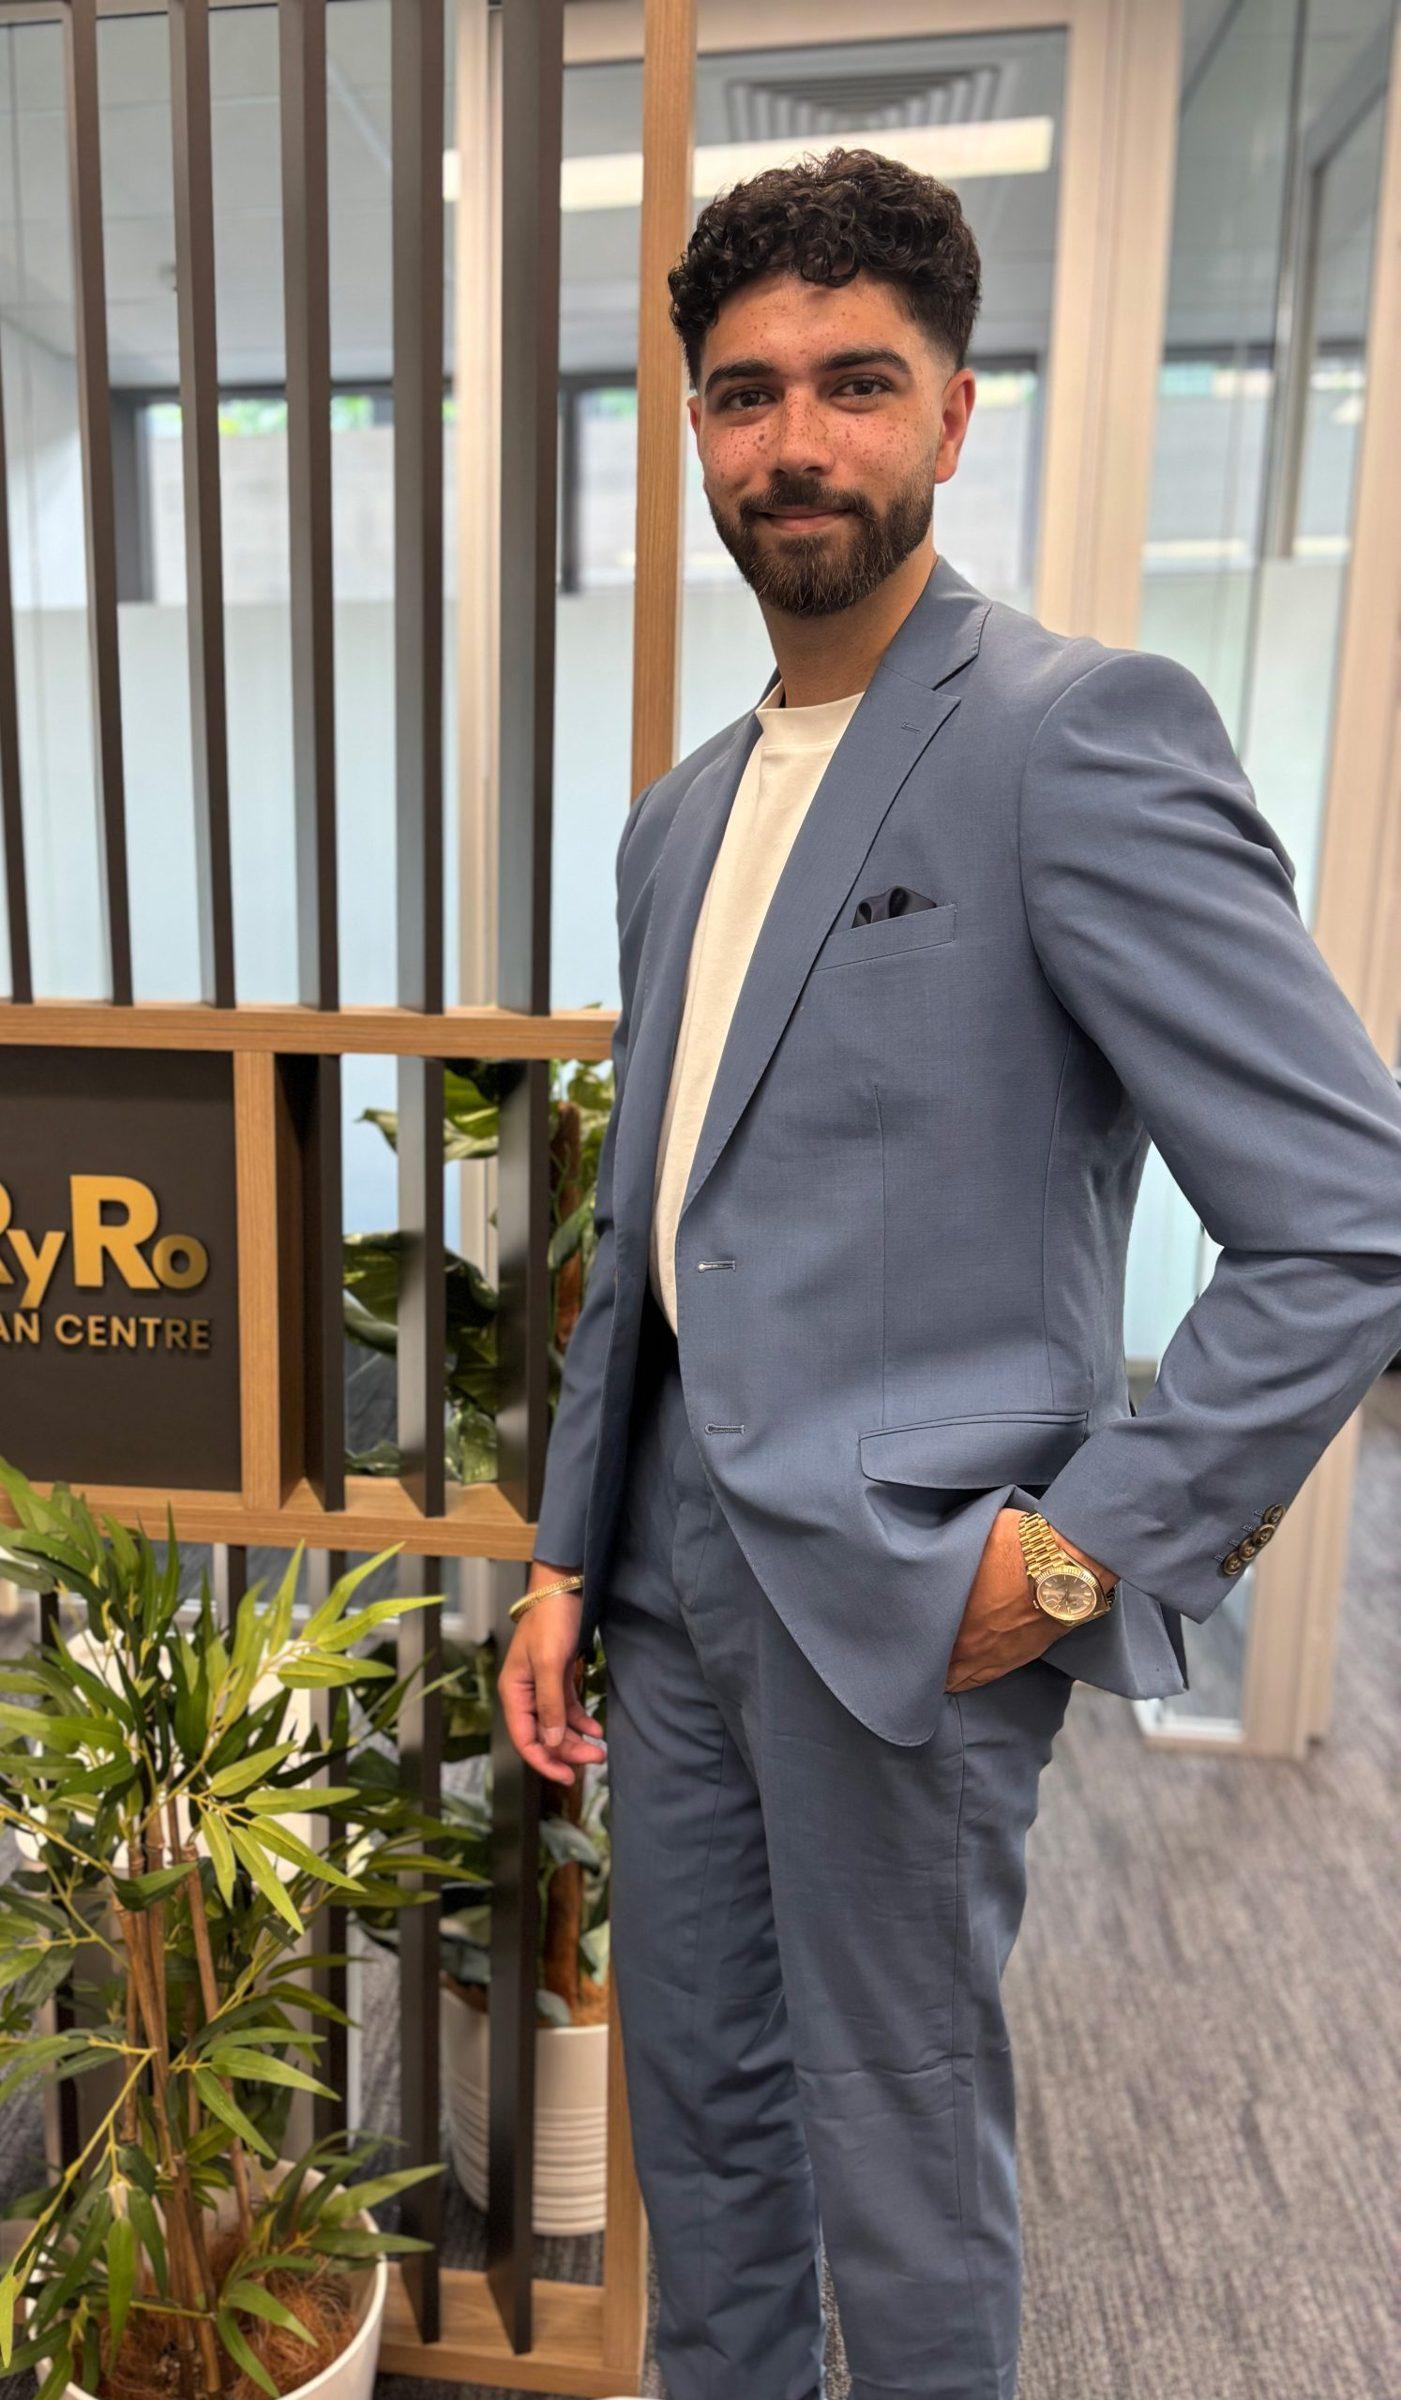
Rohan Joshi
Asset finance broker, RyRo Asset Finance, ACR 565295
Who you will deal with
You deal with one person. Rohan reads your details, works out whether a business or consumer loan fits, and keeps you updated until the vehicle is paid for. His clients mention the same things in their Google reviews: clear explanations, quick answers and simple paperwork.
RyRo Asset Finance is a separate company from RyRo Loan Centre, working from the same Norwest office. If you also need a home loan, Sumit and the RyRo Loan Centre team look after that.
Free, no obligation.
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.
Google reviews
Real Google reviews of RyRo Asset Finance, word for word.
5.0
From 13 Google reviews for RyRo Asset Finance
krunal shah
11 months ago on Google
Thank you for your support to get my business car loan done in 1 day. Highly recommend
Rayen Naidoo
2 months ago on Google
I engaged Ryro Finance to arrange finance for my vehicle, and the experience was excellent. They didn’t just compare car loan options—they took a holistic approach by considering my future financial goals and any upcoming asset purchases to ensure the finance structure suited my long-term plans. They provided valuable advice on the ideal deposit amount, explained the best approach to financing a vehicle, and secured one of the most competitive interest rates available to me. I would highly recommend Ryro Finance, not only for vehicle finance but for any financing requirements. Their personalised advice, professionalism, and long-term financial planning set them apart.
Mark Donovan
a month ago on Google
Rohan provided exceptional service, was communicative and transparent through the entire process. I ended up with a far better deal than I would have got on my own.
Gurmit Singh Bhooi
a year ago on Google
We had a great experience working with Rohan Joshi. He was professional, responsive, and made the entire process of securing our car loan smooth and stress-free. He took the time to understand our needs, explained everything clearly, and got us a competitive rate without any hassle. We really appreciated how straightforward and efficient he was from start to finish. Highly recommended if you’re looking for someone reliable to help with a car loan.
Keep reading
Our guide to ABN car loans walks through the low doc paperwork in more detail, with the questions to ask before you sign.
Personal Finance · 8 min read
Self-employed and need a car or ute? Here is how lenders assess ABN holders, what low doc car loans need, how new ABNs can still get finance, and the documents to have ready.
Read the guideTalk to Rohan
We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.
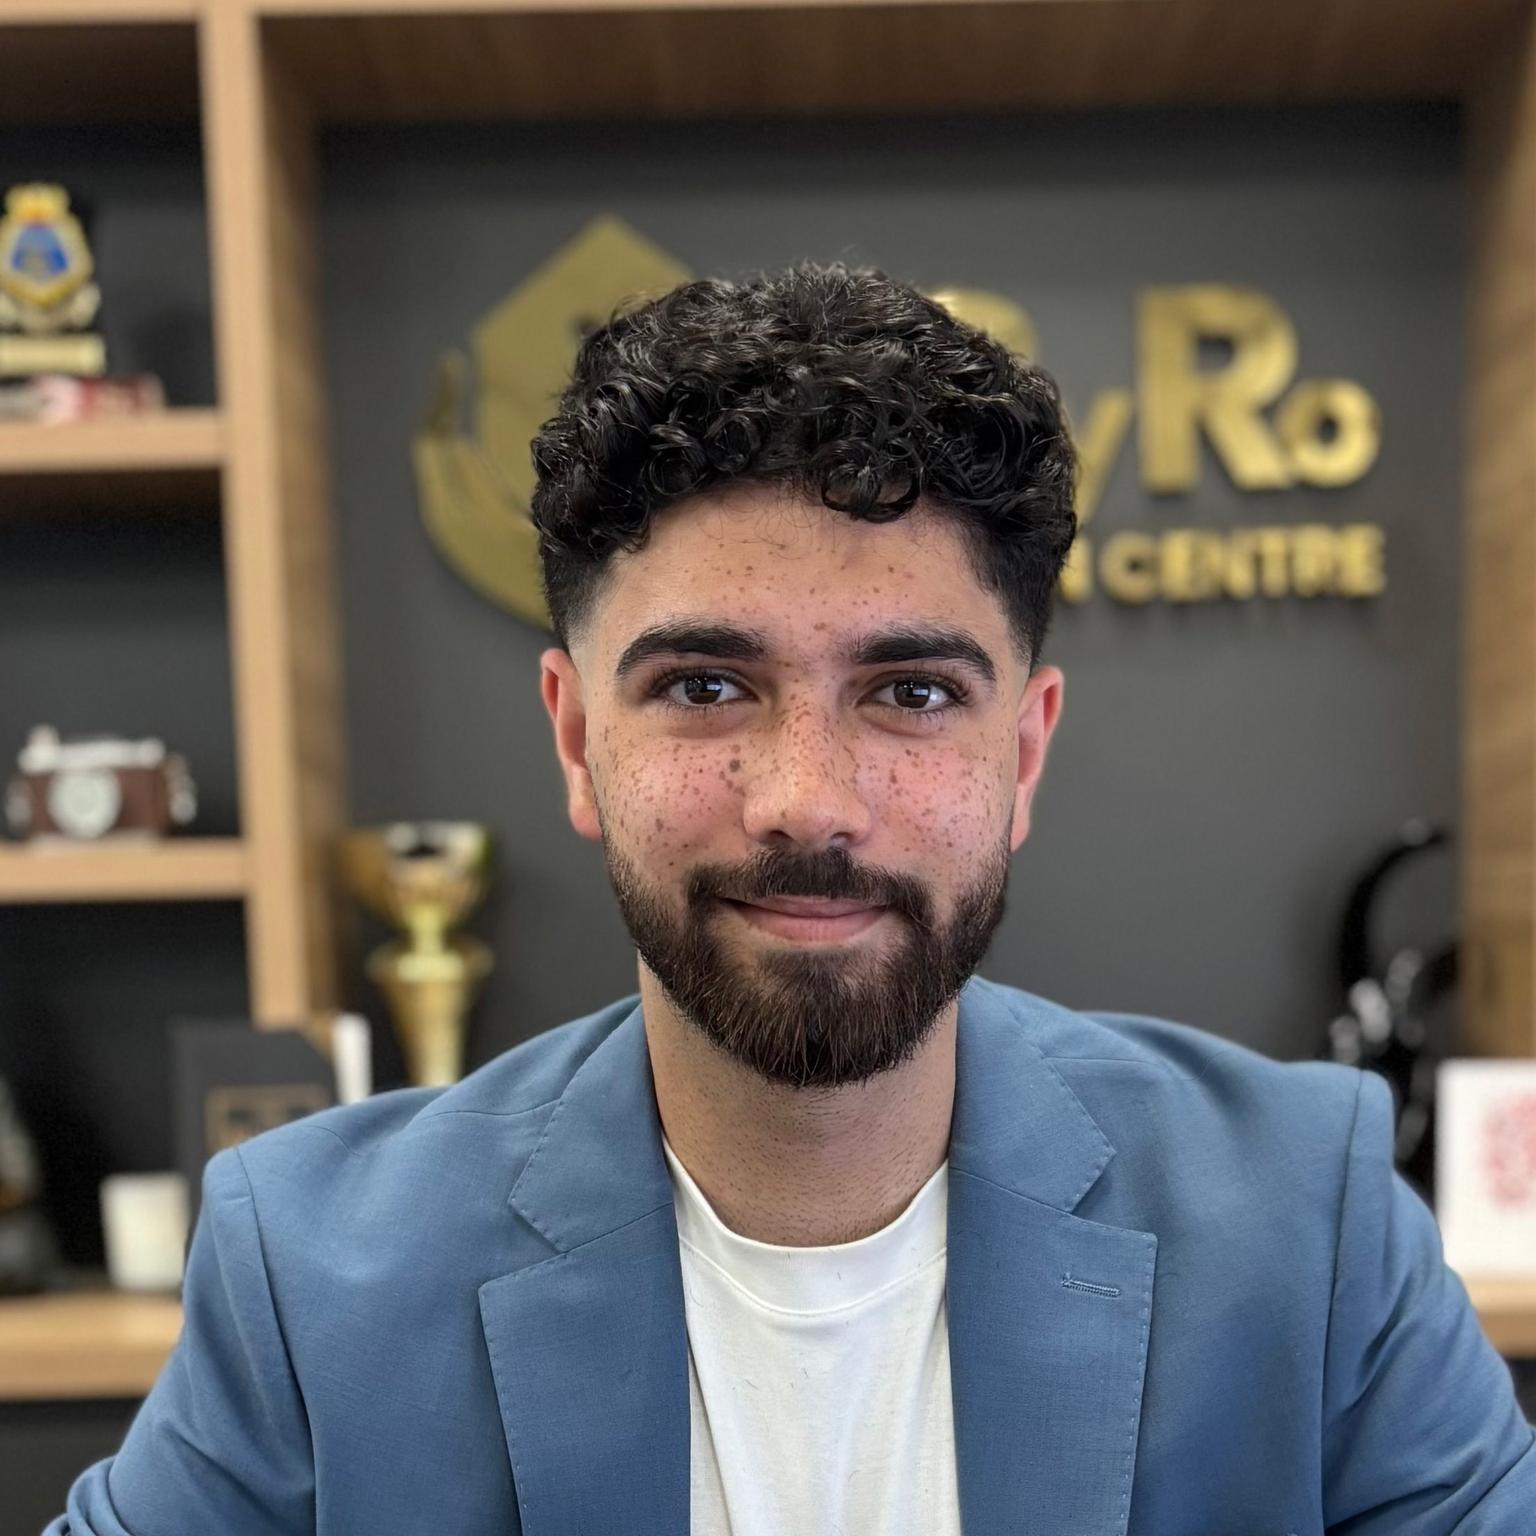
Rohan Joshi
Asset finance broker, RyRo Asset Finance
More videos from Rohan
“I had an excellent experience with Rohan for my car loan. He was professional, responsive and extremely helpful throughout the entire process. He explained all the options clearly, found a competitive loan that suited my circumstances and made the paperwork simple and stress-free. I highly recommend RYRO services to anyone looking for a reliable and trustworthy car loan broker.”
RyRo Asset Finance Pty. Ltd., (ABN 69 682 063 896) an Authorised Credit Representative (ACR #565295) of Fintelligence Pty Ltd (ABN 80 625 017 174), Australian Credit Licence # 511803.