RyRo Loan Centre

Renovation loan broker, Sydney

Renovation Loans in Sydney, Matched to Your Project

A new kitchen, a second bathroom or a full extension each call for a different loan. Sumit explains your options in plain English, works out what you can borrow and compares 50+ lenders for the one that fits the job.

Sumit Joshi, principal broker at RyRo Loan Centre

Planning a renovation?

Free call with Sumit. No credit check, no obligation.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • Top ups, equity releases, refinancing and construction loans
  • Help with quotes, valuations and progress payments
  • Based in Norwest, Sydney. $0 broker fees on home loans
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Google5.0From 360+ Google reviews Read them
Clients helped
2,500+
Broker fees on home loans
$0
Loan review, no credit check
Free

Some of the banks and lenders we compare for you

  • Commonwealth Bank
  • Westpac
  • NAB
  • ANZ
  • St.George
  • Bank of Melbourne
  • Suncorp Bank
  • BOQ
  • Great Southern Bank
  • Beyond Bank
  • People First Bank (formerly Heritage Bank)
  • Teachers Mutual Bank
  • Hume Bank
  • IMB
  • Newcastle Permanent
  • QBANK
  • UniBank
  • Bank Australia
  • BankSA
  • Credit Union SA
  • Macquarie
  • ING

The basics

What Is a Renovation Loan?

A renovation loan is money you borrow to improve your home. For most owners it is not a special product: it is extra borrowing against the home itself, through a top up, a refinance or, for structural work, a construction loan that pays the builder in stages.

Quick answer

How do renovation loans work?

The lender looks at what your home is worth, what you owe and what you earn. The gap between your loan and about 80% of the value is your usable equity. Small jobs are paid as a lump sum; big structural jobs are paid to the builder in stages.

A home loan based renovation loan can suit you if

  • You own your home and have built up some equity
  • Your income can carry the higher repayments with room to spare
  • You have quotes or a contract, so you know what the job costs
  • You want a lower cost of borrowing than unsecured credit

It may not suit you if

  • You have little or no equity yet and the job is not planned in detail
  • The repayments would already be tight before rates move
  • The job is small and you could pay it from savings
  • You would struggle to pay down a long term loan faster than required

Want to know which route suits your job? Sumit can tell you on a free call.

Talk to Sumit about my renovation
Sumit · 0:52
What equity is, and how much you can useSumit Joshi, RyRo Loan Centre · equity and usable equity

Your options

Five Ways to Fund a Home Renovation

The right home renovation loan depends on the size of the job, how much equity you have and whether your current loan is still a good deal. Here are the five routes, from the most common to the least.

Clients who refinanced with us

  • O D

    2 weeks ago on Google

    Google

    My wife and I are very happy and very greatful for all the help Sumit from RYRO LOAN CENTRE has helped us once again. We are so blessed to have had the opportunity to meet such a kind, hard working and wonderful person who will go above and beyond to get our home loan refinancing approved. So thank you very much summit. We will definitely be going back to RYRO team when we buy our next property. We will also recommend RYRO Loan Centre, especially Sumit to our family & friends! They are simply the BEST!! 😊

    O D

    Google2 weeks ago on Google

    My wife and I are very happy and very greatful for all the help Sumit from RYRO LOAN CENTRE has helped us once again. We are so blessed to have had the opportunity to meet such a kind, hard working and wonderful person who will go above and beyond to get our home loan refinancing approved. So thank you very much summit. We will definitely be going back to RYRO team when we buy our next property. We will also recommend RYRO Loan Centre, especially Sumit to our family & friends! They are simply the BEST!! 😊

  • gopichand paladugu

    a year ago on Google

    Google

    It's been an amazing experience working with Sumit, he helped me through initial Mortgage loan and recently in refinancing my loan. He helped me in every step of the process and patiently explained any questions we had. I strongly recommend him, if you are looking for mortgage broker services.

    gopichand paladugu

    Googlea year ago on Google

    It's been an amazing experience working with Sumit, he helped me through initial Mortgage loan and recently in refinancing my loan. He helped me in every step of the process and patiently explained any questions we had. I strongly recommend him, if you are looking for mortgage broker services.

Sumit · 1:23
Five ways to use the equity in your homeSumit Joshi, RyRo Loan Centre · renovating is number one
  • Sandstone cottage with a red roof behind a brick fenceEquity

    Top up or equity release

    Borrow more against your home with the lender you already have, often as a new split that holds only the renovation money.

    Best for: kitchens, bathrooms and other non-structural work

    How it works

    The lender values your home, checks your income and adds the extra to your loan, usually as a lump sum. Keeping it in its own split makes the renovation debt easy to see and pay down. Your existing loan stays as it is.

    The catch: it is more debt over a long term, and borrowing above about 80% of the value usually brings Lenders Mortgage Insurance into play.

  • Hands signing loan paperwork at a deskRefinance

    Refinance to renovate

    Move your loan to a new lender and borrow the renovation money in the same application.

    Best for: owners whose rate is no longer sharp, or whose lender will not lend enough

    How it works

    One valuation, one application, one settlement. It can make sense when a new lender offers a better deal or a more generous valuation. It costs something to switch (discharge and set up fees, and break costs on a fixed loan), so we run the maths before recommending it.

    Our guide to refinancing to renovate walks through it step by step.

  • Timber frame of a new house going up, with scaffolding against a blue skyStructural

    Construction loan

    For extensions, second storeys and major rebuilds. The lender pays your builder in stages as work is done.

    Best for: structural work with a builder and a fixed price contract

    How it works

    Money is released in progress payments as each stage is finished and checked, and you pay interest only on what has been drawn so far. Lenders want a fixed price contract, plans and council approval where needed. Some will lend against the finished value.

  • Pink piggy bank and coins on a wooden tableSavings

    Redraw or offset

    Use extra repayments you have already made, or savings sitting in your offset account.

    Best for: smaller jobs you can mostly cover yourself

    How it works

    No new application, so it is quick. But money taken out of an offset starts costing you interest again, and some lenders limit or charge for redraws. The offset vs redraw guide explains the difference.

  • Calculator app on a phone held over a folder of paperworkGeneral option

    Personal loan

    Unsecured and quick, but usually a higher rate and a short term, so repayments are higher.

    Best for: small jobs when you would rather not touch your home loan

    How it works

    RyRo arranges home loan based renovation finance, not unsecured personal loans. We mention them so you see every option. If you are weighing one up, we can show you what the same amount would cost through your home loan.

Not sure which of the five fits? We compare them for your home and your job.

Find the right route for me

Side by side

Which Renovation Loan Fits Your Project?

A quick comparison of the four home loan based options. Your lender's policy decides the detail, so treat this as a starting point, not a rule.

Renovation loan options compared
OptionTop up or equity releaseRefinance to renovateConstruction loanRedraw or offset
SuitsNon-structural workAny job, when a better deal is availableExtensions, second storeys, major workSmall jobs
How the money is paidLump sum to youLump sum at settlementStages, straight to the builderDrawn as you need it
ValuationHome as it is todayHome as it is todayCan be on completionNone
New applicationYesYesYesNo
Paperwork for the workQuotesQuotesContract, plans, approvalsNone

How much could you borrow for your renovation?

A first estimate on your income and debts. The lender also checks your usable equity, so we test both together on the call.
Open the full borrowing power calculator
Who is applying?
a year
a month
% a year
More details(optional, 3)
a month

Your indicative range

You could borrow around

$489,000 to $541,000

Lower figure: stricter assumptions. Higher: more generous ones.

Rate the loan is tested at
9.00% a year
Repayment at your 6% rate
$2,933 to $3,246 a month
How we worked it out
Income after tax
$6,457 a month
Living expenses used
$2,100 to $2,520 a month
Debts and card limits
$0 a month

A range, not a single figure, because every lender assesses this differently. The lower number uses stricter assumptions and the higher one more generous ones. No lender has approved it.

Assumptions and sources
AssumptionStricterMore generous
Bonus and overtime counted50%80%
Rental income counted70%80%
Card limit as a monthly repayment3.8%3%
Living cost benchmark$2,520/mth$2,100/mth
Debt-to-income cap6x incomeNone
Rate buffer+3 points+3 points
  • Tax uses the ATO 2026-27 resident rates, the low income tax offset, the 2% Medicare levy and HECS or HELP repayments. Each applicant is taxed as a single person.
  • Living costs are the greater of what you enter and the benchmark. Lenders use the Household Expenditure Measure, which is not public, so the benchmark is our conservative stand-in.
  • The loan is 30 years, principal and interest, tested at your rate plus the APRA buffer of 3 percentage points. Rental income has no deductions taken off. Fees, stamp duty and your deposit are not included.
  • Estimate only, not a loan offer or financial advice. Each lender uses its own servicing calculator and policy, so your real figure can sit outside this range.

This is an estimate, not financial advice. Results are a guide only. Speak to a broker for accurate figures based on your situation.

Free, no obligation. Your numbers go with your enquiry.

5.0360+ Google reviews

Want this comparison run on your own loan and your own quotes?

Compare my renovation options

Valuations

How Lenders Value a Renovation

How much you can borrow often comes down to one question: will the lender value your home as it is today, or as it will be when the work is done?

Most jobs

As is valuation

The valuer looks at your home today. Your borrowing is based on that value.

  • Standard for top ups, equity releases and refinances
  • Simple and quick
  • Limits what you can borrow if equity is thin

Bigger jobs

On completion valuation

The valuer estimates the value once the work is finished, from your contract and plans.

  • Offered by some lenders for structural work
  • Needs a fixed price contract and plans
  • The valuer may not agree with your estimate

Not every lender offers on completion valuations for renovations, and those that do set their own rules. That is one reason the choice of lender matters as much as the rate.

Some lenders value on completion and some do not. We know which ones do.

Check which lenders suit my job
House plans and architectural drawings spread across a table
Plans and a fixed price contract are what a lender needs for an on completion valuation.Photo: Marina Zvada / Unsplash
Drafting house plans with a pencil and scale ruler
Get the scope and the quotes right before you apply.Photo: Daniel McCullough / Unsplash

Before you apply

Quotes, Contracts and Cost to Complete

Lenders lend on what the job will cost to finish, not on a rough guess. The cost to complete is the full price of the work, including the bits that are easy to forget, such as approvals, fees and a buffer for surprises.

Jobs over this price (including GST) need a written contract in NSW
$5,000
Source: NSW Government, checked Nov 2026
The most a builder can ask as a deposit in NSW
10%
Source: NSW Government, checked Nov 2026
Jobs over this need home building compensation cover from your builder
$20,000
Source: NSW Government, checked Nov 2026
  • Written quotes or a fixed price contractSmall jobs often need only quotes. Structural work usually needs a signed fixed price building contract.
  • Plans and specificationsFor extensions and anything structural, so the valuer can see what is being built.
  • Council approval where neededDevelopment or complying development approval for work that needs it.
  • Builder licence and insuranceLenders check your builder is licensed and insured before they pay progress payments.

Send us your quotes and we will tell you what the lender needs to see.

Check what my lender will need

Sound familiar?

Renovation Projects We Finance

Each kind of job asks something different of the lender. Here is what usually gets in the way, and how we fund it.

  • Kitchen and bathroom renovations

    The challenge: The most common job we fund. Quotes often grow once the old kitchen or bathroom comes out.

    How we fund it

    Usually a top up or new split from your equity, with a buffer above the quote for surprises. If your rate is stale, we compare a refinance at the same time.

  • Extensions and second storeys

    The challenge: Structural work needs council approval, a licensed builder and money paid out in stages.

    How we fund it

    Often a construction loan or a construction split on your current loan, paid to the builder in progress payments. Where the lender allows it, we ask for an on completion valuation.

  • Granny flats

    The challenge: A second dwelling on your block for family or rent. Lenders treat it differently from a kitchen job.

    How we fund it

    Funded from equity for a kit or small build, or with a construction loan for a builder led project. If you plan to rent it out, we show the lender the expected rent.

  • Knockdown rebuilds

    The challenge: You love the street but the house has to go. This is a new build, not a renovation, in the lender’s eyes.

    How we fund it

    A construction loan that pays out your existing loan if needed and then funds the build in stages. We plan where you will live during the build too.

  • Renovating an investment property

    The challenge: You want to lift the rent or the value, without mixing the debt with your own home loan.

    How we fund it

    A separate split or loan against the investment so the debt stays tied to that property. Talk to your accountant about tax before you start: we do not give tax advice.

  • Renovating a home you just bought

    The challenge: You bought a home that needs work, but there is little equity in it yet.

    How we fund it

    Some lenders assess the finished value for planned work with a fixed price contract. Otherwise we plan the work in stages as your equity builds.

These are common situations, not client stories. Every loan depends on your circumstances and the lender's policy.

Project not listed here? Tell us what you are planning.

Tell Sumit about my project

Case studies

Renovations We Have Funded

Real clients, details kept private. The figures are from the loans we arranged; your outcome depends on your circumstances.

Plan my renovation funding

Free, no obligation.

  • Equity release
  • Top-up loan
  • Renovation

$200K for renovations without refinancing the existing loans

Property value
$1.85M
Existing loans (2 splits)
$1.006M
New split for renovations
$200K
  1. 1. The situation

    The clients owned their home, valued at about $1.85M, with two existing NAB loan splits totalling around $1.006M.

  2. 2. What we did

    Checked whether a full refinance would actually leave them better off. It would not.

    +2 more in the full story

  3. 3. The result

    Access to their equity without disturbing loans that were already working for them.

    +2 more in the full story

Read the full story

The situation

The clients owned their home, valued at about $1.85M, with two existing NAB loan splits totalling around $1.006M. They wanted to fund non-structural renovations and upgrades and assumed they would need to refinance everything to do it.

What we did

  • Checked whether a full refinance would actually leave them better off. It would not.
  • Kept both existing NAB splits exactly as they were.
  • Added a separate $200K split to hold the renovation funds.

The result

  • Access to their equity without disturbing loans that were already working for them.
  • Renovation money kept in its own facility, so it is easy to track and pay down.
  • Total lending of about $1.2M, roughly 65% of the property value.

Step by step

How a Renovation Loan Works With RyRo

From the first call to the last payment to your builder, you deal with the same small team in Norwest.

  1. Step 1

    Free strategy call

    Tell us the job, your rough budget and your current loan. We ask what the work involves, not just what it costs.

  2. Step 2

    Equity and borrowing check

    We estimate your usable equity and what you can borrow on your income, then pick the funding route that fits the job.

  3. Step 3

    Quotes and paperwork

    You gather quotes or the building contract and plans. We tell you exactly what the lender needs so nothing holds it up.

  4. Step 4

    Valuation and approval

    The lender values the home, as it is or on completion, and approves the loan. We keep you posted at each step.

  5. Step 5

    Funds released, work starts

    A lump sum lands in your account or the builder is paid in stages. Kathryn and Sumit stay on it until the last payment.

Clients who built with us

  • Jaimie Sarwary

    11 months ago on Google

    Google

    I truly cannot express how amazing our experience has been with RyRo Loan Centre. Sumit and his team have gone above and beyond to make my mine and my husband’s dream of building our first home come true. They have been in constant communication throughout the process, explained everything in detail and have taken the stress away from finding a home loan. We had a very tight deadline and they made it work, even exceeded our expectations by having us approved for a much higher amount than an alternate broker advised. Sumit, we are forever grateful for your service, you have been an absolute pleasure to deal with!

    Jaimie Sarwary

    Google11 months ago on Google

    I truly cannot express how amazing our experience has been with RyRo Loan Centre. Sumit and his team have gone above and beyond to make my mine and my husband’s dream of building our first home come true. They have been in constant communication throughout the process, explained everything in detail and have taken the stress away from finding a home loan. We had a very tight deadline and they made it work, even exceeded our expectations by having us approved for a much higher amount than an alternate broker advised. Sumit, we are forever grateful for your service, you have been an absolute pleasure to deal with!

  • Vineeth Joseph

    3 years ago on Google

    Google

    Around five years ago, we were introduced to Sumit when we initially contemplated constructing a house. Sumit provided us with valuable financial guidance regarding the essential steps to initiate the house-build. Over the years, he has been a constant source of support, assisting us not only throughout the construction of our home but also during the challenging times of the COVID-19 pandemic. More recently, he helped us in refinancing our home loan. He has always offered pragmatic and honest recommendations that prioritise our best interests. Sumit greatly simplified the financial aspect, taking the time to explain the nuances involved in dealing with financial institutions. Sumit and his team have always been approachable and have promptly responded to our queries and requirements.

    Vineeth Joseph

    Google3 years ago on Google

    Around five years ago, we were introduced to Sumit when we initially contemplated constructing a house. Sumit provided us with valuable financial guidance regarding the essential steps to initiate the house-build. Over the years, he has been a constant source of support, assisting us not only throughout the construction of our home but also during the challenging times of the COVID-19 pandemic. More recently, he helped us in refinancing our home loan. He has always offered pragmatic and honest recommendations that prioritise our best interests. Sumit greatly simplified the financial aspect, taking the time to explain the nuances involved in dealing with financial institutions. Sumit and his team have always been approachable and have promptly responded to our queries and requirements.

Ready to start? The first call is free and there is no obligation.

Start with a free strategy call
Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan Centre · every step until settlement

Google reviews

What Homeowners Say About Us

Real Google reviews of RyRo Loan Centre, word for word.

Google

5.0

From 360+ Google reviews

Sumit · 2:59
From two properties to four in six monthsSumit Joshi, RyRo Loan Centre
Read all 360+ Google reviews
  • Gurbaksh Dhillon

    2 years ago on Google

    Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

    Gurbaksh Dhillon

    Google2 years ago on Google

    Sumit and his team are exceptionally knowledgeable about the mortgage process. They secured an excellent refinancing deal for me with minimal documentation required, making the submission process straightforward and hassle-free. Every team member was professional, courteous, and approachable. I highly recommend their services.

  • Sanjay Wadhwani

    2 years ago on Google

    Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

    Sanjay Wadhwani

    Google2 years ago on Google

    Sumit and his teams were absolutely amazing throughout the whole process of refinancing our house and got us a best deal from one of the top 4 banks. Professionals who listen to customers needs with clear communication and sound advice. Highly recommend Sumit!

  • Varsha Mehra

    2 years ago on Google

    Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

    Varsha Mehra

    Google2 years ago on Google

    It was a wonderful experience dealing with Sumit Joshi and his team. Sumit was very informative, helpful, responsive and helped us purchase our new home. He was always available to answer any questions we have and really helped streamline the process for us. He guided us and being first home buyers we were completely amateurs and confused. Sumit explained things to us and made sure we understood them. Thank you.

  • Ajay Bhatia

    2 years ago on Google

    Google

    Sumit has recently helped us secure our SMSF loan plus refinance and we can’t recommend him highly enough. He makes the whole process stress-free with very clear and timely communications. He went above and beyond to help us secure our financing in a short timeframe. We won’t be going anywhere else for our future mortgage requirements. Thanks Sumit.

    Ajay Bhatia

    Google2 years ago on Google

    Sumit has recently helped us secure our SMSF loan plus refinance and we can’t recommend him highly enough. He makes the whole process stress-free with very clear and timely communications. He went above and beyond to help us secure our financing in a short timeframe. We won’t be going anywhere else for our future mortgage requirements. Thanks Sumit.

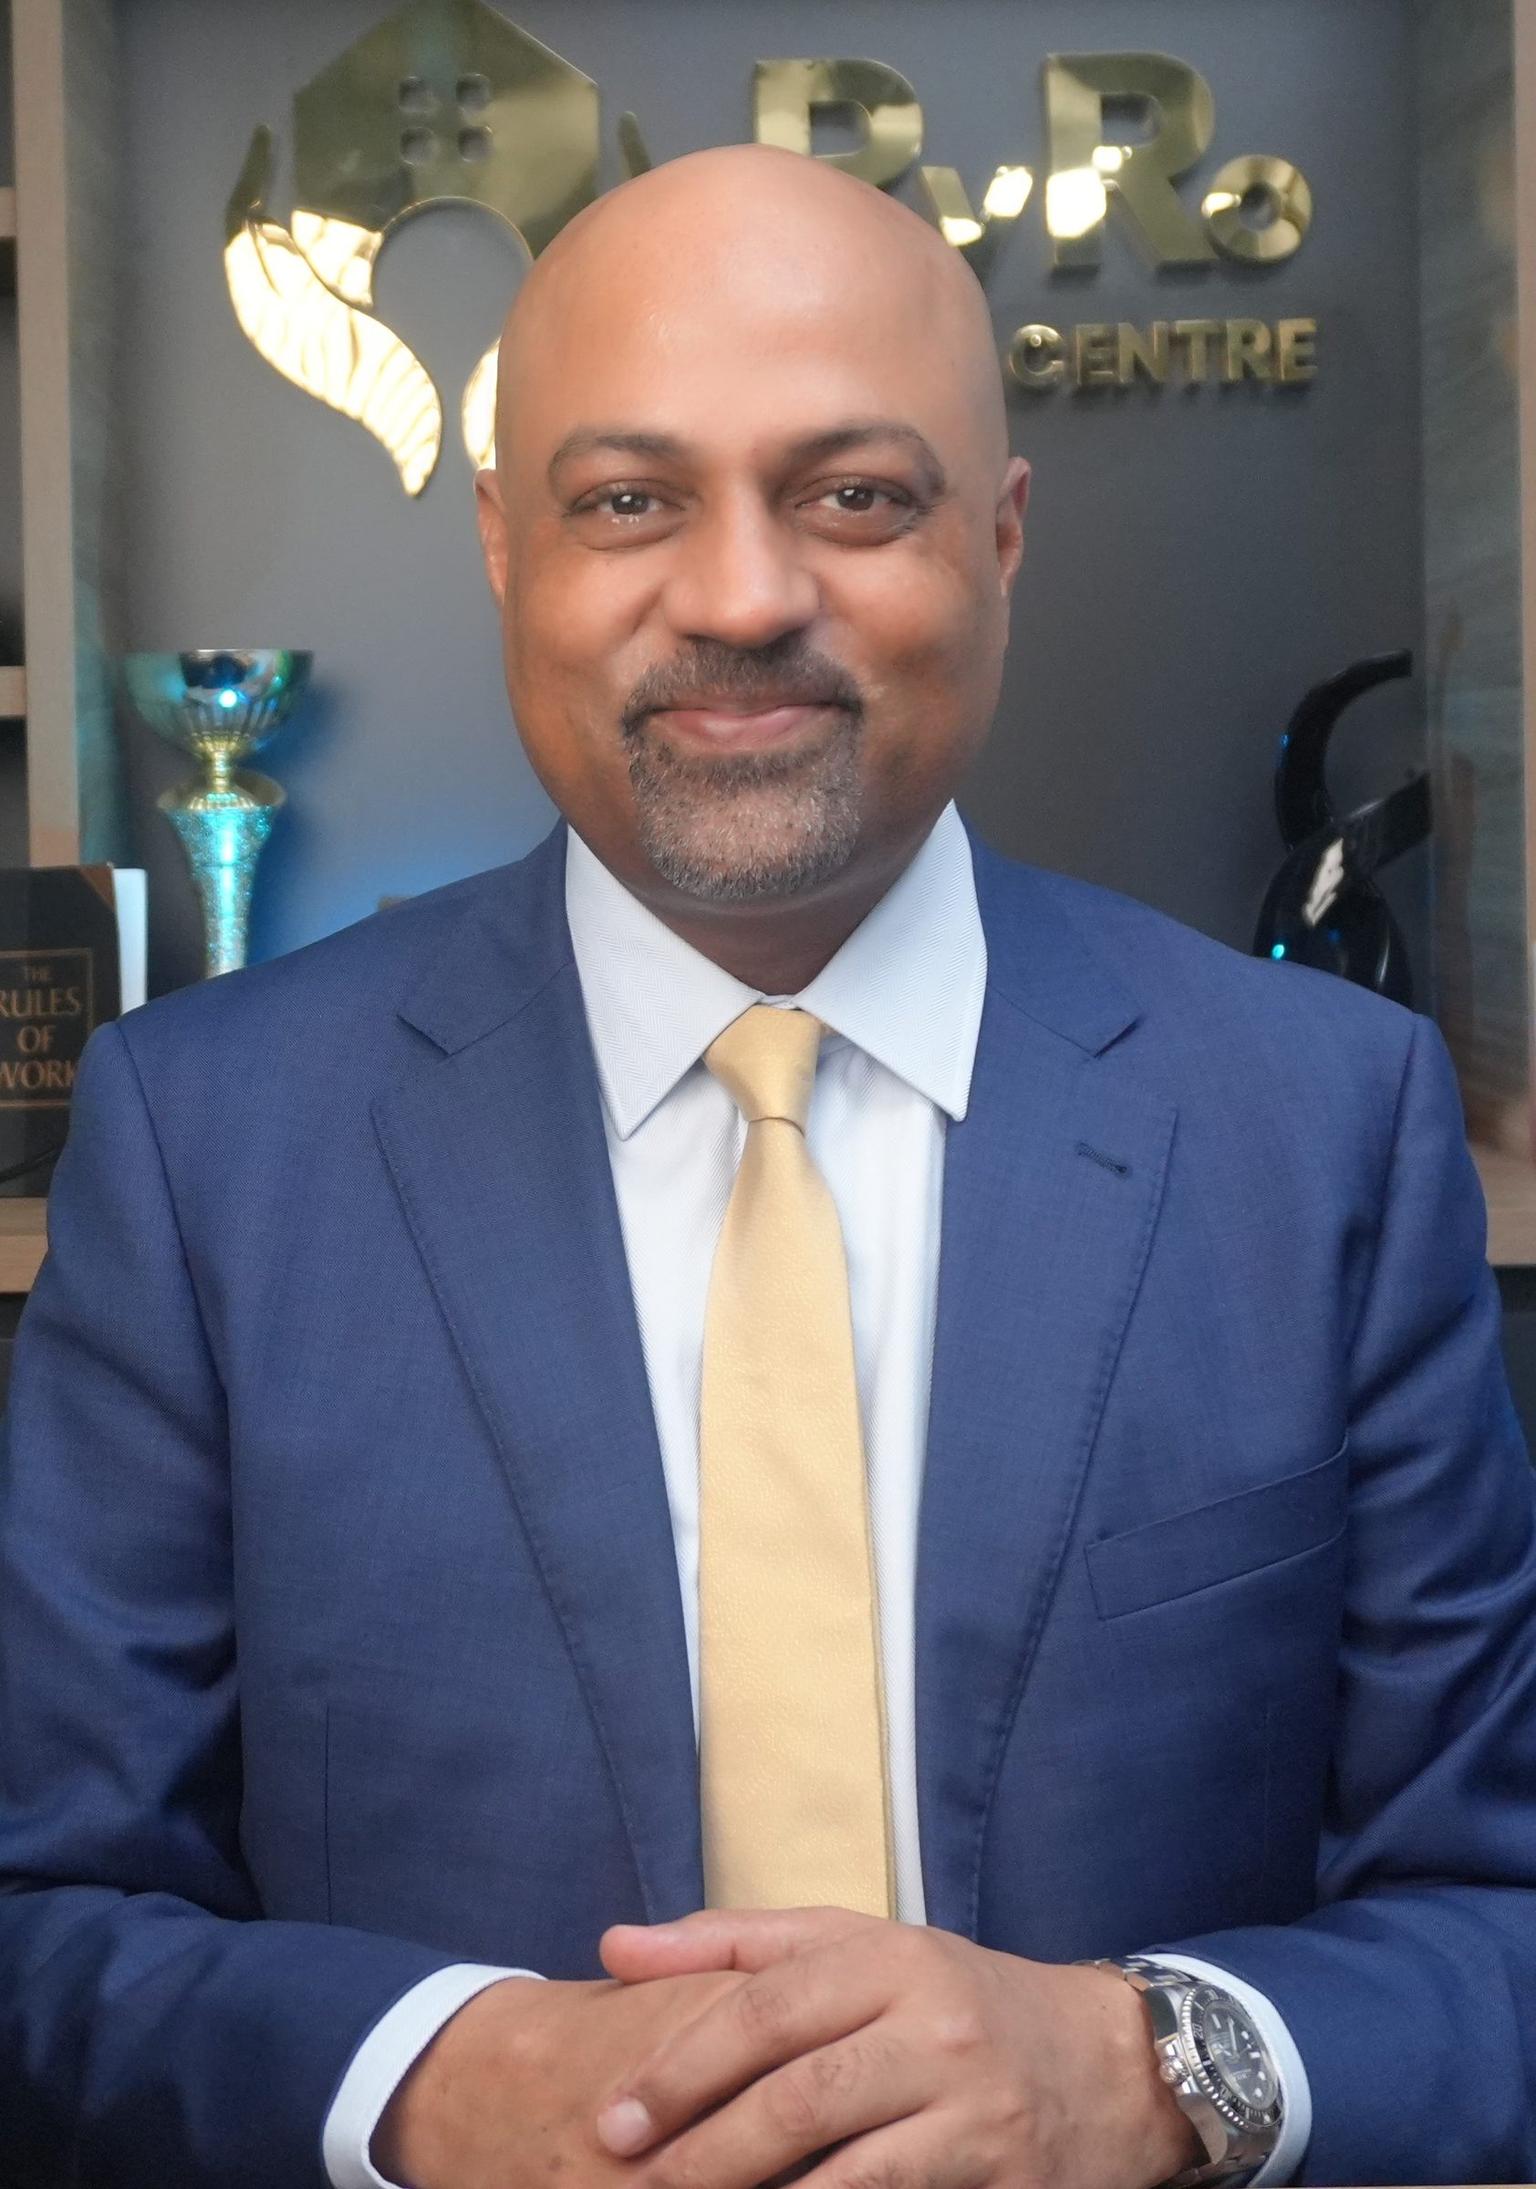
Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie
Sumit Joshi, 2020 Broker of the Year

Broker of the Year 2020Awarded to Sumit Joshi

Who you will deal with

The Ryro Team

Sumit Joshi JP · Principal broker · Credit Rep 446824

A renovation is exciting, and that is when people borrow in a hurry. I would rather slow it down, cost it properly and set the loan up so it is easy to pay off.

You deal with Sumit from the first call. He works out your equity, explains each funding route, compares lenders across the panel and stays on it until the money is released. Kathryn handles the paperwork with the lender.

We work from the Norwest office and help owners across the Hills District and all of Sydney. Not sure renovating is the right move? Our options for existing homeowners page compares renovating with upgrading.

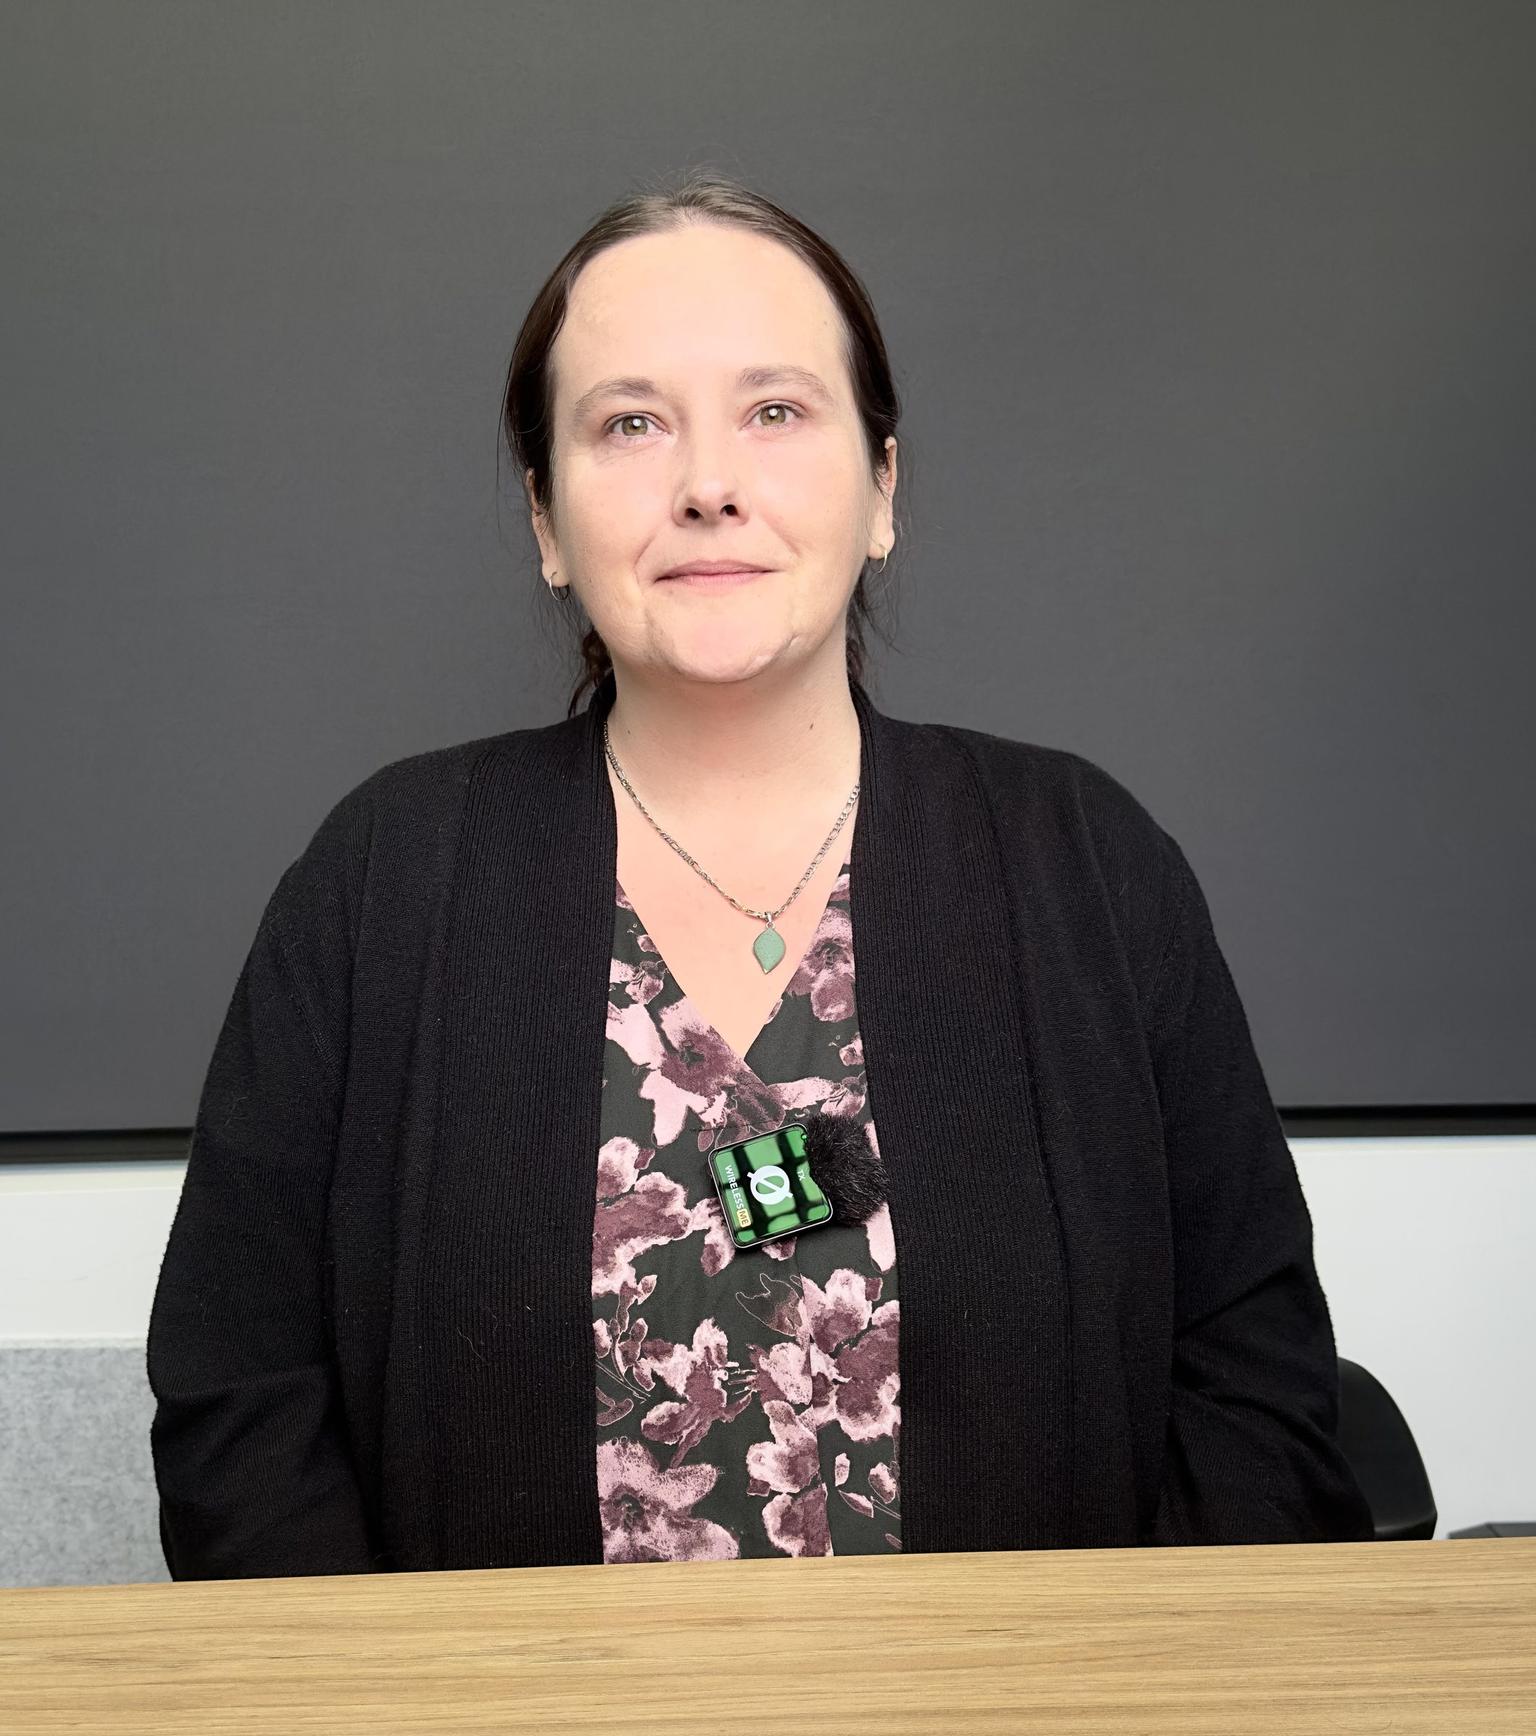
Kathryn Thomas, loan processor at RyRo Loan Centre

Kathryn ThomasSettlement and client liaison. Kathryn works with your conveyancer and the lender from exchange to settlement day.

  • We generally respond within an hour
  • Free strategy call, no obligation

Why Sydney borrowers choose RyRo

Rated by clients, recognised by lenders

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • MFAA 10 year member badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • AFG Excellence Awards finalist 2024 badge
  • AFG Excellence Awards finalist 2023 badge
  • AFG Excellence Awards finalist 2022 badge
  • AFG Award winner 2019 badge
  • AFG Award winner 2018 badge
  • AFG Award winner 2017 badge
  • AFG Award winner 2016 badge
  • AFG Award winner 2015 badge
  • AFG Award winner 2014 badge
  • AFG Award winner 2013 badge

AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026

Annaliza Benitez

a year ago on Google

Google

Sumit has been amazing through the whole process of refinancing our home loan. So professional and friendly. I highly recommend him to anyone who is looking for a mortgage broker!

Read all 360+ Google reviews

Free tools

Renovation Loan Calculators

Run your numbers before you talk to a lender. Each tool takes a minute and the result can go straight to Sumit.

Rated 5.0 from 360+ Google reviews. Sumit works through the figures based on your actual loan.

Check my numbers with Sumit

Answers on demand

Renovation Loan FAQs

The questions Sydney owners ask us most about funding a renovation: how much you can borrow, which loan suits the job and what the lender needs to see.

10 answers in 2 topics

Renovation loan basics

  • A renovation loan is any loan used to pay for work on your home. For most owners that means borrowing against the home itself: a top up on your current loan, a new split, a refinance to a lender that lends more, or a construction loan that pays the builder in stages for bigger structural work. Because the home secures the loan, these usually cost less than unsecured borrowing. We match the loan to the size of the job.

    Using your home equity
  • Start with the size of the job. Smaller, cosmetic work is often paid from savings in your offset, a redraw, or a top up on your current loan. Medium jobs such as a new kitchen and bathrooms usually come from your equity through a top up or a refinance. Large structural work such as an extension or second storey often needs a construction loan with progress payments. Get quotes first, then check your usable equity and borrowing power.

    Borrowing power calculator
  • Yes. You can move your loan to a new lender and borrow extra for the renovation in one application, as long as the new lender’s valuation and your income support the higher loan. It suits owners whose current rate is no longer sharp. If your current loan is already a good deal, a top up with your existing lender is often simpler. We compare both before you decide.

    Refinancing to renovate guide
  • It depends on two things: your usable equity and your borrowing power. Lenders often treat up to 80% of your home’s value, less what you owe, as usable equity before Lenders Mortgage Insurance applies, though that is a convention, not a rule. Your income, debts and living costs then decide how much of that you can actually borrow. For bigger jobs, some lenders assess the value once the work is finished.

  • Not always. Cosmetic work such as a kitchen, bathroom, flooring or painting can usually be funded with a top up or equity release paid out as a lump sum. Structural work, such as an extension, a second storey or a major rebuild that needs council approval, often needs a construction loan. It releases money to your builder in stages as each part is finished, and you pay interest only on what has been drawn.

    Construction loans

Valuations, quotes and paperwork

  • Yes, if you have money in either. Using an offset balance means the loan balance it was offsetting starts costing you interest again. Redraw takes back extra repayments you made, and some lenders limit or charge for redraws. Both avoid a new application, so they suit smaller jobs. For bigger work, many owners keep the renovation money in its own split so it is easy to track.

    Offset vs redraw explained
  • Sometimes. For a small job the lender usually values your home as it is today. For larger work with a fixed price contract and plans, some lenders order an on completion valuation, which estimates the value once the work is finished, and lend against that. Not every lender offers this and the valuer may not agree with your estimate, so we check the lender’s policy before you apply.

  • The usual income and expense documents for a home loan, plus details of the work. For a small job, a quote or a builder’s estimate is often enough. For larger work, lenders usually ask for a signed fixed price building contract, plans and specifications, council approval where it is needed, and the builder’s licence and insurance details. Getting these ready early saves weeks.

  • Some lenders do lend to owner builders, but fewer of them, and they usually ask for a larger deposit or more equity and a detailed costing. In NSW you need an owner builder permit for building work worth more than $10,000 on your own home when you are not contracting a licensed builder (NSW Government, checked November 2026). Talk to us before you commit to owner building, so the finance is lined up first.

  • A personal loan can be quick for a small job and does not touch your home loan, but it usually has a higher rate and a much shorter term, so repayments are higher. Borrowing against your home usually costs less per year but is spread over a longer term, so you can pay more interest overall unless you pay it down fast. RyRo arranges home loan based renovation finance, not unsecured personal loans.

    Loan repayment calculator
View all FAQs

Talk to Sumit

Ready to Fund Your Renovation?

Join 2,500+ Australians who've trusted RyRo Loan Centre with their lending. $0 fees on home loans. Plain advice. No credit check.
Sumit Joshi, principal broker at RyRo Loan Centre

Plan My Renovation Loan

We'll call you to talk through the job and your loan. No obligation, no credit check.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reads your details and calls you back
  • No obligation and no credit check
  • Free for home loans: the lender pays us
Sumit · 1:18
Cheaper rate or the right strategy?Sumit Joshi, RyRo Loan Centre

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Renovation questions answered on this page
10
“Amazing service!!! Sumit always guided us about how to manage our finances and investments. He was always available to answer our questions- in person or over the phone. I recognise how time consuming this must be for him; but at no time has he made us feel that it was an inconvenience to him. He not only gave us the best product at the best rate, that suited our refinancing and investment needs but also made the whole process so easy and smooth. We highly recommend their services to anyone who is looking for a good and reliable mortgage broker.”
Vandana Kanwar · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026.

Get my free loan review